Market Movers: Urgency
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 6 minutes
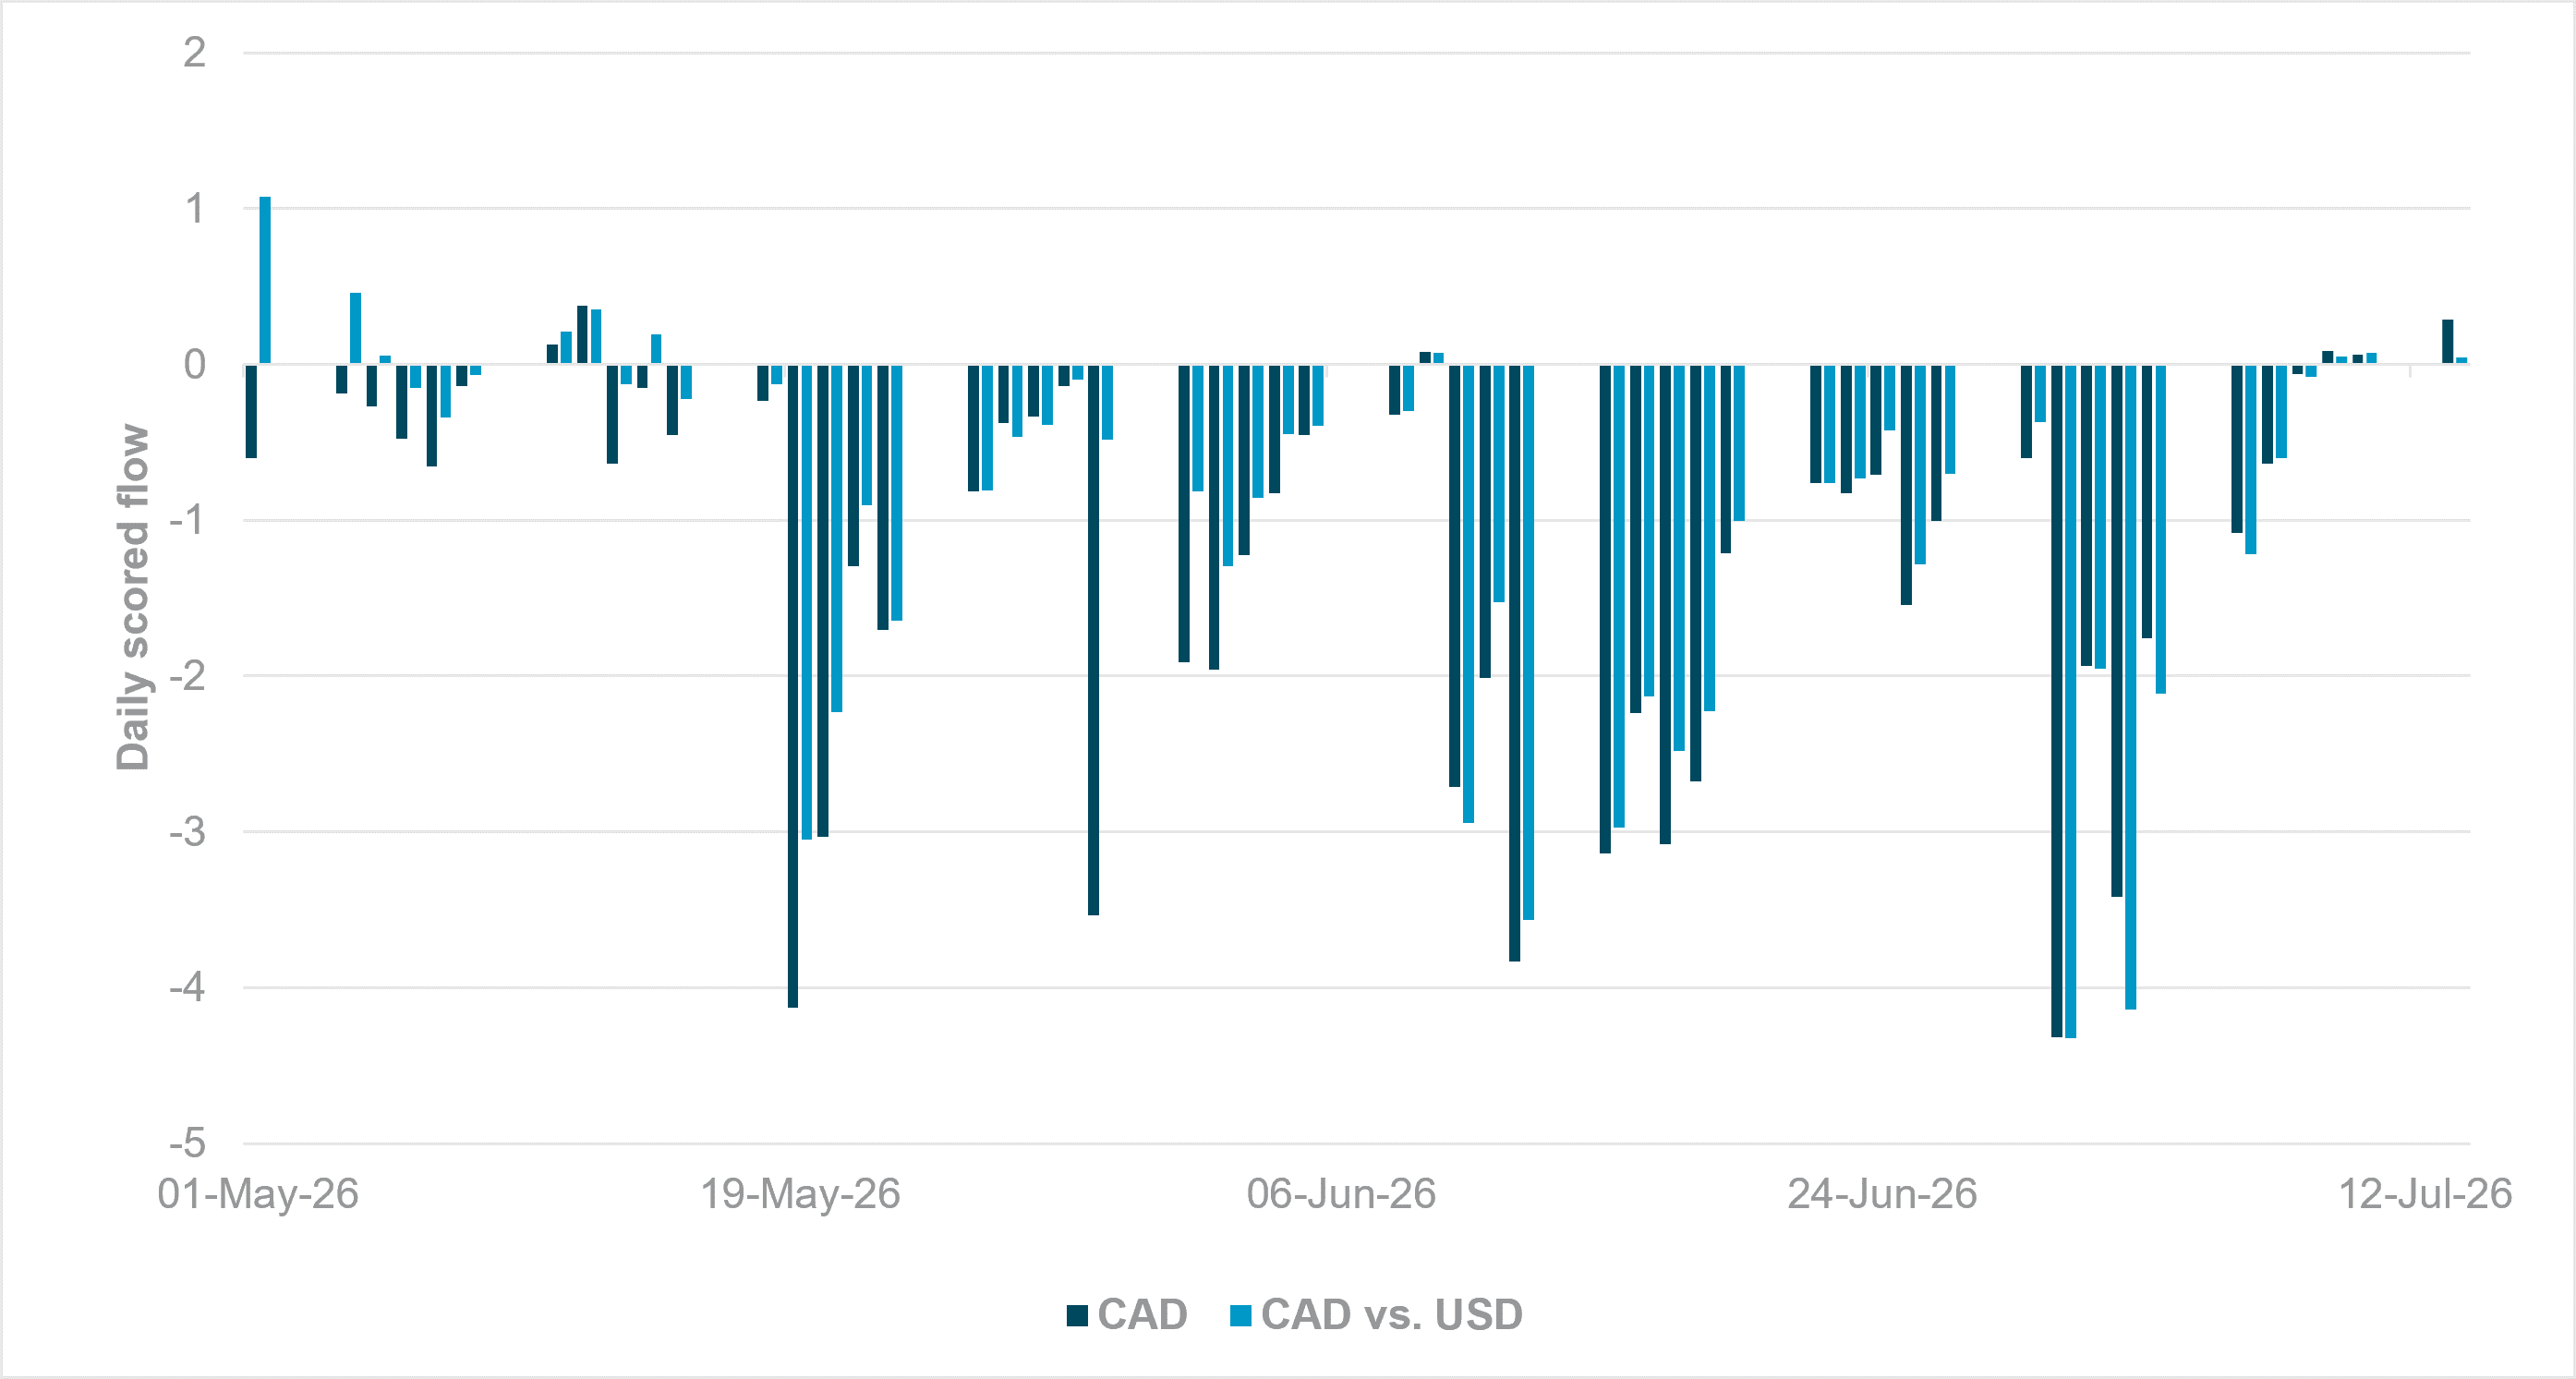
Very light CAD purchases finally emerging ahead of BoC meeting
Source: BNY, GPIF
Ahead of today’s BoC decision, our data show that selling of CAD-denominated accounts has finally eased, allowing light aggregate CAD purchases to emerge after a long period of pressure. BoC pricing will continue to weigh on performance, but flows and asset holdings now appear to reflect that policy backdrop more fully, creating room for value to emerge. Higher energy prices may help at the margin, though CAD and Canadian equity flows rarely align closely with crude swings. In aggregate forwards and swaps, the buying remains tentative, but the shift in momentum is clear after relentless selling.
The key question is whether this can develop into a more durable purchase trend. CAD’s two-month rolling flow average remains extremely weak at close to -1.5, a level usually associated with severe risk aversion. If the bad news is already reflected in the price and onshore investors now see grounds to add hedges on overseas assets, the path is open for a more meaningful reversal. USDCAD selling has driven much of the improvement, suggesting CAD-based investors are no longer adding USD exposure after extreme inflows in late June. We would add CAD exposure selectively, not aggressively, given that valuations and positioning are supportive but domestic selling and weak underlying Canadian asset flows are still limiting upside.
Softer CPI numbers and Kevin Warsh’s testimony have provided relief, but not an all-clear: The lull in financial conditions may be brief. U.S. Central Command said the country’s forces began striking Iran at 6am ET today, putting oil back at the center of macro risk. Hormuz remains the channel from escalation to inflation, supply risk and central bank reactions. Today’s U.S. PPI data will show whether price pressure is broadening, but protection cannot wait for confirmation.
China has stepped up its policy urgency: Q2 GDP slowed to 4.3%, with weak domestic demand and property drag offset mainly by exports and high-tech production. Beijing is not facing collapse, but its growth mix is too export-dependent and exposed to trade friction. The case for reflation is stronger.
Japan is making the urgent need to act explicit: Prime Minister Sanae Takaichi has warned that “if we don’t build a strong economy now, it will be too late.” The window to boost investment, wages and strategic capacity is narrowing.
Earnings are still vindicating the growth drivers: U.S. and global results are supporting the AI, semiconductor and capex story, but multiples are rich and leadership concentrated. Earnings will need to justify extended positioning while macro risk looms large.
The bottom line is that urgency cuts both ways: The U.S. inflation relief rally has opened up a narrow window, but oil, China’s demand shortfall and Japan’s growth push are already testing it. Investors would be wise to stay protected against geopolitical and inflation spillovers while policymakers still have room to act.
Japanese Prime Minister Sanae Takaichi has warned that if Japan does not build a strong economy now, it will be too late, pushing back against concerns that her government’s draft economic blueprint triggered the recent JGB selloff. Takaichi said that she saw no link between an unapproved government document and the market shock that drove bond yields to multi-decade highs, arguing that interest rates and FX moves reflect multiple factors, including U.S. rates and employment data. Her comments follow concerns that the blueprint could imply political pressure on monetary policy. She also framed temporary food sales tax cuts as a chance to create a more flexible consumption tax system, while saying domestic investment and competitiveness are key to supporting the yen. Nikkei +1.49% to 68752, USDJPY +0.031% to 162.3, 10y JGB -2.4bp to 2.695%.
ECB officials Piero Cipollone and Martin Kocher have both signaled that the central bank is focused on preventing the energy shock and Middle East uncertainty from feeding into broader inflation dynamics, rather than treating imported price pressure as a reason for automatic tightening. Cipollone said the ECB is seeing the direct impact of higher energy prices and some indirect passthrough to production costs, but not yet second-round effects from wages or corporate pricing behavior. Kocher echoed that view, saying the ECB is not seeing second-round inflation for now, though policy must remain calibrated to expectations amid elevated uncertainty. Both comments point to a data-dependent stance, with the ECB ready to act if inflation expectations become less anchored, while keeping the option of holding or raising rates open. However, Bundesbank President Joachim Nagel reiterated the need for vigilance. Euro Stoxx 50 +0.06% to 6284, EURUSD +0.035% to 1.1424, BBG AGG Euro Government High Grade EUR +0.7bp to 3.366%.
China assessment of its H1 economic performance remains broadly constructive. The National Bureau of Statistics stated that the economy “operated within an appropriate range” despite external pressures, highlighting faster production, stable employment, mild price increases, solid foreign trade and rapid development of new growth drivers. GDP grew more softly than expected at 4.7% y/y in H1 (Q1: 1.3% q/q, 5.0% y/y, Q2: 0.9% q/q, 4.3% y/y), indicating some moderation in momentum. The assessment acknowledges that the external environment has become “increasingly unstable and uncertain” (vs. May: “complex and volatile”), while domestic demand remains insufficient relative to supply. The NBS expects prices to “increase mildly” vs. “generally stable” in May. The policy guidance stepped up the rhetoric on counter-cyclical and cross-cyclical adjustment (June: “to step up” vs. May: “enhance”), but with a stronger emphasis on building a robust domestic market, accelerating new growth drivers and supporting employment, businesses, markets and confidence. Overall, the tone remains supportive without materially changing the underlying policy stance. CSI 300 -0.2% to 4787, USDCNY -0.009% to 6.771, 10y CGB +0.1bp to 1.734%.
The BoC has said it will not provide Wednesday’s rate decision to media on an embargoed basis after a planned protest in support of striking security guards. As a result, headlines and reporting on the decision may be delayed until the announcement is posted on the bank’s website at 9:45 a.m. New York time. The BoC is expected to keep rates unchanged at 2.25%. Markets are expecting no change at least until Q4 but easing could be on the agenda with any renewed downside surprises to inflation. The recent pick-up in core inflation and labor market improvements suggest the status quo is adequate but, as Governor Tiff Macklem noted, the central bank is prepared to “take action” if the situation changes on inflation expectations. TSX 60 Future -0.08% to 2088, USDCAD -0.029% to 1.4055, 10y CGB +0.8bp to 3.573%.
Reports in the U.K. suggest Andy Burnham is increasingly unlikely to appoint Ed Miliband as chancellor, with Shabana Mahmood now seen by some MPs and allies as the frontrunner for the Treasury. The debate has become an early test of how Burnham intends to govern, with markets and business focused on whether his economic team will signal fiscal caution or a sharper leftward shift. Miliband is viewed by supporters as experienced and close to Burnham, but critics see him as divisive, market-unfriendly and vulnerable to attacks over net zero, North Sea energy policy and job creation. Mahmood would be read as a more reassuring choice for the City, though no final decision has been announced ahead of Burnham entering No. 10. FTSE 100 -0.22% to 10506, GBPUSD +0.053% to 1.3397, 10y gilt -1bp to 4.967%.
Bank of Canada is expected to hold rates unchanged at 2.25%.
U.S. July Empire Manufacturing is forecast to rise to 9.2 vs. 5.7.
U.S. June PPI final demand is forecast at 0.0% m/m, 6.2% y/y vs. 1.1% m/m, 6.5% y/y in May; PPI ex food and energy is forecast at 0.3% m/m, 5.2% y/y vs. 0.4% m/m, 4.9% y/y in May; PPI ex food, energy and trade is forecast at 0.3% m/m, 5.2% y/y vs. 0.8% m/m, 5.1% y/y in May.
Canada May manufacturing sales are forecast to ease to 1.1% m/m vs. 4.2% m/m.
Canada May wholesale sales ex petroleum are forecast to fall to -0.7% m/m vs. 0.6% m/m.
Central bank speakers: Fed Chair Kevin Warsh testifies before the Senate Banking Committee; the Fed’s John Williams delivers keynote remarks; the Fed’s Lisa Cook speaks on the economic outlook; the Fed releases its Beige Book; the ECB’s Joachim Nagel speaks in Stuttgart.
U.S. Treasury sells 17-week bills.
Mood: iFlow Mood continued its downward trajectory to -0.155, as sovereign bonds continued to see inflows at the expense of global equities.
FX: FX Flows were well-balanced and limited, with SEK, AUD and NOK registering inflows while NZD, HUF and KRW saw modest outflows
FI: Global investor demand for sovereign bonds was strong, with sizable inflows into U.S., Eurozone and Indian government bonds. There were modest outflows from Chilean and Thai bonds
Equities: Global equity flows were mixed, with inflows into Turkish, Indian and Thai equities while Singapore and Colombian equities leaned toward selling.
“You may delay, but time will not.” – Benjamin Franklin
“Things don’t just happen. Things are made to happen.” – John F. Kennedy
Euro area industrial production fell 0.2% m/m and 1.2% y/y in May (initial estimates), while EU output declined 0.1% m/m and 0.3% y/y. The m/m fall followed gains in April and reflected weaker intermediate goods and durable consumer goods production, partly offset by higher energy, capital goods and non-durable consumer goods output. On a y/y basis, capital goods and energy rose, but sharp drops in non-durable consumer goods and durable consumer goods dragged on overall activity. Among member states, Ireland posted the steepest m/m and y/y declines, while Luxembourg, Hungary and Poland recorded the strongest monthly gains. Euro Stoxx 50 +0.06% to 6284, EURUSD +0.035% to 1.1424, BBG AGG Euro Government High Grade EUR +0.7bp to 3.366%.
Spanish inflation came in at 3.2% y/y in June, unchanged from May, while the core rate eased to 2.9% from 3.0%. Consumer prices rose 0.6% m/m, driven mainly by housing, where electricity and gas pushed prices higher, as well as recreation and tourism packages, and hotels and restaurants. Transport was the main detractor, as fuel prices fell. The harmonized index also held steady at 3.6% y/y, with the m/m rise also at 0.6%. Inflation was positive in all autonomous communities, led by Madrid at 3.8% and then Extremadura at 2.4%. IBEX 35 -0.66% to 19231, EURUSD +0.035% to 1.1424, 10y Bono +0.5bp to 3.576%.
Swedish CPI inflation came in at 0.7% y/y in June, easing from 0.8% in May, while the m/m rise was 0.4%. The CPIF, the Riksbank’s target measure, also moderated to 1.3% from 1.5%, and CPIF excluding energy slowed to 0.4%. Statistics Sweden said the m/m increase was driven by seasonal gains in package holidays, car rental and air fares, partly offset by lower fuel, clothing and food prices. On a y/y basis, higher electricity, fuel and package holiday prices supported inflation, while food and dental services weighed on it. OMX -0.05% to 3161, EURSEK +0.143% to 11.0536, 10y Swedish GB +1.8bp to 2.939%.
Norwegian CPI for June came in at 2.7% y/y, while the CPI-ATE measure was also 2.7% y/y, with headline prices falling 0.2% m/m on a broad easing across goods categories. The m/m decrease was led by information and communication (-3.2%), clothing and footwear (-1.8%) and consumer goods (-1.1%), while furnishings also fell 0.9%. Services remained firmer, rising 0.4% m/m and 2.6% y/y, with restaurants and accommodation up 0.9% m/m and 6.0% y/y. Insurance and financial services remained the strongest annual component at 8.9%. CPI-AT was higher at 4.1% y/y but fell 0.5% m/m. OSE +0.1% to 1966, EURNOK +0.445% to 11.1189, 10y NGB -2.4bp to 4.38%
Polish consumer prices rose 2.5% y/y and fell 0.5% m/m in June. The annual reading matched the flash estimate and was precisely in line with the National Bank of Poland’s inflation target of 2.5% +/-1 percentage point. Services prices increased by 5.4% y/y, while goods rose 1.3%. On a m/m basis, transport drove the decline with a 4.4% drop, followed by food and non-alcoholic beverages (-0.7%) and clothing and footwear (-1.7%). By contrast, recreation and culture, restaurants and accommodation, and alcohol and tobacco posted increases, limiting the overall fall. WIG +0.16% to 144004, EURPLN +0.04% to 4.3273, 10y PGB +5.9bp to 5.489%.
Japan’s machinery orders report for June showed a weaker reading m/m, although the basic assessment was left unchanged. Core private sector orders excluding ships and electricity fell 12.4% m/m after an 8.7% m/m increase in the prior month, marking the first decline in two months. The three-month moving average also remained negative at -4.8% m/m. The Cabinet Office said machinery orders, a leading indicator for private capital spending, are still showing signs of recovery; May’s drop was treated as a one-off move following the strong rebound in April. The overall tone was unchanged: “a moderate recovery trend is visible.” Nikkei +1.49% to 68752, USDJPY +0.031% to 162.3, 10y JGB -2.4bp to 2.695%.
Japan’s tertiary industry activity index rose 1.1% m/m, 1.5% y/y in May, indicating a firmer service sector backdrop. Broad-based personal services improved by 0.6% m/m, and business services gained 2.0% m/m. The main m/m contributors were information and communications (3.1% m/m, 2.0% y/y), finance and insurance (3.4% m/m, 13.7% y/y) and retail trade (1.9% m/m, 4.1% y/y), alongside gains in business-related services, leisure-related services, utilities and transport/postal activities. Offsetting the rise, real estate dipped 0.5% m/m and wholesale trade was slightly weaker. Overall, the report points to continued expansion in Japan’s tertiary sector, with strength led by digital, financial and consumer-facing services.
China’s H1 data showed a widening gap between resilient production and weak domestic demand. Industrial value added rose 5.4% y/y YTD, with manufacturing up 5.6% and high-tech manufacturing much stronger at +13.3%. June output accelerated to 5.3% y/y from 4.5% in May, while production of 3D printing devices, lithium-ion batteries and industrial robots rose 48.5%, 39.3% and 28.0% y/y, respectively. Profits also improved, rising 18.8% y/y in the first five months of the year. By contrast, consumption remained soft: H1 retail sales of goods and services rose 2.7% y/y, led by services, while consumer goods sales rose only 1.3%. Autos and home appliances remained clear drags. CSI 300 -0.2% to 4787, USDCNY -0.009% to 6.771, 10y CGB +0.1bp to 1.734%
China’s investment and property data point to the main weakness in the economy. Fixed-asset investment excluding rural households fell 5.7% y/y in H1, with primary industry investment up 0.9%, but secondary and tertiary investment down 1.1% and 8.4%, respectively. Infrastructure, manufacturing and private investment all contracted, while real estate development investment fell 18.0%. Property activity remained under severe pressure, with new starts down 23.4%, completions down 23.7%, sales by area down 11.6% and sales by value down 13.6%. Housing prices showed some tentative stabilization at the margin, especially in tier-one cities, but y/y declines persisted across most city tiers.
Chinese labor and credit data were more stable, but not strong enough to offset the domestic demand picture. The surveyed urban unemployment rate averaged 5.2% in H1 and eased to 5.0% in June, while migrant worker numbers had risen 0.5% y/y by end-Q2. Total social financing grew by 7.4% y/y to ¥462.06tn, although H1 incremental financing was ¥2.02tn lower than a year earlier. M2 rose 8.0%, RMB loans increased by ¥10.72tn and deposits rose ¥17.76tn, but household loans declined, reinforcing the consumer caution narrative. Overall, China’s economy remains production-led, with high-tech manufacturing and credit stability cushioning persistent weakness in consumption, property and private investment.
South Korea’s preliminary trade price and volume data for June showed a strong surge in exports and softer import prices. In KRW terms, the export price index was flat m/m but rose 48.9% y/y, while the import price index fell 4.4% m/m but still increased by 20.6% y/y. In USD terms, exports rose 29.8% y/y by volume and jumped 74.8% y/y by value, in a sharp improvement from May. Imports increased by 12.0% y/y by volume and 30.5% y/y by value. The net barter terms of trade improved by 15.6% y/y, supported by exports rising much faster than imports in value terms. Overall, the release points to stronger external price competitiveness and robust trade momentum in June, despite a m/m decrease in import prices. KOSPI +6.24% to 7284, USDKRW +0.098% to 1491.3, 10y KTB +7.3bp to 4.34%.
South Korea’s labor force growth grew modestly in June, with stable unemployment alongside slight declines in participation and employment intensity. The economically active population rose 0.2% y/y to 29.988 million, while the labor force participation rate edged down 0.2 percentage points y/y to 65.2%. Employment also increased by 0.2% y/y to 29.154 million, but the employment-to-population ratio slipped 0.2 percentage points y/y to 63.4%. Unemployment was little changed: the unemployment count rose 1.2% y/y to 834k, while the unemployment rate held steady at 2.8% y/y. Meanwhile, the economically inactive population stood at 16.152 million in April, up 1.1% y/y.
New Zealand card transaction figures show retail spending fell 1.4% m/m in June (-1.5% in core retail), led by weaker durables, hospitality, fuel and apparel, partly offset by small gains in motor vehicles and consumables. The non-retail category also declined, while services rose modestly. Overall card spending, including non-retail categories, fell 1.2% m/m. Across the June quarter, retail spending was broadly flat, with gains in fuel, durables and consumables offset by weaker hospitality, motor vehicles and apparel; overall card spending rose 0.5% q/q. The release says card transactions are a proxy for consumer spending and economic activity. NZX 50 -0.12% to 13635, NZDUSD +0.104% to 0.5821, 10y NZGB +1.8bp to 4.68%.