Market Movers: Tension
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 6 minutes
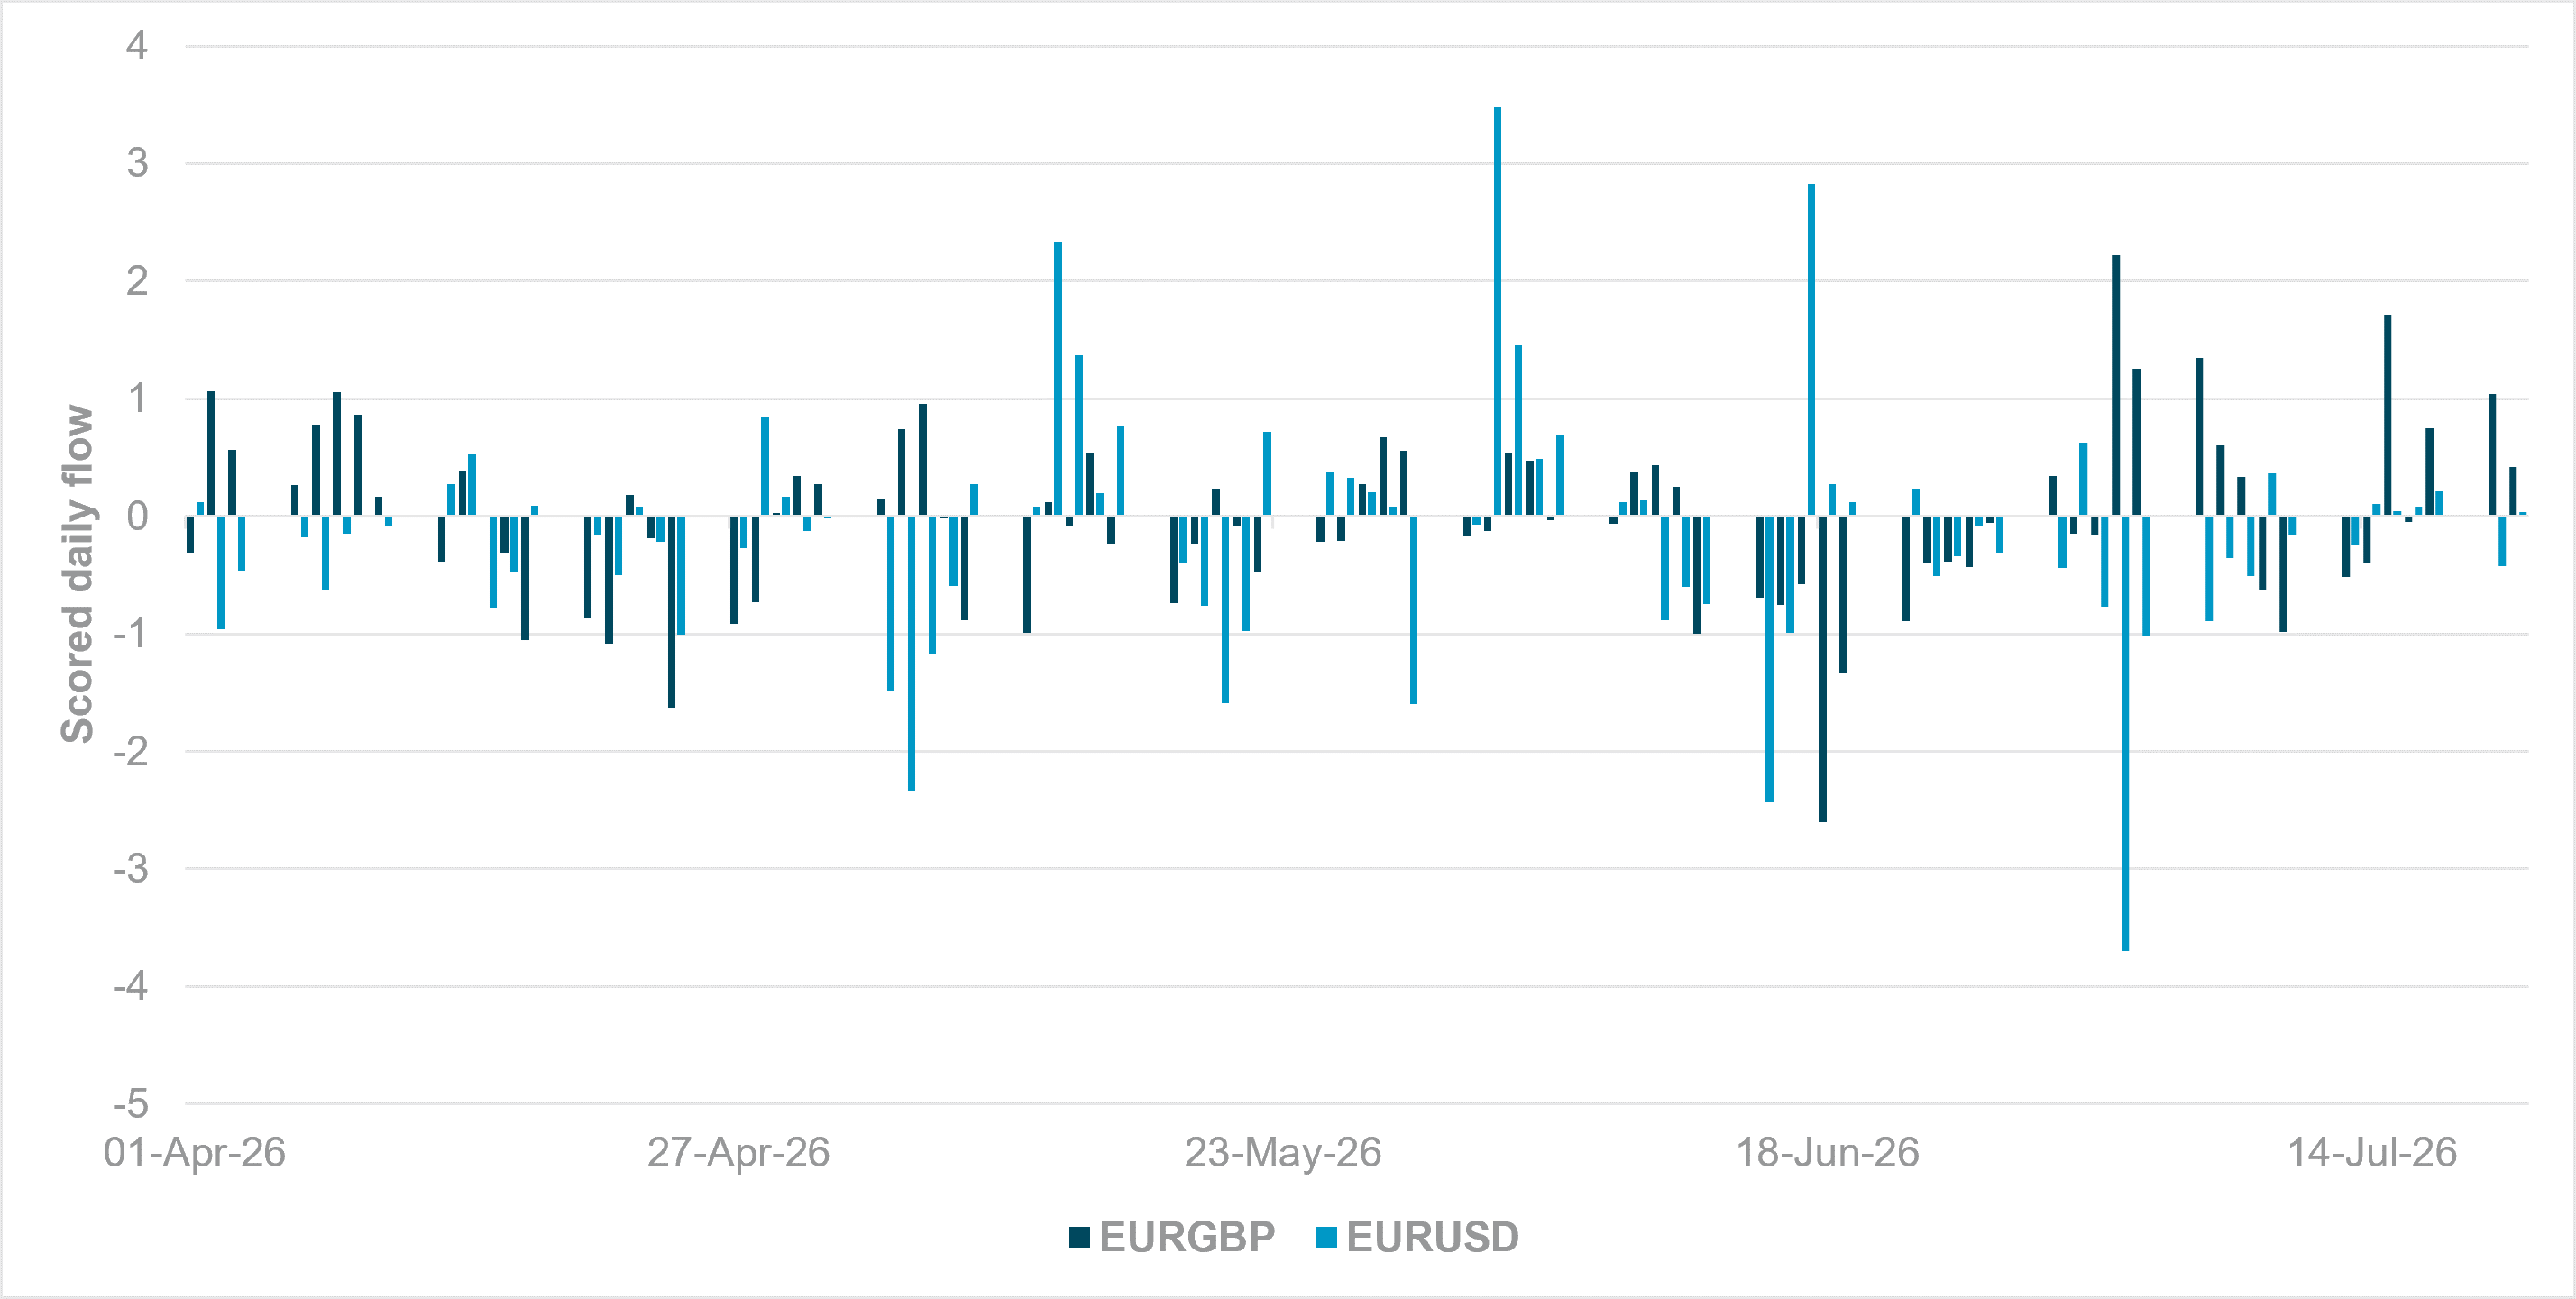
EURGBP vs. EURUSD flow
Source: BNY
EUR is finding a steadier footing ahead of today’s ECB decision, but the recovery is still incomplete. Spot flow is improving and hedge unwinding continues to support the currency, reinforcing the broader Eurozone asset recovery story. The move is not yet backed by strong forward or swaps demand, however, and this matters because EUR holdings still need meaningful recovery flow before they return to more normal levels. The ECB remains the key near-term test. Tightening expectations are rising globally, but EUR may get less incremental support because ECB pricing was already relatively strong versus European peers.
The cross picture is also important. EURUSD is drawing light bids, but the flow signal remains thin. EURGBP looks more attractive on a risk-reward basis, even though it is facing net sales this week, because current holdings have struggled more sharply and leave greater scope for recovery if GBP momentum fades.
Hedge unwinding is the clearest source of EUR resilience. Cross-border hedging is continuing to decline, and net exposure to Eurozone assets is at its highest level in more than two years. Still, onshore investors are not yet forward-buying EUR, which is limiting conviction. Overall, this is a recovery led by spot demand and lighter hedging, not a full rebuild. The ECB needs to tread carefully, as real yields are supporting bonds but equity flows are continuing to weaken under tighter financial conditions and supply shock pressure.
Oil and rates tension: Brent is in the high $90s. European natural gas is back at 2026 highs. Renewed U.S.-Iran escalation and Houthi attacks have revived disruption risk around the Strait of Hormuz and the Red Sea. Bond markets are treating this as an inflation shock rather than a conventional risk-off event. Treasury, Bund and gilt yields are rising as investors price in a more persistent energy shock and put additional tightening back into global curves.
ECB tension: The ECB faces a poor set of choices. Holding rates would avoid tightening directly into weak growth and a supply shock, but it could look too relaxed relative to market pricing of at least two hikes by year-end. A hawkish hold would protect credibility but deepen pressure on European demand, industrial margins and bonds. The key question is whether September remains live for a hike. We favor a greater focus on growth risks.
Risk appetite tension: Asia managed to rally. Semiconductors and AI-linked names led the move, with South Korea particularly strong. Europe is trading the other side of the shock. Technology shares weakened after disappointing guidance, while higher energy costs and yields are reinforcing the region’s weaker growth and margin outlook. Asia still needs earnings validation; Europe needs relief from the supply shock.
U.S. tests: Initial jobless claims are the immediate rates catalyst. A resilient print would support the growth story but leave little reason to unwind hike expectations. Intel reports after the close, which will be the next test of whether AI and data center investment is producing credible revenue, margins and guidance, and not just higher capex.
Bottom line: Oil is tightening financial conditions before central banks have resolved the trade-off between inflation and growth. Asia can still trade the technology cycle, but Europe is absorbing the energy and rates shock. Jobless claims, the ECB decision and tech earnings now need to provide stabilization; otherwise, oil close to $100 and rising yields remain a stagflationary and risk-dampening combination.
A Houthi spokesman said the group had targeted two oil tankers in the Red Sea. This widens the Iran conflict into a key shipping corridor just as the Red Sea becomes a workaround for crude exports disrupted by tensions around the Strait of Hormuz. The reported tanker strike off the coast of Saudi Arabia pushed Brent above $96/barrel, adding to concerns that the war is moving from regional military escalation into a broader energy and inflation shock. The U.S. responded with a 12th consecutive night of strikes on Iran, targeting missile, drone, surveillance and air defense assets, while warning that bombing will intensify until shipping routes reopen. With neither Washington nor Tehran showing much willingness to negotiate, the risk is that attacks on vessels and infrastructure will keep energy prices elevated. Brent +4.114% to 97.94, WTI +3.179% to 89.59, Omani crude +9.269% to 97.5, Dubai crude +1.504% to 77.685.
Crop prices have hit a three-year high, as heatwaves and escalating attacks in the Black Sea have intensified supply fears and revived food inflation risks. The Bloomberg Agriculture Spot Index, which tracks ten major crop products, reached its highest level since July 2023 after a seven-week advance. Meanwhile, Chicago wheat futures climbed to a fresh two-year high, and soybean and palm oil prices also rallied. The report said the conflict is disrupting trade from a region that supplies more than a quarter of global wheat exports, while extreme heat in Europe is threatening corn and other crops. It also noted that higher crude prices are boosting demand for biofuel feedstocks, adding to upward pressure across the food chain. Wheat -0.319% to 703.5, hogs +0.256% to 88.35.
Republicans in the U.S. House of Representatives have adopted a $95bn Republican-only budget package aimed at funding the Iran war and advancing President Trump’s priorities. It was passed 216-214, with all Democrats voting against and a few GOP defections. The plan includes $60bn for the Pentagon, $13bn for other national security needs, $12bn for farmers hit by Trump’s tariffs and $10bn for voting law changes tied to the SAVE America Act and proof-of-citizenship requirements. Speaker Mike Johnson is using the reconciliation process to bypass a Senate filibuster, but the package faces uncertainty in the Senate, where some Republicans want spending offsets and others prefer more defense funding. Democrats have blasted the measure as war spending at the expense of domestic needs. Senate Majority Leader John Thune is focused first on avoiding a government shutdown before the September 30 funding deadline. S&P Mini -0.57% to 7498, DXY -0.04% to 101.085, 10y UST +2.3bp to 4.677%.
In its latest monthly bulletin, the RBI observed that India’s economy remained resilient, despite heightened global uncertainty from fragile geopolitics and supply chain disruptions. Domestic demand remained healthy, supported by stronger rural and firm urban activity, while industrial and services sectors continued to perform well. Headline CPI inflation edged up in June, driven by food and fuel, while core inflation excluding food and fuel was unchanged and the core measure excluding precious metals stayed low. System liquidity improved in early July, supporting robust credit growth, though conditions tightened later in the month. External sector indicators remained steady, with stronger exports and imports in Q1 2026-27, higher FDI in April-May and positive FPI inflows in June and July. Foreign exchange reserves remained comfortable, while the rupee and other EM currencies weakened in July on a stronger USD. SENSEX -0.64% to 76264, USDINR +0.035% to 96.5388, 10y INGB +1.9bp to 6.82%.
The ECB is expected to keep rates on hold at 2.25%. The Governing Council is no longer showing a unified front on the outlook, as more members question the presence of second-round effects. However, Bundesbank President Joachim Nagel has warned that the current tension in the Strait of Hormuz is essentially a return to conditions in March. Vigilance will remain, but if the ECB signals no clear risk of a severe scenario, the risk of further hikes is low.
South Africa’s SARB is expected to hike by 25bp to 7.25%. The market’s base case is that this hike will be the last in the recent cycle, barring material escalation in the Gulf and sharp rises in global energy prices. Inflation figures for June are due the day before the SARB meeting; core CPI is expected to stay below 4%, but sequential price growth looks set to remain high, mandating “insurance” moves. Weakness in manufacturing and industrial production is limiting economic tolerance of further tightening.
U.S. initial jobless claims are forecast to rise to 211k vs. 208k.
U.S. June Chicago Fed National Activity Index is due out; the May reading was -0.1.
U.S. July Kansas City Fed Manufacturing Activity is forecast at 13.0 vs. 11.0.
Canada May retail sales are forecast to rise to 1.0% m/m vs. 0.5% m/m; the ex auto measure is forecast at 1.3% vs. 0.1% m/m.
U.S. Treasury sells $110bn in 4-week bills, $100bn in 8-week bills and $21bn of 10y TIPS.
Mood: iFlow Mood continued to worsen to -0.15, driven by continued strong demand for global fixed income.
FX: G10 currencies were mixed, with USD and SEK seeing strong inflows while GBP continued to record large outflows associated with political uncertainty. CAD also came under selling pressure.
FI: Demand for global sovereign bonds was strong, with China, Sweden, the U.K. and the Eurozone all seeing significant inflows.
Equities: Global investor demand for equities was mixed. Hungary continued to lead outflows on a scored basis and G10 countries faced some selling pressure, with Japan, Canada and Sweden all seeing outflows. The Philippines, Denmark and Thailand all recorded inflows.
“Interest rates act on financial valuations the way gravity acts on matter.” – Warren Buffett
“Interest is often described as the ‘price of money,’ but it is better called the ‘price of time.’” – Edward Chancellor
The French manufacturing business climate improved slightly in July, with the INSEE composite indicator rising one point to 101, just above its long-term average. The rebound was driven mainly by better views on past production and global order books, while foreign orders were stable and inventories fell back below average. Firms reported a further reduction in expected selling price pressures, though the balance remained above its norm. Supply-side constraints worsened, with sourcing difficulties and supply-only bottlenecks rising to their highest levels in almost three years, while demand-only obstacles remained low. The climate improved across most subsectors, led by machinery and equipment, and transport equipment, while other manufacturing was broadly stable. CAC 40 -1.07% to 8347, EURUSD +0.167% to 1.1423, 10y OAT +4.1bp to 4.01%.
Poland’s H1 labor market data showed weaker employment and higher unemployment. Average employment in the enterprise sector fell 1.1% y/y to 6.377 million, with June employment down 0.9% from a year earlier. The sharpest declines were in mining, energy, transport, construction and manufacturing, while water supply and accommodation posted rises. Registered unemployment reached 901.5k at end-June, down 1.6% m/m but up 13.1% y/y, and the unemployment rate was 5.8%. New registrations fell 4.9%, while exits declined by 5.5%, mainly because of the number of workers finding jobs. Job vacancies were 43.1k at end-June, while layoffs affecting 3.1k workers are planned. WIG +0.05% to 145281, EURPLN +0.072% to 4.3306, 10y PGB +8.5bp to 5.785%.
In Japan, used condo prices in Tokyo’s 23 wards saw falls in June for the first time in 26 months, signaling a possible cooling after a prolonged boom. The average price of a 70 sqm unit slipped 0.8% m/m to ¥127.41mn from May, while prices in Tokyo’s six central wards fell faster, down 1.3% m/m to ¥185.12mn. The decline suggests demand for Tokyo real estate is losing momentum as higher interest rates and returning inflation weigh on buyers and investors. The report points to a market adjustment after years of record gains driven by strong domestic and overseas demand. Nikkei +0.46% to 66423, USDJPY -0.209% to 163.36, 10y JGB +2.8bp to 2.79%.
Australia’s June Labour Force Survey showed firmer conditions. Seasonally adjusted employment rose 76,300 m/m (+0.5%) to 14.823 million, with gains in both full-time and part-time work. The employment-to-population ratio increased by 0.3 percentage points to 64.0%, while participation rose 0.3 percentage points to 67.0%. The unemployment rate was unchanged at 4.4% (up 0.1 percentage points m/m in unrounded terms), with the unemployment count up 12,700 to 686,800. Underemployment rose 0.2 percentage points to 6.5%, lifting underutilization to 10.9%. Monthly hours worked increased by 4.9 million to 2,014 million, though the rise here was smaller than for employment. In trend terms, employment and participation edged higher, while unemployment remained at 4.4%. ASX -0.22% to 5751, AUDUSD +0.115% to 0.7001, 10y ACGB +1.6bp to 4.991%.
South Korea’s advance Q2 GDP estimate showed the economy grew 0.6% q/q, 3.7% y/y vs. 1.8% q/q, 3.8% y/y in Q1. On the expenditure side, private consumption rose 0.4% q/q (Q1: 0.3% q/q), government consumption increased by 0.2% q/q (Q1: -0.4%) and gross fixed capital formation rose 0.8% q/q (Q1: 2.9%), within which construction investment fell 0.2% q/q (Q1: 1.4%), facilities investment edged up 0.2% q/q (Q1: 6.6%) and investment in intellectual property products jumped 3.3% q/q (Q1: 0.9%). Exports increased by 1.4% q/q, led by semiconductors, and machinery and equipment, while imports rose 0.8% q/q. On the production side, services expanded by 1.1% q/q (Q1: 0.6%) and manufacturing gained 1.2% q/q (Q1: 3.9%) while agriculture, forestry and fishing dropped 7.1% q/q (Q1: 4.3%) and construction declined by 1.9% q/q (Q1: 2.2%). KOSPI +4.4% to 7097, USDKRW +0.599% to 1469.55, 10y KTB +5.5bp to 4.385%.
South Korean President Lee Jae-myung has signaled a review of tax rules for single-home owners, saying the capital gains tax exemption should not be available an unlimited number of times and could be capped by lifetime use or amount. He also floated a temporary, smaller tax benefit for multiple-home owners who did not manage to sell by the end of the grace period for the heavy capital gains tax, but said they should not receive the same treatment as earlier sellers. Lee further pledged a full review to remove the “marriage penalty” in loans and housing subscriptions. He stressed the need to strengthen property holding taxes, but ruled out an abrupt move to advanced-economy tax levels and said ultra-high-priced homes should face more appropriate taxation.
Singapore’s consumer price data showed inflation steady overall in June, with the MAS core inflation measure rising to 1.6% y/y from 1.4% in May, in line with the broadly subdued price backdrop. Core prices increased by 0.1% m/m after being flat previously. Headline CPI was unchanged m/m and edged up to 1.9% y/y from 1.8% in May. Food inflation firmed up to 2.1% y/y from 1.8%, while transport remained the main upside driver at 7.5% y/y, slightly above May’s 7.4%. Housing and utilities remained soft at 0.3% y/y, and communication remained in deflation at -2.7% y/y. The data suggest modest underlying inflation pressure, with transport and food keeping headline inflation positive while core inflation remains contained. STI -0.67% to 5558, USDSGD +0.078% to 1.2903, 10y SGB +6.2bp to 2.297%.
Taiwanese industrial production rose 22.95% y/y and 1.97% m/m in June (seasonally adjusted: +2.68%). Manufacturing grew 24.34% y/y and 2.06% m/m, driving the gain. On a quarterly basis, industrial output rose 9.89% q/q in Q2 and 16.47% y/y. For January-June, industrial production was up 19.82% y/y, with manufacturing up 21.24%. The surge was led by electronics and computer-related industries, supported by strong AI, high-performance computing, cloud data services and semiconductor investment. Electronics components rose 30.37% y/y, and computers, electronic products and optical items jumped 45.05% y/y. Traditional industries were mixed: machinery and basic metals grew, while chemicals and auto parts contracted on weak demand and inventory adjustments. The ministry said July output is likely to increase further. TAIEX +0.06% to 44851, USDTWD +0.338% to 32.266, 10y TGB +11.6bp to 1.865%.