Market Movers: Supply
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 5 minutes
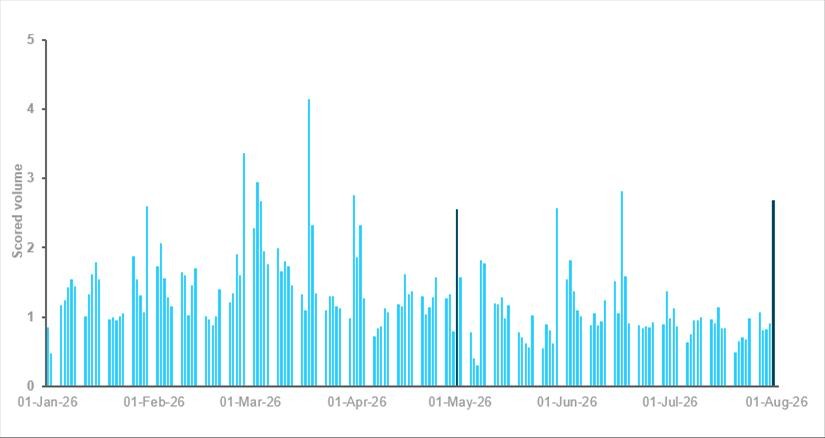
Intervention makes its mark on JPY volumes
Source: BNY
The market is continuing to focus on JPY intervention prospects, and it appears that both U.S. and Japanese authorities stepped aside from market action overnight. Tokyo seems intent on avoiding losing its IMF classification as a “free-floating exchange rate regime,” which would limit the country’s ability to intervene in a fourth trading session. Furthermore, under a free-floating exchange rate regime, only three episodes of currency intervention are allowed in a six-month window, which would permit only one more episode before the end of October. However, the U.S. actions have raised the prospect of greater market volatility, and this is having a clear impact on transaction volumes.
Our data show that intervention days have generated some of the biggest volume sessions YTD. This is likely happening by design. April 30 and July 31 were intervention sessions but also month-ends, during which flows can be amplified. Although the “surprise” element during the first period of intervention generated the strongest price action in USDJPY and JPY crosses, stronger volumes can help reinforce current price action. The most concentrated volume gains still came in the first weeks of the conflict, indicating that sustained event risk remains the biggest driver of sustained volume gains. The challenge, however, is that event risk tends to be positive for JPY and negate intervention efforts.
Dollar supply: U.S. Treasury Secretary Scott Bessent wants the Fed to expand its FIMA Repo Facility, giving Japan greater access to dollars against its Treasury holdings. Tokyo could then sell those dollars to buy yen without liquidating U.S. bonds. The goal is more intervention firepower with less disruption to the Treasury market. Liquidity can sharpen the signal, but lasting success will still require monetary and fiscal fundamentals to cooperate.
Oil supply: Saudi Aramco has said that July’s attacks had no material operational or financial impact. Alternative pipelines, storage and export terminals have preserved business continuity despite the disruption around the Strait of Hormuz. That is an important reassurance: Saudi supply remains intact, even if geopolitical and shipping risks are still elevated.
Metal supply: Copper is surging as tighter availability collides with uncertainty over U.S. tariffs. Shipments to the U.S. have drained inventories elsewhere, while constrained mine output leaves the market vulnerable to further squeezes. Tariffs may redirect flows, but they cannot create more metal.
Water supply: Europe’s drought is turning water scarcity into an industrial and energy problem. Low river levels are disrupting freight, limiting cargo loads and reducing hydroelectric and nuclear output. The result is higher transport costs, tighter power supply and another supply-side headache for European industry.
Bottom line: Markets are now awaiting earnings and today’s JOLTS report, an important test of whether labor demand is cooling enough to support Fed restraint. Results must justify elevated valuations, while job openings and quits will shape the policy debate ahead of the payrolls release. Supply constraints remain visible across currencies, hydrocarbons, metals and water. Central banks cannot print oil, copper or water molecules. Where authorities can create liquidity, as through FX intervention, they will deploy it forcefully while fundamentals permit. Either way, volatility remains the common denominator.
U.S. Treasury Secretary Scott Bessent has called on the Federal Reserve to boost its Foreign and International Monetary Authorities Repo Facility as part of ongoing efforts to support Japan’s efforts to strengthen the yen. The facility, which allows accountholders to monetize their Treasury holdings as repo collateral, would enable Japan to access dollars without selling its Treasury holdings. The comments indicate that the U.S. authorities are well aware of the risks of ongoing intervention by Japan affecting the U.S. Treasury market, as Japan remains the largest foreign official holder of such securities. Nikkei +0.32% to 63958, USDJPY +0.389% to 157.79, 10y JGB +2.5bp to 2.86%.
Saudi Aramco has said the July attacks on its assets had no material operational or financial impact, even though some facilities were targeted and there was some interruption. Chief Executive Officer Amin Nasser declared that the company still has its full 12 million barrels/day of production capacity available and could ramp up within three weeks if requested by the government. He added that Aramco is seeking to expand export flexibility as disruption in the Strait of Hormuz continues, including possible upgrades to the East-West pipeline and greater use of Yanbu. He also said Red Sea threats have not affected export volumes, while the company continues contingency planning around shipments. Brent +1.505% to 85.03, WTI +0.561% to 80.79, Omani crude -1.714% to 78.56, Dubai crude -3.784% to 78.04.
Copper markets were in focus as the metal climbed to a two-month high of almost $14,000/ton in London, with traders watching swelling U.S. inventories ahead of an expected tariff decision by President Trump. More than 200,000 tons arrived at U.S. ports in July, the largest monthly inflow in available shipping data, tightening supply elsewhere and helping push the LME market into a steeper backwardation that signals short-term scarcity. Copper has risen about 12% this year on trade policy speculation and optimism tied to the energy transition and artificial intelligence infrastructure, although some Chinese demand has softened as prices have remained elevated. Aluminum (LME) +1.063% to 3227.59, iron ore (SGX) +0.15% to 93.9, copper (CMX) +1.667% to 664.95.
Hungary and Romania face mounting energy stress as record-low Danube levels force both countries to reduce nuclear output from their only atomic plants. Romania has declared a nationwide state of emergency after low river levels shut part of the Cernavoda plant, leaving naval forces to blast rock from the riverbed to redirect cooling water to the remaining reactor. Hungary is also under pressure, with the Paks plant operating at less than half capacity and authorities warning that a full shutdown could come within days if water levels do not improve. Both countries are increasingly reliant on expensive power imports just as heatwave conditions drive up electricity demand. The crisis highlights how drought is turning from an environmental shock into an energy security problem for the region. Budapest SI +0.75% to 148475, EURHUF -0.228% to 363.25, 10y HGB 0bp to 5.47%.
JOLTS job openings are forecast to decline to 7.454 million from 7.594 million.
U.S. durable goods orders are projected to remain flat at 0.3%, unchanged m/m.
Canadian manufacturing PMI is released; the June print was 53.0.
Mood: iFlow Mood turned slightly positive, driven by global equity inflows, but remained in risk-off territory.
FX: FX flows were generally muted, with the exception of inflows into GBP and sizable outflows from NZD and CNY.
FI: Fixed income flows were mixed in the G10 segment: Danish and Eurozone sovereign bonds continued to show strong inflows, while Norwegian and New Zealand bonds saw outflows.
Equities: Equities started to turn more positive after nearly a week of selling pressure, with inflows into Danish, Colombian and Peruvian equities, while Hungary and Canada saw outflows.
“An hour lost at a bottleneck is an hour lost for the entire system.” – Eliyahu M. Goldratt, The Goal
“The meek shall inherit the earth, but not its mineral rights.” – J. Paul Getty
Italian retail sales edged down 0.1% m/m in both value and volume terms in June, as food sales fell 0.4% by value and 0.5% by volume, while non-food sales rose 0.2% on both measures. In Q2, retail sales increased by 0.6% in value terms and 0.2% in volume terms q/q, supported by gains in non-food goods. On a y/y basis, sales climbed 3.1% by value and 1.9% by volume, with food flat by volume and non-food up 4.0% by value and 3.1% by volume. Online sales remained the strongest channel, surging 26.7% by value. FTSE MIB +1.1% to 53456, EURUSD +0.009% to 1.151, 10y BTP -0.5bp to 3.932%.
Spain's registered unemployment count rose by 19,517 to 2,311,499 in July. This was the lowest July reading since 2007, but still up 0.85% vs. June. On a y/y basis, unemployment fell by 93,107, or 3.87%, signaling continued labor market resilience. Jobless claims rose in services and construction and among those without previous employment, while industry and agriculture were broadly stable. Female unemployment remained below 1.4 million at 1,396,016, and male unemployment was 915,483. Youth unemployment fell to a record-low 159,562. Total contracts reached 1,587,141, with 38.89% permanent. June benefit coverage stood at 80.96%, also a record for that month. IBEX 35 0% to 20012, EURUSD +0.009% to 1.151, 10y Bono -0.3bp to 3.588%.
South Korean inflation eased to a three-month low in July, with the consumer price index rising 2.8% y/y after 3.2% in June, below the expected 3.0%. Prices fell 0.2% m/m, in the first drop in eight months. The softer headline reading reflected lower petroleum prices and fuel support measures, but officials said upward pressures persisted, including risks from Middle East tensions and a one-off boost in August from base effects. Core inflation accelerated to 2.6%, the biggest jump since December 2023, keeping the Bank of Korea cautious ahead of its August 27 meeting and leaving markets still considering another rate hike. KOSPI +1.62% to 6359, USDKRW +0.014% to 1432.15, 10y KTB -0.2bp to 4.26%.