Market Movers: Supply Constraint
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 9 minutes
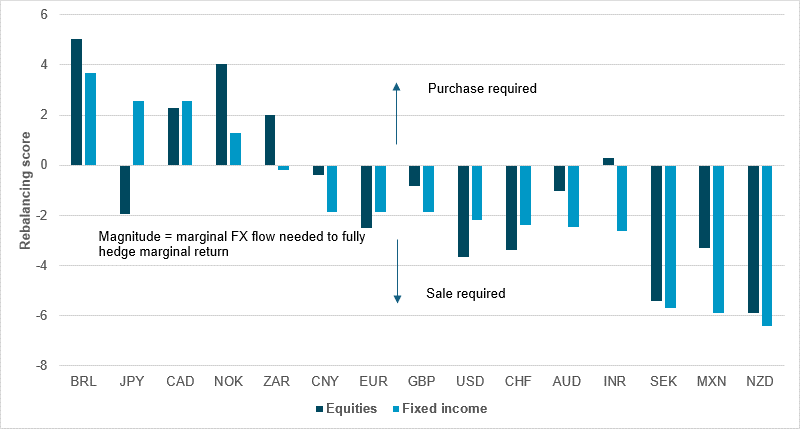
Commodity-linked names benefiting the most from rebalancing
Source: BNY
The main June theme in FX was weakness in commodity-linked currencies. CAD, BRL and NOK all struggled as lower energy prices hurt terms of trade. At the same time, SEK and NZD were the strongest bought, reflecting demand for low-yielders where markets had been pricing in further rate hikes. That support now looks fragile. If these flow patterns reverse, carry should benefit, and that fits the improving carry backdrop we have already flagged.
In equity rebalancing, the clearest buy signals are in BRL, NOK, CAD and ZAR. These markets saw simultaneous weak equity performance and currency weakness, creating strong purchase requirements to rebalance portfolios. BRL and NOK stand out most, driven by the sharp drop in liquefied natural gas prices and the broader hit to commodity exporters. That rebalancing can be achieved through fresh equity buying or by scaling back FX hedges.
By contrast, SEK and NZD now face the opposite problem: FX strength without equity support. As markets shift toward carry, both currencies look exposed, and rebalancing scores reinforce that view.
Bond market strength is generating much bigger FX sell signals than buy signals. NZD, MXN and SEK show the strongest selling pressure, as inflows into FX and fixed income have left positions stretched. SEK and NZD are straightforward sell expressions because carry is low. MXN is more a mean-reversion setup. We flagged ahead of the Banxico meeting that the better risk-reward in Mexico lies in assets with higher hedge ratios, not outright FX. On the buy side, BRL and JPY reflect simultaneous weakness in currency and fixed income. Of the two, BRL is the stronger opportunity: June weakness means a higher risk premium has already been priced in, and carry remains attractive. JPY still screens positively on rebalancing, but those inflows rarely stick because policy credibility remains weak.
Today is another difficult day for markets, as developments in the technology sector prompt investors to ask tougher questions about the economics of the artificial intelligence buildout. While the direct cost of funding AI infrastructure has been a focus for some time, rising prices for memory and storage chips are now beginning to feed through the real economy, making higher prices for consumer electronics and other component-intensive goods more likely. For policymakers, the risk is that just as energy inflation fades, AI-driven hardware costs emerge as a new source of price pressure, leaving financial conditions tighter. That said, tighter financial conditions transmitted through equity markets may be preferable to additional policy rate hikes while growth outside the technology sector remains subdued.
Oil prices continue to fall, shrugging off reports of attacks on shipping over the past 24 hours as markets look beyond near-term disruptions to focus on the future management of the Strait of Hormuz. Iran stated overnight that vessels would require its permission to transit the strait, but also reaffirmed that navigation would be managed under the memorandum of understanding agreed with the U.S. With crude flows now recovered to around 75% of pre-conflict levels, policymakers will be hoping the recent fall in oil prices feeds through to lower retail energy costs faster.
Eurozone inflation expectations continue to ease, with the 12-month forward measure falling to 3.5%. Combined with the sharp decline in oil prices, headline inflation is likely to moderate further. That weakens the case for Governing Council concerns over second-round effects – one of the factors keeping the ECB more hawkish than its developed market peers. Markets have now fully priced out any further rate hikes this year, raising questions over whether July can realistically remain a live meeting if current trends persist.
Germany’s industrial sector continues to face mounting cyclical and policy headwinds, raising broader questions over the region’s growth outlook as the ECB prepares for its annual Sintra symposium. Earlier this week, Germany’s largest defense contractor, Rheinmetall, suffered a record one-day slide after the government scrapped a major naval procurement program. Meanwhile, Volkswagen today announced plans that could eliminate up to 100,000 jobs and close four plants as it accelerates cost cuts in response to intensifying Chinese competition.
Bottom line: The inflation story is improving; the growth story is not. Lower energy prices and easing inflation expectations are giving central banks more room to pause should another supply shock emerge. Technology and Europe’s industrial sector, however, continue to highlight deeper structural challenges that lower inflation alone cannot solve.
Asian equity markets fell sharply after a global tech selloff hit semiconductor stocks, with South Korea leading the declines. The KOSPI dropped as much as 9%, triggering a temporary 20-minute trading halt; Samsung Electronics and SK Hynix were both down more than 10% at one stage. The weakness spread across emerging markets, pushing the MSCI emerging market equity index down as much as 3.9%, its biggest decline in almost three weeks. Investor sentiment deteriorated after Apple raised product prices because of memory chip shortages, raising concerns about technology demand, while reports that OpenAI may delay its initial public offering added to pressure on AI-related stocks. Meanwhile, emerging Asian currencies were broadly stable as expectations of a hawkish Federal Reserve and geopolitical uncertainty continued to support the U.S. dollar. KOSPI -5.81% to 8411, USDKRW -0.344% to 1537.85, 10y KTB -1.8bp to 4.155%
President Lee Jae-myung has announced a plan to build South Korea’s own security tech champions by 2030, aiming for five companies valued at more than ₩1tn and 50 firms with annual sales above ₩100bn. He said the government will back startups in AI, drones, cybersecurity and aerospace, with faster procurement channels, a South Korean version of In-Q-Tel and stronger university-based talent pipelines. Lee argued South Korea’s defense industry is still overly concentrated in large hardware firms and too slow to adopt new technologies. Defense Minister Ahn Gyu-back said the military will expand tech-testing units, improve access to AI-ready military data and speed up the deployment of domestically developed systems, including drones and loitering munitions. The initiative is intended to help South Korean firms compete with Palantir and Helsing.
Traffic has continued to move in both directions through the Strait of Hormuz today despite an attack on a container ship, which has unsettled some shipowners and prompted a review of exit plans. Vessels including fully laden tankers, empty VLCCs and LNG carriers were still using routes along the Omani coast and, in some cases, near Iran. The incident followed the first strike since an interim U.S.-Iran peace deal; however, shipping had been gradually normalizing, with tanker crossings rising to more than 20 a day from about six during much of the war. The U.S. has warned Iran against imposing tolls or fees on the strait, saying such a move would risk chaos and undermine any permanent peace deal. Brent -3.588% to 72.56, WTI -3.574% to 69.35, Omani crude +1.528% to 64.48, Dubai crude +0.194% to 79.672.
The euro area Consumer Expectations Survey for May showed mixed but mainly softer inflation and activity expectations. Median perceived inflation over the past 12 months stayed at 4.0%, while inflation expectations for the next 12 months fell sharply to 3.5% from 4.0% in April. Expectations for inflation three years ahead were unchanged at 2.9%, with five-year-ahead expectations at 2.4%. Consumers also raised their nominal income growth expectations to 1.0%, while expected spending growth eased to 3.8%. Economic growth expectations improved slightly, though unemployment expectations rose to 11.3%. Home price growth expectations edged down, mortgage rate expectations were unchanged and reported credit conditions tightened further. Euro Stoxx 50 -0.66% to 6226, EURUSD +0.299% to 1.1404, BBG AGG Euro Government High Grade EUR -3.6bp to 3.17%.
The ECB has announced a broad review of its banking supervision publications to improve transparency, consistency and usability for banks and the public as part of a wider push to make supervision more efficient, effective and risk-based. The ECB said it has reviewed about 130 guides, reports, letters and methodologies, discontinuing around 40 that were outdated or no longer relevant, while keeping them available for archival purposes. Several others will be revised, with changes aimed at clarifying non-binding supervisory expectations, updating references to reflect new rules and aligning guidance with forthcoming European Banking Authority and legislative developments. The ECB has also updated its publication classification to better distinguish the purpose of different supervisory tools.
Italian consumer and business confidence was mixed in June: consumer sentiment fell fall while business confidence improved. The consumer confidence index slipped to 92.4 points from 93.4 on deteriorations in the personal and current climate, even though the economic and future outlook measures edged higher. In contrast, the composite business confidence gauge climbed to 95.2 points from 94.2, supported by gains across all main sectors. Manufacturing confidence improved modestly and construction more strongly, services edged higher and retail trade posted the strongest increase. Overall, the release shows softer household sentiment but firmer corporate conditions, especially in retail and construction. FTSE MIB -1.07% to 51228, EURUSD +0.299% to 1.1404, 10y BTP -0.3bp to 3.587%.
Sweden’s Economic Tendency Indicator rose to 101.7 points in June from 99.9 in May, maintaining a normal overall sentiment reading. The increase was driven almost entirely by manufacturing, where the confidence indicator jumped to 105.1, its highest level since December 2022, helped by smaller reported inventories and improved views on order books at home and abroad. Construction weakened to 97.3 as hiring plans were revised down. Retail eased but remained the strongest sector at 105.8, services were broadly stable at 101.9 and households improved slightly to 93.6 but still signaled a subdued mood and cautious plans for durable goods purchases. OMX -0.76% to 3157, EURSEK +0.007% to 11.0658, 10y Swedish GB +0.2bp to 2.65%.
In Japan, June headline CPI inflation in the Tokyo area came in at 1.7% y/y (1.4% in May) and 0.3% m/m. The ex-fresh food index was up 1.6% y/y (1.3% in May) and 0.3% m/m, while the ex-fresh food and energy measure accelerated to 1.9% y/y (1.6% in May) and 0.4% m/m. Higher prices were led by food, including eating out, prepared meals, meat, confectionery and seafood, alongside rent, transport and communications. On the downside, other miscellaneous items fell sharply, mainly due to free nursery care, while fuel-related components remained weak, with electricity, city gas and gasoline still down y/y, though some declines narrowed. The release serves as a leading indicator for Japan’s nationwide CPI due later in the month. Nikkei -4.15% to 69361, USDJPY -0.124% to 161.59, 10y JGB -1.2bp to 2.621%.
Mood: Core government bond sentiment has turned decisively, with outflows gaining momentum, while global equities remain under selling pressure. iFlow Mood narrowed slightly to -0.122.
FX: Flows were highly divergent across the G10 and EMEA, while APAC and LatAm saw mixed and generally moderate activity. Within the G10, AUD, NZD and SEK attracted strong inflows, offset by sizable outflows from JPY, NOK and CAD. USD recorded modest inflows.
FI: Demand for Eurozone and Indian government bonds remained resilient, contrasting with substantial selling in Philippine government bonds. Flows across the rest of the fixed income universe were relatively muted.
Equities: Global equities remained broadly under pressure. India, Malaysia, Australia and New Zealand attracted selective buying, while the U.S., South Korea and Indonesia recorded significant outflows.
U.S. May advance goods trade balance is forecast to widen to -$85.0bn vs. -$82.4bn. May advance goods imports are forecast at 2.1% vs. 2.0% m/m, and May advance goods exports at 2.1% vs. 3.8% m/m.
U.S. May retail inventories are forecast to ease to 0.5% m/m vs. 0.7% m/m. Wholesale inventories are forecast to ease to 0.4% m/m vs. 0.6% m/m.
U.S. June final University of Michigan sentiment is forecast to rise to 50.0 vs. 48.9. The current conditions measure is forecast to rise to 49.0 vs. 48.4. University of Michigan expectations are forecast to rise at 49.6 vs. an estimate of 49.3 and 44.1 for May.
U.S. June final University of Michigan 1-year inflation expectations are forecast to be unchanged at 4.6% vs. an estimate of 4.6% and 4.8% in May, while 5-10-year inflation expectations are forecast at 3.3% vs. an estimate of 3.4% and 3.9% in May.
U.S. June Kansas City Fed Services Activity is due; the May reading was +10.
Central bank speakers: the Fed’s Neel Kashkari participates in the Aspen Ideas Panel; ECB Vice President Boris Vujčić joins a panel discussion on climate change at a workshop on “Micro and Macro Productivity Challenges in Times of Structural Shifts”; the ECB’s Isabel Schnabel participates in a panel discussion.
“Design depends largely on constraints.” – Charles Eames
“The more constraints one imposes, the more one frees one’s self.” – Igor Stravinsky