Market Movers: Static
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Bob Savage
Time to Read: 8 minutes
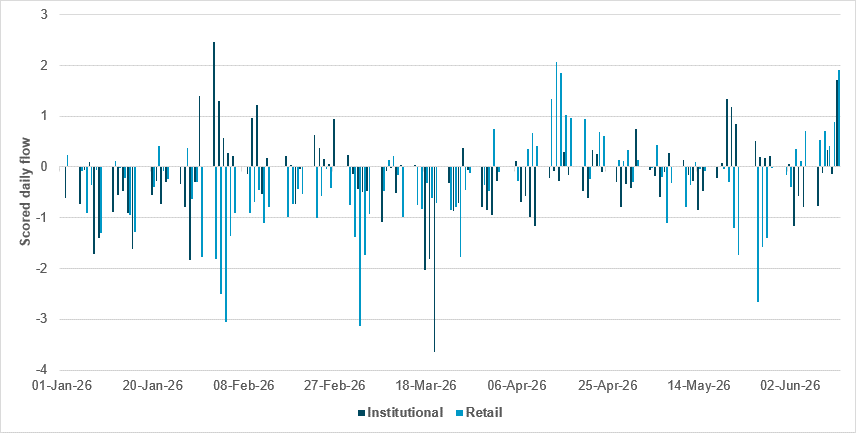
Daily institutional and retail flow, U.S. equities, GICS code 501010 – diversified telecommunications services
Source: BNY
Friday’s SpaceX IPO could mark the beginning of a new round U.S. exceptionalism plays. Coupled with the imminent signing of a 60-day ceasefire agreement between the U.S. and Iran, this means risk appetite is clearly in favor. However, the market will likely remain selective in respect of which sectors will receive fresh allocations.
Our data show that on Friday, the industry group that includes SpaceX (GICS 501010, diversified telecommunication services) saw the second-largest flow sessions YTD for both global institutional and retail investor segments, on a scored basis. On an outright net asset flow basis (which does not incorporate a decay effect from previous flow sessions), this was the largest flow session of the year for the industry classification.
Aside from flows into South Korea and Taiwan, which are associated with drivers of U.S. tech, the concentration of global asset allocation will likely remain strong. Our data indicate that, on a holdings basis, global semiconductor stocks have continued to accelerate but that the broader market is topping out at best. Monday’s price action in Europe indicates some relief from supply chain disruptions, but for now there is limited sign of greater breadth in performance. Even with a near-term peace settlement, supply issues will linger and growth forecasts continue to face downward revisions. The U.S. is an outlier on growth, even if the drivers are concentrated, further contributing to rotation.
Markets were noisy overnight, with central bank decisions and lower oil prices again driving asset prices. The BoJ rate hike left the Nikkei close to flat, JGBs lower and JPY weaker. The quantitative tightening taper will end next year, and the rate guidance lacks urgency. The RBA kept rates on hold as expected, capping bond yields, with AUD slightly weaker. Zimbabwe became the first central bank to cut rates in the wake of the U.S./Iran agreement. Details of the peace deal details are still sketchy, but oil and gas prices fell again. USD reached a 10-day low: commodity-linked FX sagging was led by CAD and AUD, while EM currencies rebounded, led by KRW, HUF and ZAR. Bonds and stocks continue to be bid in EMEA and mixed in U.S. futures, with the focus squarely on SpaceX and AI.
Bottom line: Watching market prices flicker is like listening to static noise on the radio. There is less information than frustration in trading assets. Trend factors remain dominant, with bonds and stocks correlated and any moves higher unlikely to be sustained. The way in which the day ahead turns out for U.S. markets will rest on the extent to which further economic data and new headlines about the “deal” will matter for central bank decisions and a weary public. The barometer of Tuesday turnaround risk remains the bond market, where U.S. 2y yields are still over 4% and 10y rates are holding at 4.44%. Bonds’ ability to track stocks rather than balance them out highlights the risk associated with central bank guidance. Easy global financial conditions make a hawkish policy bias less meaningful.
The BoJ has raised its policy rate by 25bp to 1.00%, although the decision was not unanimous. Asada Toichiro dissented in favor of keeping rates unchanged, arguing that the downside risks to production and employment outweighed the upside risks to inflation. The BoJ’s assessment of the economy was broadly more constructive. It highlighted support from strong global AI-related demand, easing Middle East tensions and a recovery in domestic activity aided by government policy measures. Despite headline inflation slowing to 1.4%, the BoJ maintained that underlying inflation pressures remain firm and warned that inflation could exceed its 2% target. Overall, the statement retained a hawkish tone, emphasizing that financial conditions remain accommodative even after the rate hike and reiterating the bank’s intention to continue raising rates and adjusting the degree of monetary accommodation as warranted. Separately, the BoJ has announced that it will continue to scale back its JGB purchase program by ¥200bn per calendar quarter. This decision was also not unanimous, with Tamura Naoki opposing the plan to continue reducing bond purchases from 2028. Under the latest schedule, monthly JGB purchases will be reduced by ¥200bn per quarter, from ¥2.5tn in Q3 2026 to ¥2.3tn in Q4 2026, ¥2.1tn in Q1 2027 and ¥2.0tn from Q2 2027 onward. The BoJ has retained the flexibility to increase purchases or conduct fixed-rate JGB operations should long-term yields rise sharply, underscoring its commitment to preserving orderly market conditions. Nikkei +0.13% to 69405, USDJPY -0.069% to 160.24, 10y JGB +6.1bp to 2.643%.
The RBA has left its cash rate unchanged at 4.35% in a unanimous decision, with a clear tightening bias and willingness to tighten further if required. The bank cited signs that Australia’s economy is slowing after recent rate increases. Financial conditions are now tighter, and the recent data show weaker momentum alongside a rise in unemployment. The RBA said it would monitor the impact of previous tightening and the oil supply disruption and will do what it considers necessary to bring inflation back to target. ASX +0.06% to 5616, AUDUSD -0.184% to 0.7059, 10y ACGB +1.9bp to 4.826%.
The Central Bank Gold Reserves Survey 2026 shows that central banks remain strongly constructive on gold amid the geopolitical and economic uncertainty. The survey, which was conducted between February and May 2026 and covered 76 respondents, found 89% expect global central bank gold reserves to rise over the next 12 months, while 45% expect their own holdings to increase. Gold is viewed mainly as a crisis hedge, diversifier and inflation hedge, with geopolitical risk also a key driver. Most respondents see the U.S. dollar’s share of reserves shrinking over the next five years, while gold is expected to gain share. Funding for new purchases is expected to come mainly from domestic local-currency buying or sales of existing reserve assets. The BoE remains the preferred vaulting location, though domestic storage and overseas diversification are both rising. Gold -0.106% to 4333.67, silver -0.939% to 70.046, platinum +0.254% to 1785.69.
Fitch Ratings said the U.S. private credit default rate remained at a record-high 6.0% in the 12 months to May. This was unchanged from April, which was itself the highest level since the series began in August 2024. The model-based credit opinion default rate rose to a record 4.9% from 4.8%, while the privately monitored rating default rate eased to 9.5% from 9.7%. Fitch reported 14 default events in May, led by healthcare, industrial and manufacturing, and business services. The increase mainly reflected maturity extensions under stress and the continued use of payment-in-kind structures. Defaults remained concentrated among smaller issuers, with the lowest EBITDA cohorts accounting for most cases, while healthcare and industrials posted the highest sector default rates. S&P Mini -0.03% to 7624, DXY +0.034% to 99.664, 10y UST -2.4bp to 4.449%.
India’s government has announced a further increase in export duties on diesel and aviation turbine fuel, effective June 16, 2026, while leaving the petrol levy unchanged. The revised special additional excise duty on diesel and ATF was raised to ₹14 per liter and ₹12.5 per liter, respectively, from ₹13.5 and ₹9.5. The measure follows the original introduction of export levies on March 27 to secure domestic fuel availability by discouraging exports amid supply disruptions in the Middle East. The ministry said the rates are reviewed every two weeks based on average international prices of crude oil, petrol, diesel and ATF. The increase comes despite softer global crude prices, with Brent down from around $95 two weeks ago to about $83 per barrel. SENSEX +0.53% to 76666, USDINR +0.155% to 94.57, 10y INGB -0.6bp to 6.871%.
U.S. ADP weekly employment change is forecast at 26k vs. 29.0k prior.
U.S. May import price index is expected at 1.0 m/m, 5.7% y/y vs. 1.9% m/m, 4.2% y/y in April. The ex-petroleum measure is forecast at 0.5% vs. 0.7% m/m. The May export price index is expected at 0.6% m/m vs. 3.3% m/m.
U.S. June New York Fed Services Business Activity is expected at -3 points vs. -5.8.
U.S. May housing starts forecast at 1.430 million vs. 1.465 million or -1.9% vs. -2.8% in April, while building permits are forecast to fall to 1.419 million vs. 1.423 million, or -0.6% m/m vs. 4.4% in April.
Central bank speakers: The ECB’s Philip Lane speaks in London. The ECB’s Olaf Sleijpen speaks at the Centre for European Reform.
U.S. Treasury sells $65bn in 6-week bills and $13bn in a 20y bond reopening.
Mood: iFlow Mood has stabilized in risk-off territory at -0.321, reflecting accelerating global equity outflows, partially offset by a moderation in demand for core government bonds.
FX: Flows were mixed across the universe. Notable inflows into USD and ZAR contrasted with outflows from CAD and AUD. Elsewhere, flows were generally modest, with EUR and GBP seeing light outflows, while CNY and JPY attracted mild inflows.
FI: Demand remained strong across LatAm and G10 sovereign bonds, led by the Eurozone, Japan and Colombia. In contrast, government bonds in China, Indonesia, South Korea and Australia faced selling pressure. Notably, demand for Indian government bonds continued to improve following recent policy measures aimed at attracting foreign inflows.
Equities: Selling pressure was widespread across the iFlow universe, with the largest outflows concentrated in South Africa, South Korea, Taiwan, the U.K. and Chile. Selling in the U.S., Europe and Japan was comparatively modest. Select buying interest emerged in Australian, Danish and Norwegian equities.
“Fear is static that prevents me from hearing myself.” – Samuel Butler
“The world is full of noise. And finding quiet isn’t about pushing everything out. It’s about pulling yourself in.” – Victoria Schwab
Canadian home sales rose 5.5% m/m in May – the first meaningful pickup in headline demand this year after a slower spring start. The Canadian Real Estate Association (CREA) said the increase was broad-based but led disproportionately by Ontario. New listings fell 1.0% m/m, pushing the national sales-to-new listings ratio up to 49.2% from 46.2% in April, indicating a firmer market balance. Prices were broadly stable: the MLS Home Price Index edged down 0.1% m/m and was 4.1% lower y/y, while the national average home price increased by 1.5% y/y. The CREA said expectations between buyers and sellers are aligning, with tighter sale-to-list ratios and shorter days on market pointing to improving conditions. TSX +0.97% to 35276, USDCAD -0.286% to 1.401, 10y CGB +1.2bp to 3.413%.
Germany’s ZEW Indicator of Economic Sentiment improved sharply in June as expectations of an end to the Iran conflict boosted the outlook. The indicator jumped to +10.5 points from -10.2 in May, moving back into positive territory. The current assessment of Germany’s economic situation still deteriorated slightly, however, to -81.0 points from -77.8. The ZEW said lower energy prices and inflation could support energy-intensive industries, private households and domestic demand. Sector sentiment improved most strongly in autos, chemicals and pharmaceuticals, and mechanical engineering, while construction weakened further, likely reflecting the ECB’s June 11 rate hike. Eurozone sentiment also strengthened, rising to +9.5 points from -9.1, though the current situation remained deeply negative at -43.4. DAX +0.2% to 24943, EURUSD -0.138% to 1.1595, 10y Bund -1.2bp to 2.942%.
Q1 euro area labor costs rose 3.2% y/y (3.4% for wages & salaries; 2.9% for non-wage costs), while EU labor costs were up 3.6% y/y (3.7% wages & salaries; 3.2% non-wage costs). By activity, euro area labor costs rose 3.3% in the (mainly) non-business economy, 3.2% in business, with construction the strongest at 4.1% and services at 3.1%. In the EU, labor costs rose 3.7% in the (mainly) non-business economy and 3.5% in business, led by construction at 4.2% and services at 3.4%. Among member states, Hungary recorded the fastest rise in hourly wage costs, while Malta and France saw the smallest increases. Euro Stoxx 50 +0.69% to 6273, EURUSD -0.087% to 1.1601, BBG AGG Euro Government High Grade EUR 0bp to 3.223%.
Spain’s Quarterly Labor Cost Survey for Q1 showed labor costs rising 4.9% y/y to €3,278.01 per worker, per month, matching wage costs, while other costs increased by 4.8%. Mandatory social security contributions, the largest constituent of other costs, climbed 4.5%. On a calendar-adjusted, seasonally adjusted basis, labor cost per worker rose 4.5% y/y and 1.4% q/q. Hourly labor costs also moved higher, with the cost per effective hour up 5.4% y/y and per paid hour up 4.8% y/y. Job vacancies totaled 159,785, up 6,900 from a year earlier, with services accounting for 86.6% of the total. Cost growth was strongest in Cantabria, País Vasco and Cataluña, while vacancies were highest in Cataluña, Madrid and Andalucía. IBEX 35 +0.03% to 19056, EURUSD -0.138% to 1.1595, 10y Bono -1.8bp to 3.358%.
Italian consumer prices rose 0.4% m/m and 3.2% y/y in May, up from 2.7% y/y in April, in line with the preliminary estimate. The acceleration was driven mainly by higher prices for non-regulated energy (12.5% y/y vs. 9.6%), regulated energy (5.6% vs. 5.3%), transport services (1.7% vs. 0.6%) and recreation, culture and personal care services (3.0% vs. 2.6%). Core inflation excluding energy and fresh food edged up to 1.7% y/y from 1.6%, while excluding only energy it rose to 2.1% from 1.9%. Goods inflation increased to 3.4% and services to 2.8%. Headline consumer inflation and core measures firmed up modestly overall. FTSE MIB +0.83% to 52268, EURUSD -0.138% to 1.1595, 10y BTP -1.9bp to 3.649%.
Türkiye’s trade sales volume increased by 0.1% y/y in April (no prior-year comparison available) but fell 2.7% m/m. The retail trade sales volume rose 11.4% y/y and declined by 1.7% m/m. By contrast, wholesale and retail trade and repair of motor vehicles and motorcycles fell 7.6% y/y but edged up 0.6% m/m, while the wholesale trade sales volume decreased by 3.3% y/y and 3.7% m/m. The release indicates a mixed picture, with y/y strength in retail activity offset by weakness in wholesale trade and motor vehicle-related sales and softer m/m momentum across the sector. BI 100 +0.4% to 14504, USDTRY -0.049% to 46.3002, 10y TGB +4bp to 33.23%.
Türkiye’s Residential Property Price Index (RPPI) rose 1.7% m/m in May. Y/y, it was up 24.5% in nominal terms but down 6.1% in real terms. In major cities, the RPPI rose 2.1% m/m in Istanbul, 1.5% m/m in Ankara and fell 0.1% m/m in Izmir; y/y gains were 25.4%, 27.3% and 22.8%, respectively. The New Tenant Rent Index (NTRI) rose 1.9% m/m, increasing by 30.4% y/y in nominal terms but falling 1.7% y/y in real terms.
New Zealand’s Selected Price Indexes (SPI) for May showed monthly inflation pressures remaining mixed, with the SPI up 1.0% m/m and 3.2% y/y. Food prices rose 1.0% m/m (3.2% y/y), led by fruit and vegetables (+2.5% m/m), meat, poultry and fish (+0.9% m/m) and grocery food (+1.0% m/m), while non-alcoholic beverages eased (-0.2% m/m). In transport, prices fell sharply, driven by petrol (-3.8% m/m) and diesel (-11.4% m/m), alongside lower domestic and international air transport costs (-11.4% m/m and -5.5% m/m). Housing-related prices were mixed, with electricity rising (+1.4% m/m, 12.1% y/y) and rental measures edging lower. Overall, the data suggest goods price inflation remained supported by food and utilities, while transport provided a significant offset. NZX 50 +0.49% to 13426, NZDUSD -0.411% to 0.5819, 10y NZGB +3.6bp to 4.449%.
China’s economy remained broadly resilient in May despite ongoing property sector weakness and external headwinds. Industrial production accelerated, with value-added industrial output rising 4.5% y/y (vs. 4.1% in April), supported by strong gains in equipment manufacturing (+9.5%) and high-tech manufacturing (+15.1%). Production of emerging technology products remained robust, including 3D printers (+54.4%), lithium-ion batteries (+40.0%) and industrial robots (+27.9%). The services sector also expanded steadily, with the Index of Services Production rising 4.4% y/y, led by information technology (+11.3%), leasing and business services (+10.9%) and financial services (+7.0%). CSI 300 -0.15% to 4884, USDCNY -0.009% to 6.7582, 10y CGB -1bp to 1.733%.
Chinese consumption remains uneven. While total retail sales of goods and services rose 2.8% y/y in January-May and service consumption increased by 5.4%, May retail sales of consumer goods fell 0.6% y/y, the first negative reading since December 2022, reflecting softer goods demand. Online retail sales continued to outperform, rising 5.9% y/y in the first five months of the year, while spending on beverages, apparel and cosmetics remained positive. The biggest drag came from auto sales at -16.1% y/y, -11.8% YTD y/y.
Chinese investment in fixed assets investment remained the main drag on growth in January-May. Investment fell 4.1% y/y over this period, pulled down by a 16.2% decline in real estate investment. Property sales also remained weak, with floor space sold down 10.8% and sales value down 13.5%. However, infrastructure investment continued to grow (+0.6%), while investment in intellectual property products (+9.3%) and high-tech industries (+4.5%) highlighted ongoing policy support for innovation-driven development. Overall, the data suggest China’s growth is increasingly being supported by advanced manufacturing, technology and services, while the property downturn continues to weigh on domestic demand and investment.
China’s property sector remained weak in January-May. Real estate investment fell 16.2% y/y, while residential investment declined by 15.6%. Construction activity continued to contract, with floor space under construction down 12.3%, new housing starts falling 22.6% and completions dropping 23.4%. Housing demand remained subdued, with new commercial property sales area and sales value declining by 10.8% and 13.5%, respectively, while residential sales area and value weakened further, down 12.1% and 14.1%, respectively. Developer financing conditions also deteriorated, as total funding fell 19.0%, led by sharp reductions in domestic loans and mortgage lending. Overall, the property sector remained a significant drag on growth and investment.
Chinese housing data for May revealed a mixed and uneven stabilization in the property market. Tier-1 cities continued to outperform, with new home prices rising 0.2% m/m (vs. 0.1% in April), in a fourth consecutive m/m increase. In contrast, new home prices fell 0.1% m/m in Tier-2 cities and 0.4% m/m in Tier-3 cities. Existing home prices showed a similar pattern, with Tier-1 cities posting a 0.4% m/m gain, the third straight increase, while prices Tier-2 and Tier-3 cities fell 0.2% m/m and 0.4% m/m, respectively. On a y/y basis, declines in new home prices continued to narrow in Tier-1 (-1.7%) and Tier-2 (-3.2%) cities, while Tier-3 cities continued to underperform at -4.2%. Existing home prices also showed improving trends, with y/y declines moderating to -5.8% in Tier-1 cities and -5.7% in Tier-2 cities. The data suggest emerging green shoots in Tier-1 cities, but a broader and more durable recovery will require further stabilization across Tier-2 and Tier-3 markets.
South Korea’s export/import price and trade indexes for May showed further strength in both external prices and trade values. The export price index rose 0.3% m/m and 46.9% y/y (after 7.5% m/m and 41.3% y/y in April), while the import price index fell 0.3% m/m but still climbed 24.8% y/y (after -2.1% m/m and 20.5% y/y). In USD terms, the export volume increased by 14.7% y/y and the export value by 56.8% y/y, while the import volume rose by 5.2% y/y and the import value by 21.3% y/y. The net barter terms of trade index improved by 18.7% y/y, indicating that exports continued to outperform imports on price and volume. Manufacturing drove most of the export gain, with sharp increases in computers, electronic and optical equipment. KOSPI +2.11% to 8727, USDKRW +0.372% to 1509.05, 10y KTB -7.5bp to 4.12%.
South Korea’s monetary and liquidity aggregates continued to expand in April. Narrow money (M1, seasonally adjusted, period-average) rose 0.4% m/m to ₩1.372qn (0.1% m/m in March), while broad money (M2) increased by 0.6% m/m to ₩4.154qn (0.4% m/m in March). Liquidity of financial institutions (Lf) climbed 0.5% m/m to ₩6.219qn (0.4% m/m in March). Period-end liquidity (L) grew 1.8% m/m to ₩7.963qn, bouncing back from -0.5% m/m in March. On a y/y basis, M1 rose by 8.3%, M2 by 5.7%, Lf by 7.3% and L by 8.1%, indicating firmer money growth and stronger liquidity conditions across the financial system.
Hong Kong’s labor market was broadly stable in March-May. The seasonally adjusted unemployment rate stayed at 3.7% (February-April 2026: 3.7%), while the underemployment rate remained at 1.5% (1.5%). Total employment edged down to 3.639 million from 3.648 million, and the labor force slipped to 3.780 million from 3.787 million. The unemployment count rose to 141,100 from 139,200, while the number of underemployed people fell to 56,800 from 58,100. By sector, unemployment improved mainly in cleaning and similar activities, but worsened in social work activities and accommodation services. The government said ongoing economic expansion should continue to support the labor market, though external uncertainties remain a risk. Hang Seng -1.4% to 24494, USDHKD +0.016% to 7.8332, 10y HKGB -1.2bp to 1.417%.