Market Movers: Standstill
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 6 minutes
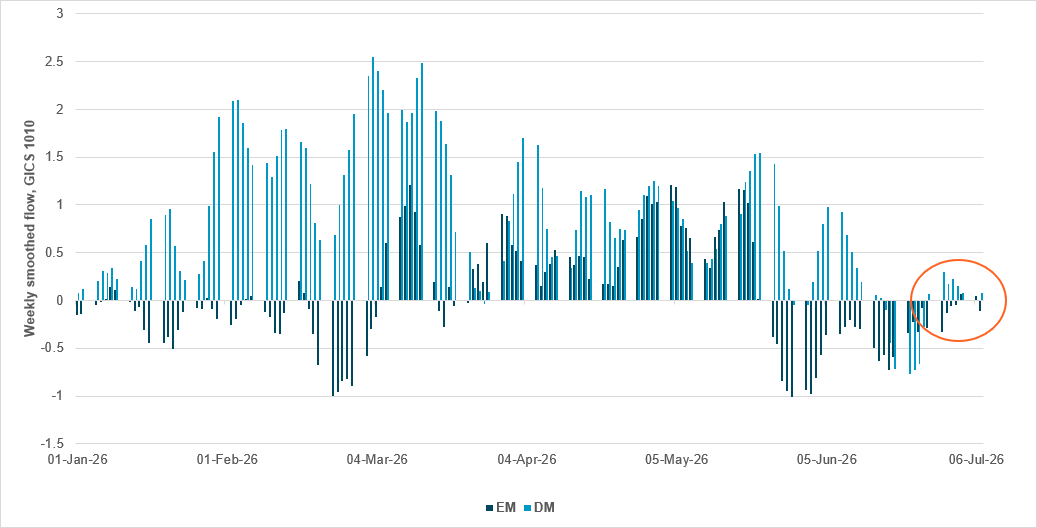
Flows into energy equities stabilizing after a poor run in June
Source: BNY
Energy prices are back in focus this week due to perilous state of the ceasefire. News that traffic through the Strait of Hormuz is at a near-standstill may reverse some of the recent easing in supply pressures. However, the market’s base case remains unchanged, i.e., that there will be no resumption of full-scale hostilities. Nevertheless, the new equilibrium is uneasy, and asset allocation needs to reflect additional risk premiums.
iFlow figures reflect this shift. Based on flows into EM and DM energy industry group equities (GICS level 2), we note that expectations of higher energy prices (and earnings lift for relevant companies) were strong through to early May. The ceasefire led to some unwinding and/or profit-taking through June, but this specific period was brief. The past few sessions have seen flows neutralize or move into light purchases.
Valuation and holdings attractions are emerging: energy is not even in the five best-held sectors globally at present, with holdings having fallen by over 20 percentage points as a share of the rolling 12-month average, close to levels in mid-January this year. Increased OPEC supply and weak Chinese demand are structural factors which will limit long-term gains in energy prices, but pricing in “no supply risk” is also excessive. We expect a period of near-term consolidation for the relevant sector and industry groups, pending clarity on the status of the ceasefire.
President Trump’s talk of another “deal” with Iran after a second day of strikes offers some relief, but only a little. We concur with the view that geopolitical tail risks are well-covered, but that alone is unlikely to support a market that is grappling with stretched valuations and fading momentum ahead of earnings season. Meanwhile, the Fed minutes did little to dent hawkish rate expectations, and the most reliable route to lower inflation is weaker demand – a path that offers little comfort for equities.
Stagflation risks remain in prospect. The IMF has downgraded its global growth forecasts, while both the BoJ and New York Fed have warned that higher energy prices and tariffs will continue to feed through to inflation. China, meanwhile, continues to send mixed signals. Its factory gate inflation has climbed to around 4% y/y, but CPI has slipped back to 1%, reinforcing the view that domestic demand remains subdued. That weakness is weighing on global growth and capping commodity prices, even as rising producer prices point to firmer export costs. The net effect is a more benign global inflation backdrop, but the search for a growth engine beyond technology continues.
Attention now shifts back to the U.S. economy, with weekly jobless claims and existing home sales due today. The economy is continuing to outperform, but the narrative is shifting from acceleration to consolidation – a backdrop that favors rotation over liquidation. For all the inflation vigilance, the Fed and its peers recognize that markets remain highly sensitive to supply shocks. This week’s energy volatility has already tightened financial conditions, reducing the need to reinforce the case for further rate hikes. Policymakers have sought to preserve the expansion, but it is now up to incoming data and earnings to demonstrate that growth is slowing rather than stalling.
U.S. forces have struck Iran for a second consecutive day after President Trump declared the ceasefire with Tehran “over” and signaled more military action. The strikes were aimed at degrading Iran’s ability to threaten shipping in the Strait of Hormuz, following Iranian attacks on commercial vessels. Trump said any further action would end “very quickly,” but also warned it could escalate sharply if Iran attacks again, and raised the prospect of reimposing a naval blockade. He described Iranian leaders in inflammatory terms and said talks could continue, though he was skeptical they would produce results. The escalation drove oil prices higher and prompted the International Maritime Organization to urge shipowners to avoid the strait while safety cannot be assured. The U.S. and Iran each accused the other of violating the tentative peace deal. S&P Mini +0.31% to 7552, DXY -0.087% to 100.904, 10y UST -1.7bp to 4.563%.
The New York Fed said in its July 8 Liberty Street Economics post that more tariff passthrough still lies ahead for many U.S. firms. Drawing on regional business surveys, the institution reported that nearly half of firms that pay tariffs directly are still planning further price increases, with some expecting to raise prices six months or more from now. It said roughly 47% of service firms and 44% of manufacturers that pay tariffs expect additional tariff-related price hikes. It also noted that gradual pricing, fixed contracts and policy uncertainty are extending the adjustment process, suggesting tariff-driven inflationary pressure may persist longer than many policymakers expected.
The International Monetary Fund has inched its 2026 global growth forecast down again to a sluggish 3.0%. Growth is projected to rebound to 3.4% in 2027, but that is still below the average of 3.5% seen in 2024 and 2025. In April, it was forecasting 3.1%. The slowdown reflects war-related disruptions in the Middle East, partly offset by stronger demand from the AI-driven technology cycle. The impact is uneven: energy exporters outside the conflict zone are gaining from better terms of trade, while tech-linked economies are seeing stronger activity even if they import energy. By contrast, many low-income, energy-importing countries face weaker growth. Global headline inflation is seen rising from 4.1% in 2025 to 4.7% in 2026 before easing to 3.9% in 2027, suggesting the disinflation trend has stalled. Risks remain tilted to the downside, with renewed conflict, trade fragmentation and a technology correction the key threats. MSCI World -0.64% to 1114, DXY -0.087% to 100.904, BBG Global Aggregate flat at 3.919%.
Bank Negara Malaysia kept the overnight policy rate at 2.75% at today’s Monetary Policy Committee meeting, saying the stance remains appropriate for price stability and sustainable growth. It noted that global growth has been broadly resilient, helped by strong tech activity and better supply conditions, while risks persist from the Middle East conflict, tighter financial conditions and market valuation concerns. For Malaysia, recent indicators suggest resilient Q2 growth, supported by domestic demand, stronger exports, investment projects, improved electrical and electronics demand, tourism and labor market gains. Headline and core inflation averaged 1.7% and 2.1% in the first five months, and inflation is expected to remain contained in 2026 despite higher commodity prices. KLCI -0.16% to 1681, USDMYR -0.04% to 4.0757, 10y MGB +0.6bp to 3.626%.
Taiwan’s central bank has said it is closely monitoring rising financial leverage and bank funds flowing into equities amid a booming stock market, while warning banks to manage related credit expansion risks. In a report to lawmakers, it noted that strong AI-driven optimism has pushed Taiwanese stocks sharply higher and lifted trading turnover, encouraging households to borrow more through banks and brokers. The bank also said it will keep watching housing market pressure, where affordability remains stretched, and foreign capital flows, which have increased exchange-rate management challenges. It reiterated that it would preserve foreign exchange market order under a managed float and will act as needed to safeguard price, housing, equity and FX stability. TAIEX -0.83% to 45355, USDTWD +0.462% to 32.192, 10y TGB -0.1bp to 1.7%.
U.S. initial jobless claims are forecast at 218k vs. 215k.
U.S. June existing home sales are forecast to rise to 4.2 million vs. 4.17 million.
Central bank speakers: The Fed’s John Williams and Lorie Logan participate in a moderated discussion at the Future of Market Liquidity and Functioning Workshop; BoE Deputy Governor Sarah Breeden speaks on a panel at the New York Fed and Chicago Booth School of Business Future of Market Liquidity and Functioning Workshop.
U.S. Treasury sells $100bn in 4-week bills, $95bn in 8-week bills and $22bn in a 30y bond reopening.
Mood: iFlow Mood edged lower to -0.077, despite a resurgence in core sovereign bond demand after two weeks of selling. Global equity outflows eased to their lightest since mid-May.
FX: USD and JPY buying remained dominant against CAD, EUR and GBP. Elsewhere, flows turned modestly positive across LatAm, EMEA and most APAC FX, with KRW and SGD the main laggards.
Fixed income: Demand returned to G10 government bonds, led by U.K. gilts and Eurozone sovereigns. EMEA and APAC flows were mixed, while Brazilian government bonds saw the heaviest selling.
Equities: Regional flows were mixed. DM APAC attracted the strongest inflows, while DM Americas recorded the largest outflows. Selling was concentrated in U.S. and U.K. equities, offset by buying in Japan and India.
“Policy needs to walk, not run, to stand still.” – Mark Carney
“The long run is a misleading guide to current affairs.” – John Maynard Keynes
The U.K. RICS Housing Market Survey for June pointed to a still-weak housing backdrop in England and Wales. The headline price balance improved only marginally to -33 points in June from -34 in May, remaining deeply negative. Price expectations also remained subdued at -32 (from -44), while sales expectations rose to -16 from -23. New buyer inquiries were slightly less negative at -29 from -34, but agreed sales were again soft at -32 from -35. New instructions weakened to -23 from -10, suggesting limited fresh supply. Surveyor activity was broadly steady: stocks of homes on books edged down to 47.0 from 47.2, while the number of houses sold was little changed at 15.6 from 15.5. The sales-to-stock ratio improved slightly to 33.1% from 32.8%. FTSE 100 -0.53% to 10433, GBPUSD +0.239% to 1.3421, 10y gilt -5.5bp to 4.919%.
Czech industrial production fell 0.4% m/m but rose 2.0% y/y in June. The y/y increase was led mainly by manufacture of computer, electronic and optical products, supported by a recovery in that industry and a lower comparison base, while motor vehicles, fabricated metal products and chemicals also contributed. Output declined in other transport equipment, partly due to a high base last year, and mining and quarrying continued to fall. New industrial orders increased by 4.0% y/y, with foreign orders up 5.2% and domestic orders up 1.7%, although orders were down 1.2% m/m. Employment in industry decreased by 1.1% y/y. Prague SE +0.33% to 2601, EURCZK -0.062% to 24.246, 10y CZGB -0.5bp to 4.694%.
Chinese CPI rose 1.0% y/y in June, unchanged from the average for January-June, and dropped 0.3% m/m. Food prices were the main drag, down 1.6% y/y and 0.4% m/m, while non-food prices rose 1.5% y/y and fell 0.3% m/m. Within the food category, pork fell sharply, alongside lower prices for meat, dairy and fruit; eggs were a notable offset, rising strongly. Transportation and communication prices increased by 4.1% y/y but dropped 1.3% m/m, reflecting weaker transport-related costs and energy. Medical care also rose, while housing was slightly weaker y/y. Core CPI excluding food and energy rose 1.0% y/y and fell 0.1% m/m. Overall, the report points to subdued consumer inflation, with food prices still soft and transport costs easing. CSI 300 +2.54% to 4876, USDCNY -0.171% to 6.7944, 10y CGB 0bp to 1.732%.
Chinese producer prices rose 4.1% y/y in June but fell 0.3% m/m in the first monthly decline since July 2025. Producer purchase prices increased by 6.4% y/y and fell 0.2% m/m. Across H1, ex-factory prices were up 1.5% and purchase prices up 2.4% y/y. The y/y rise in ex-factory prices was driven by higher prices for means of production, up 5.5%, led by mining, raw materials and processing industries, while consumer goods prices fell 0.9%. Within consumer goods, food dropped 2.1% and clothing and daily necessities fell 1.0%, while durable consumer goods edged up 0.1%. On a m/m basis, production materials and consumer goods both declined by 0.3%, with food down 0.8%. Input prices were lifted by non-ferrous metals, fuel and power, and chemicals, while construction materials and agricultural products fell.
New Zealand’s June BNZ-BusinessNZ Performance of Manufacturing Index rose sharply to 59.7 points from 51.3 in May, well above the long-term average of 52.5 and its strongest reading since July 2021. The improvement signals a broad-based recovery in factory activity, with all sub-indices in expansion. New orders were the standout item at 64.1, pointing to healthy work ahead, while production climbed to 59.4 and deliveries to 57.3. Stocks of finished products reached 56.9 and employment 55.8, suggesting firmer hiring conditions. BusinessNZ said positive comments outweighed negative ones for the first time in recent months, helped by stronger sales, fuller order books and improved confidence, although the Middle East conflict and high fuel prices remained headwinds. NZX 50 +0.88% to 13786, NZDUSD +0.597% to 0.5734, 10y NZGB +7.4bp to 4.586%.
Taiwanese trade figures for June, measured in USD, showed strong external demand, with exports rising 40.3% y/y to $74.83bn and imports climbing 51.8% to $62.63bn, leaving a trade surplus of $12.2bn. Export growth was led by information, communication and audio-video products, which surged 72.3%, and electronic parts, up 32.8%, while machinery and mineral products also expanded. On the import side, demand for information, communication and audio-video products jumped 140.4%, with sizable gains in electronic parts, machinery, mineral products and petroleum. Shipments to the U.S., ASEAN, Europe and South Korea were especially robust, highlighting broad-based momentum in Taiwan’s trade performance. TAIEX -0.83% to 45355, USDTWD +0.462% to 32.192, 10y TGB -0.1bp to 1.7%.