Market Movers: Shifting Bias
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Bob Savage
Time to Read: 8 minutes
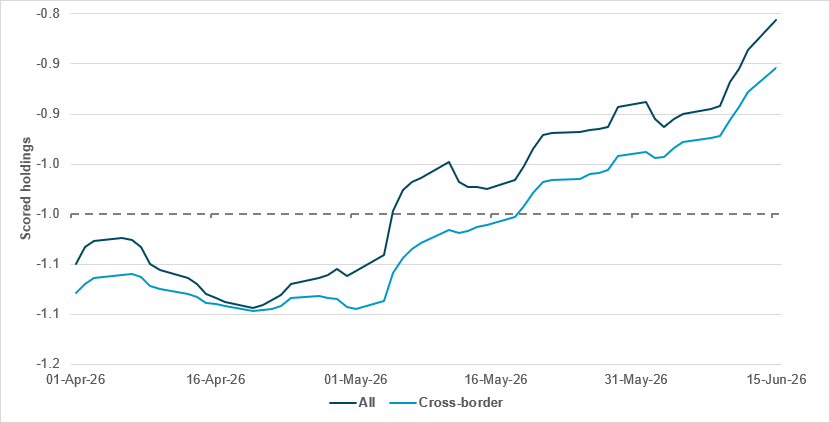
Cross-border dollar hedges fall to 15% below rolling one-year average on “U.S. exceptionalism” theme
Source: BNY
The dollar has been enjoying its best run this quarter ahead of today’s FOMC decision. Although expectations are for a hold and the peace deal may soften near-term inflation expectations, Fed expectations have fundamentally shifted since the last meeting. The acceleration in flows indicates that investors do not want to be caught on the wrong side of a hawkish shift, even if it is only a tail risk. There is enough of a growth and asset allocation narrative in favor of a return to the “U.S. exceptionalism” theme.
The improved flow in the U.S. is having a material impact on holdings, led by cross-border positions. Holdings were still at a rolling 12-month average of -1.00 barely a month ago, but the fundamental shift in U.S. rate expectations has driven significant unwinding of hedges. This cannot be due to asset unwinding, as U.S. markets have been performing well. As of this week, cross-border holdings are now running at 0.85x the rolling 12-month average in underheld territory, indicting a 15% drop in hedges in absolute terms and a shift of over 25 percentage points since the low in May. Consequently, the market has clearly shifted toward a positive/overweight dollar holdings bias.
The wait for the new Fed chair’s first meeting leaves markets wary but not worried. There is a clear risk of a shift in bias from easing to tightening. Guidance is unlikely to be as important to the Warsh-era Fed as it was under Jerome Powell. Policy divergence outside the U.S. hasn’t shifted FX markets, as USD remains bid while stocks and bonds are holding onto their gains from the last four days of oil price relief. AI themes and credit are back as key drivers of risk, in place of inflation and energy shocks. Overnight, U.K. CPI was better than feared, but South African inflation came in higher than expected, highlighting the ways in which different nations have handled the war. How policymakers handle peace will be the new question.
Deal details: The N12 and WSJ have reported the full list of 12 clauses in the U.S./Iran memorandum of understanding. The pushback in the U.S. against some of the clauses – specifically oil sanctions relief and a potential $300bn investment fund – has split some of President Trump’s key supporters. Nevertheless, the deal is holding, as the has U.S. allowed an Iranian supertanker loaded with oil to cross the blockade with its location tracking operational. Further ways to increase oil shipping in the strait are also being considered.
Oil: An 8.3mb (million barrel) drop in U.S. weekly API crude oil inventories has been reported, while gasoline inventories rose by 2.5mb (though they remain -6% below average) and distillates dropped by 0.5mb (-13% below average). The U.S. strategic petroleum reserve fell 8.9mb on the week to 340.3mb – the lowest level since 1983. U.S. oil inventories have shrunk by 52mb in nine weeks but are down only 1.4mb YTD. The overnight noise from Iran/Israel and doubts about the deal left oil slightly higher, with the focus on the curve: front-month prices are now just $4 above December 2026 prices, down from $25 during war.
Two-way APAC risks: The PBoC has established an offshore central bank repo facility to help RMB liquidity, pushing for more international use, adding to the efficiency of interest rate transmission, creating a new set of tools for macroprudential policy and warning that credit growth won’t maintain its previous pace. The hawkish Riksbank stance and the BoJ hike and push for rate normalization stands in contrast to China, where regulators and government are pushing for debt resolution, more walling-off of risks from real estate and local government issues to support the SME economy. Chinese equities rallied, led by semiconductors, while Hong Kong saw selling, led by Chinese financial stocks.
Bottom line: New leaders are always tested, and Kevin Warsh’s Fed leadership will be no exception. Markets’ ability to look through energy and tariffs has been significant, but much of this remains in the hands of central bankers. Policy and politics are likely to dominate today, even as credit concerns about higher rates and the K-shaped recovery in the U.S. economy play out as energy prices try to redefine normal. The barometer of choice for risk today is clearly USD, which has benefited from U.S. asset outperformance and interest rate spreads. Whether or not this holds will be a key question.
Iran stands to receive substantial economic relief under a proposed interim agreement with the U.S., including the immediate resumption of oil and petrochemical exports, the lifting of the U.S. naval blockade of Iranian ports and access to a $300bn economic development program backed by the U.S. and regional partners. The deal would also support the restoration of normal shipping through the Strait of Hormuz within 30 days, providing a major boost to trade and government revenues. In exchange, Iran would reaffirm its commitment not to pursue nuclear weapons, ease disruptions to maritime traffic and enter a 60-day negotiating period aimed at securing a broader agreement on its nuclear program and regional security issues. The memorandum is reportedly close to being signed, although some technical details remain under discussion. MSCI World -0.26% to 1128, DXY +0.022% to 99.561, BBG Global Aggregate 0bp to 3.79%.
Sweden’s Riksbank left the policy rate unchanged at 1.75% at its June meeting, saying that low inflation and weaker-than-normal activity were being offset by rising inflationary pressures from supply disruptions linked to the war in the Middle East. The central bank judged that holding rates steady was a well-balanced position for now, but it lifted its policy rate path and said the chance of a hike later this year has increased since March. It flagged continued uncertainty around oil prices, import costs and pricing behavior, while noting that GDP growth should improve and economic activity strengthen later this year. Forecasts show CPIF inflation for 2026 at 1.1% and GDP growth at 2.2%. OMX +0.14% to 3146, EURSEK +0.056% to 10.8893, 10y Swedish GB -1.2bp to 2.795%.
Japan is moving toward a temporary cut in the consumption tax on food to 1% from the current 8%. The reduction is expected to last for two years from April 2027. The proposal, backed by senior members of the ruling Liberal Democratic Party, would be combined with targeted cash support for low and middle-income households and serve as a transition toward a refundable tax credit system. If implemented, it would mark the first effective reduction in Japan’s consumption tax since its introduction in 1989. The plan reflects the political pressure on Prime Minister Sanae Takaichi to address rising living costs, but it also raises concerns over fiscal sustainability. Estimates suggest the measure could reduce government revenue by around ¥4.4tn while delivering only a modest boost to economic growth, adding to investor concerns about Japan’s already-strained public finances. Nikkei +0.72% to 69902, USDJPY +0.025% to 160.25, 10y JGB -4bp to 2.603%.
Former U.K. cabinet minister Wes Streeting has stepped up the pressure on Prime Minister Sir Keir Starmer, saying he is prepared to trigger a Labour leadership contest if Starmer refuses to step down following Thursday’s Makerfield byelection. Streeting has argued that a victory for Manchester Mayor Andy Burnham would require Starmer to set out a timetable for his departure and warned that the uncertainty over the party’s leadership could not be allowed to continue. Burnham is expected to be a leading contender in any future leadership race if elected to parliament. Starmer, meanwhile, has rejected calls to resign, insisting he will fight to remain prime minister and signaling that he would like Burnham to take a senior government role if he wins the byelection. The comments highlight growing internal Labour tensions and speculation about a potential leadership challenge. FTSE 100 -0.23% to 10470, GBPUSD -0.157% to 1.341, 10y gilt -3.4bp to 4.754%.
The IEA Oil Market Report for June forecasts that global oil demand will decline by 1.1 mb/d y/y in 2026, a 700k b/d downgrade from the May report, with Q2 deliveries having plunged by 5 mb/d y/y on higher fuel prices and weaker product availability. Global supply is expected to fall by 3.9 mb/d to 102.4 mb/d in 2026 before recovering in 2027, while refinery crude throughputs are projected to contract by 2 mb/d to 82 mb/d. Observed inventories continued to fall sharply in May, and OECD government stocks dropped to the lowest level since December 1990. The report also noted a sharp drop in North Sea Dated crude prices amid easing Middle East tensions and an interim U.S.-Iran agreement that could support a gradual recovery in Gulf exports. The first look at 2027 balances shows a significant overhang emerging next year. Global oil demand is projected to rise by a relatively modest 2 mb/d to 105.3 mb/d. By contrast, oil supplies look set to surge by around 8 mb/d to 110 mb/d. This may provide a welcome respite to the market and an opportunity to replenish depleted inventories or to build new strategic reserves, as countries review their energy strategies and policies in response to the crisis. Brent +0.076% to 79.02, WTI +0.027% to 76.07, Omani crude -7.716% to 72.24, Dubai crude -4.243% to 80.656.
FOMC is expected to keep rates on hold at 3.75% with Chair Kevin Warsh speaking at 2.30pm, along with the quarterly SEP (dot plot).
U.S. May advance retail sales are forecast to hold at 0.5% m/m vs. 0.5% m/m. Retail sales ex auto are expected to ease to 0.6% m/m vs. 0.7% m/m. Retail sales ex auto and gas are expected to ease to 0.3% m/m vs. 0.5% m/m.
U.S. April business inventories are forecast to ease to 0.5% m/m vs. 0.9% m/m.
U.S. May pending home sales are expected to slow to 1.0% m/m vs. 1.4% m/m.
Central bank speakers: The ECB’s Olaf Sleijpen speaks at the European Economics & Financial Centre.
U.S. Treasury sells $69bn in 17-week bills.
Mood: Market sentiment remains fragile, with persistent global equity outflows partly offset by a continued moderation in demand for core government bonds. iFlow Mood has improved marginally to -0.305.
FX: Strong demand for USD persisted, driven by sizable outflows from CAD and AUD, alongside EUR selling within the G10. Flows across LatAm and EMEA were mixed, while APAC currencies generally attracted modest inflows.
FI: Demand was concentrated in Eurozone, Japanese and Colombian government bonds, while South Korean, Indonesian and Australian government bonds remained under selling pressure.
Equities: Broad-based equity outflows continued across the iFlow universe, led by Taiwan, South Korea, South Africa, Türkiye, Chile, the U.K. and the Eurozone. Selective inflows were observed in Australia, the U.S. and Mexico.
“People almost invariably arrive at their beliefs not on the basis of proof but on the basis of what they find attractive.” – Blaise Pascal
“For the great enemy of the truth is very often not the lie – deliberate, contrived and dishonest – but the myth – persistent, persuasive and unrealistic.” – John F. Kennedy
Euro area inflation came in at 3.2% y/y in May, up from 3.0% in April and 1.9% a year earlier. In the EU, inflation also picked up to 3.3% from 3.2%. Monthly inflation was 0.1% in both areas. Services remained the main driver, adding 1.61 percentage points to the euro area rate, followed by energy at 0.98 percentage points. Food, alcohol and tobacco added 0.36 percentage points, while non-energy industrial goods contributed 0.23 percentage points. Among member states, Romania posted the highest rate at 9.7%, while Sweden had the lowest at 1.1%. Euro Stoxx 50 +0.11% to 6264, EURUSD -0.061% to 1.1601, BBG AGG Euro Government High Grade EUR -0.9bp to 3.215%.
U.K. inflation data for May showed the Consumer Prices Index including owner-occupiers’ housing costs (CPIH) unchanged at 3.0% y/y. The standard Consumer Prices Index (CPI) also held steady at 2.8% y/y. Both CPIH and CPI rose by 0.2% m/m, matching the year-earlier pace. Transport provided the largest upward contribution to the monthly change in both annual rates, while food and non-alcoholic beverages were the main drag. Core measures were mixed, with core CPIH steady at 2.8% and core CPI edging up to 2.6%. Goods inflation slowed, but services inflation accelerated in both series. FTSE 100 -0.23% to 10470, GBPUSD -0.157% to 1.341, 10y gilt -3.4bp to 4.754%.
U.K. producer prices for May showed firmer cost pressure, with producer input prices rising 8.7% y/y, up from a revised 7.9% in April. Meanwhile, factory gate output prices increased by 4.0% y/y, slightly below the previous month’s revised 4.1%. On a m/m basis, input prices edged up 0.2% and output prices rose 0.5%. Crude oil and refined petroleum products were the main drivers of annual inflation for input and output prices, respectively, while chemicals and other manufactured outputs led the monthly gains, partly reflecting higher plastic costs. The Import Price Index also accelerated, rising 10.1% y/y in May, from 8.8% in April.
U.K. private rent inflation continued to ease in May, with average monthly rents rising 3.3% y/y to £1,383, down from 3.5% in April. Rents increased by 3.4% to £1,442 in England, 4.7% to £836 in Wales and 1.0% to £1,009 in Scotland, while Northern Ireland recorded 3.3% growth to £876 in March. Within England, the fastest rental inflation was in the North East at 5.9%, and the slowest in London at 2.0%. U.K. house prices rose 3.8% in April to £270,000, rebounding from zero growth in March on a base effect linked to earlier stamp duty changes.
Hungary’s average gross earnings for April came in at HUF 772,200 for full-time employees, while average net earnings reached HUF 541,200. Gross pay rose by 9.0% y/y, net pay by 11.2% and real earnings by 8.9%, as consumer prices climbed 2.1%. The stronger rise in net earnings reflected larger family tax allowances and new tax exemptions for mothers. Regular gross earnings, excluding bonuses, were HUF 711,400, up 8.4%. Median gross earnings stood at HUF 616,000 and median net earnings at HUF 436,400, both posting solid y/y gains. Budapest SI -0.26% to 138365, EURHUF -0.258% to 349.89, 10y HGB -13bp to 5.07%.
South Africa’s headline consumer price index for all urban areas rose to 4.5% y/y in May, up from 4.0% in April 2026, while prices increased by 0.7% m/m. The pickup in inflation was driven mainly by housing and utilities, transport, and insurance and financial services, which together made the largest contributions to the annual rate. Goods inflation accelerated to 4.4% from 3.4%, while services inflation edged higher to 4.7% from 4.6%. Overall, the release points to firmer price pressures in both goods and services, with transport and housing costs remaining key inflation drivers in the month. JSE TOP 40 +0.06% to 107612, USDZAR -0.63% to 16.2395, 10y SAGB -9bp to 8.429%.
Japanese trade data for May showed exports rising 17.0% y/y to ¥9.51tn, while imports increased by 12.5% y/y to ¥9.89tn, leaving a trade deficit of ¥0.38tn – smaller than a year earlier. Export growth was led by electrical machinery, transport equipment and machinery; semiconductor-related shipments were particularly strong. Imports were lifted by mineral fuels, electrical machinery and machinery, though food imports declined. By destination, exports to the U.S. (12.5% y/y), China (17.9%), the EU (14.5%) and Asia (19.5%) all increased, with especially strong gains to Taiwan (37.7%), South Korea (22.2%) and Malaysia (38.2%). On the import side, purchases from Asia (21.7% y/y), the U.S. (26%), Taiwan (43.2%) and South Korea (26%) rose, while imports from the Middle East (-42.7% y/y) fell sharply, reflecting lower energy-related inflows. The report indicates broad-based export strength alongside softer energy import costs. Nikkei +0.72% to 69902, USDJPY +0.025% to 160.25, 10y JGB -4bp to 2.603%.
Japan’s machinery orders rose 3.4% m/m (seasonally adjusted) in April, indicating a modest improvement in overall demand. Private sector machinery orders, excluding volatile orders for ships and those from electric power companies, increased by 8.7% m/m and 15.6% y/y, suggesting stronger underlying business investment appetite. Overall, the data point to a pickup in orders after the previous month, with private demand showing particularly firm momentum.
New Zealand’s current account deficit widened to NZ$4.6bn in the March quarter, up NZ$100mn q/q. New Zealand’s annual current account deficit was NZ$16.3bn, or 3.6% of GDP. The deterioration was driven mainly by a larger goods deficit, which widened to NZ$1.1bn from NZ$757mn as imports rose NZ$680mn on higher imports of mechanical and machinery equipment, partly offset by a fall for petroleum and petroleum products. Goods exports increased by NZ$356mn to NZ$21.0bn, led by fruit and meat, while dairy fell. The services balance remained in surplus at NZ$33mn, though slightly below the prior quarter, as services exports and imports both rose. The primary income deficit narrowed to NZ$3.3bn from NZ$3.5bn, helped by lower earnings on both overseas investments and foreign investment in New Zealand. NZX 50 -0.25% to 13393, NZDUSD -0.377% to 0.5813, 10y NZGB -7bp to 4.379%
New Zealand’s Q2 consumer confidence fell sharply, with the Westpac-McDermott Miller Consumer Confidence Index dropping 14.3 points q/q to 80.4, the lowest level since 2023. The decline reflects rising fuel and other living costs, higher borrowing costs and worsening concerns about economic activity, all of which have weighed on household spending. The survey suggests both current and expected conditions weakened materially, while the “good time to buy” reading remained subdued. The note also flags some possible relief ahead: if the recent ceasefire extension in the Middle East holds and oil prices continue to ease, disruptions to transport, shipping and supply chains may gradually fade, supporting a recovery in confidence and economic activity later in the year.
At the 2026 Lujiazui Forum, Chinese officials outlined a broad set of financial policy initiatives. PBoC Governor Pan Gongsheng said the central bank will refine short-term rate controls, launch a repo facility for foreign central banks, pilot offshore RMB FX trading in the Shanghai Free Trade Zone, study a macroprudential liquidity support tool for non-bank institutions and issue an action plan for Shanghai’s offshore finance development. He also announced the official launch of the interbank market data reporting repository. CSRC Chairman Wu Qing emphasized tighter regulation across market entry, ongoing supervision and exit, while cracking down on speculative abuse, market manipulation and insider trading, and backing M&A, refinancing and qualified Hong Kong-listed firms seeking mainland listings. NFRA chief Ding Xuexiang said China will improve prudential and inclusive regulation and support offshore finance and reinsurance. SAFE will issue a new batch of QDII quotas. CSI 300 +0.97% to 4931, USDCNY -0.008% to 6.7572, 10y CGB -1bp to 1.725%.
South Korea’s central bank has said inflation is likely to stay elevated for an extended period despite the end of the Middle East conflict. The Bank of Korea cited lingering upside pressures from higher incomes in the technology sector, public service charges, elevated crude oil costs and a weak won. South Korea’s consumer price inflation rose to 3.1% y/y in May, the fastest pace in 26 months, matching the pace in March 2024. The BoK said inflation is expected to remain around 3% in Q2, while core inflation, excluding food and energy, should stay in the mid-2% range. It also noted that previous energy shocks had spillover effects on non-energy prices with a delay of about six months and lasting roughly a year. KOSPI +1.58% to 8864, USDKRW -0.337% to 1514.4, 10y KTB -1bp to 4.11%.
Singapore’s external trade data rallied strongly in May. Non-oil domestic exports (NODX) rose 38.4% y/y (April: 24.4%), led by a surge for electronics (+94.8% y/y) and stronger non-electronics (+17.7% y/y). The main contributors were ICs, disk media products and PCs, while pharmaceuticals, specialized machinery and non-monetary gold supported non-electronics. NODX to key markets increased in particular for Taiwan (135.2% y/y), the U.S. (80.9%) and China (31%), while Indonesia (-26.9%) saw a fall. Non-oil re-exports (NORX) climbed 33.6% y/y (April: 29.6%), driven by electronics and non-electronics, with gains in ICs, other computer peripherals and parts of PCs. Overall merchandise trade expanded by 39.7% y/y (April: 33.0%), as exports rose by 36.1% y/y and imports by 43.6% y/y. STI +1.19% to 5178, USDSGD -0.117% to 1.2827, 10y SGB -0.4bp to 1.998%.
The Monetary Authority of Singapore’s June Survey of Professional Forecasters showed economists slightly lowering their 2026 GDP growth expectations to 3.5% y/y (from 3.6% in March), despite Q1 growth surprising to the upside at 6.0% y/y (vs. an estimate of 5.8%). Respondents now see Q2 growth at 4.3% y/y and 2027 growth at 2.5% y/y. Inflation forecasts were lifted: CPI-All Items inflation is projected at 2.3% y/y in 2026 (from 1.5%), while MAS core inflation is seen at 2.0% y/y (from 1.5%). Q1 CPI inflation was 1.5% y/y and core inflation 1.4% y/y, both broadly in line with or below prior expectations. Risks remain skewed to the downside from a prolonged Middle East conflict, while an AI-led tech cycle remains the key upside risk.
The Banco Central de Chile has unanimously held its monetary policy rate at 4.5%. It judges that the balance of risks to inflation has been shifting gradually toward equilibrium, although the macroeconomic outlook remains subject to higher-than-usual uncertainty. The board said the external backdrop remains dominated by Middle East tensions and higher oil prices, though recent ceasefire news briefly eased crude prices and supported global markets. Domestically, activity contracted in Q1, driven mainly by weak natural resource sectors, while consumption remained resilient and investment softened. The labor market also weakened, with unemployment rising. Inflation accelerated, as expected, with CPI rising to 3.9% y/y in May (April: 3.5% y/y), largely due to fuel costs, while core inflation was unchanged at 3.2% y/y. Inflation expectations remain near 3%. The bank maintained a cautious stance and said future rate decisions will be made meeting by meeting to ensure inflation converges to 3% over a two-year horizon. CSM Select +0.23% to 10904, USDCLP +0.807% to 885.56, 10y CGB -2bp to 5.64%.