Market Movers: Selective
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Wee Khoon Chong
Time to Read: 4 minutes
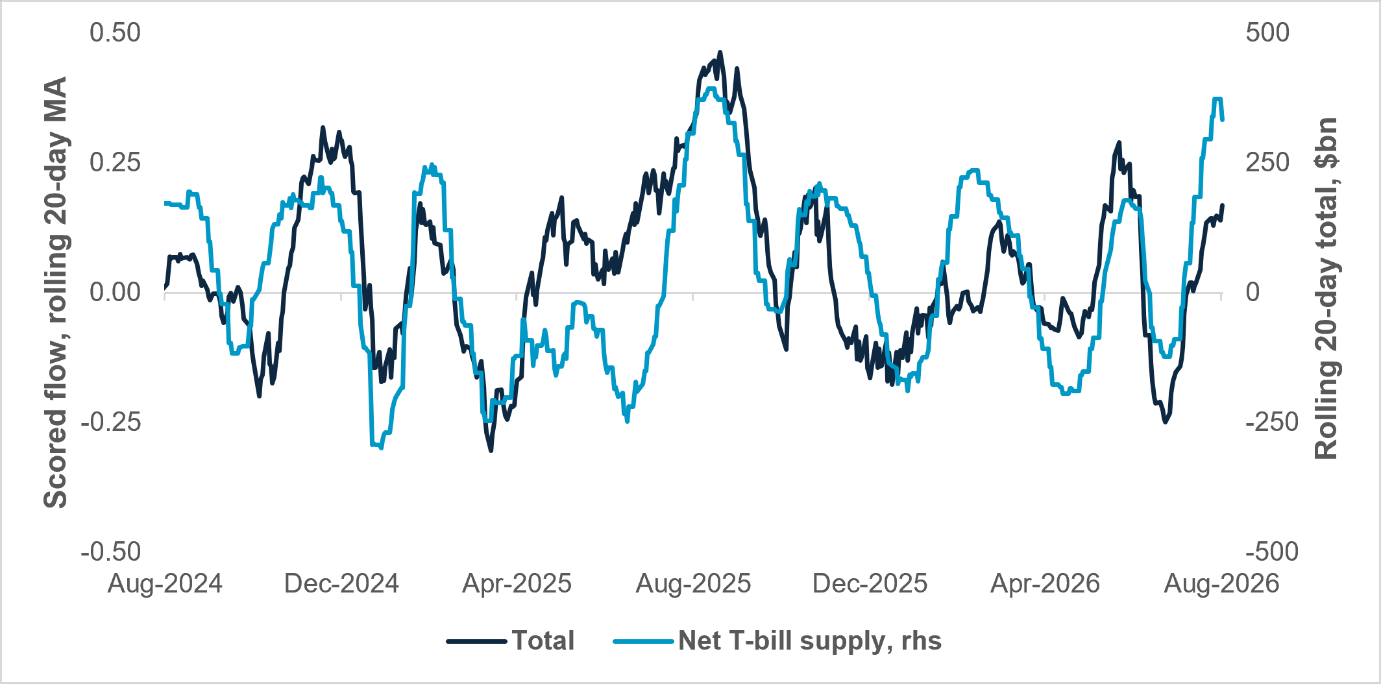
T-bill supply and investor demand
Source: BNY
In its quarterly refunding announcement, the U.S. Treasury announced that it expects to borrow nearly $750bn between July and September, and another $630bn between October and December. The bulk of the additional borrowing will be through T-bill issuance. We don’t think that the market will suffer much – if any – indigestion when this supply comes online. The chart shows that demand for Treasurys with maturities below one year waxes and wanes with net T-bill issuance, generally rising and falling to match net supply.
Risk appetite: Risk appetite has improved but remains selective and concentrated in technology. Asian risk assets have held firm, led by tech; the Asia Semiconductor Index has rebounded by around 20% from its July lows. Tech sentiment is consolidating, supported by sustained foreign inflows into both Taiwan and South Korea this week following aggressive selling in July. In contrast, the commodity rally has paused for breath, with gold and silver ending their recent winning streaks.
Japan: Sanae Takaichi’s government’s support for a near-term BoJ rate hike has failed to reverse bearish sentiment in Japan. Persistent price pressures, reinforced by high PPI data, have kept USD/JPY drifting toward the psychologically important 160 level. Long-end JGB yields have moved higher as spreads between JGBs and Treasurys widened. We will closely monitor whether higher yields attract renewed foreign inflows or reinforce concerns over duration risk.
Bottom line: The market remains in a selective risk-on regime, with technology and renewed foreign inflows providing the clearest support. Japan remains the key area of divergence: higher yields and more hawkish policy expectations are still failing to support JPY, leaving flows as the critical signal to watch.
Norges Bank has kept its policy rate unchanged at 4.25%. Its committee said that although inflation has slowed, coming in lower than projected over the summer, it remains too high and it is too early to conclude the outlook has materially improved. The bank reiterated that a restrictive stance is still needed to bring inflation back to target, while noting that it does not want to tighten more than necessary. Capacity utilization appears close to normal but is drifting down, with unemployment little changed, housing prices falling in the secondary market and construction activity weak. The committee said future policy will depend on incoming data, with new forecasts due at the September meeting. OSE +0.3% to 2068, EURNOK -0.046% to 10.9605, 10y NGB +0.6bp to 4.371%.
The RBA’s Assistant Governor Christopher Kent has commented that Australia’s monetary policy is now somewhat restrictive and that the earlier tightening is working. Higher borrowing costs, rising mortgage payments, weaker established housing market conditions and a stronger Australian dollar have all tightened financial conditions, while aggregate demand is slowing as intended to help return inflation to target. Estimates of the nominal neutral rate also support the view that policy is mildly restrictive. The board notes, however, that non-policy forces are also affecting conditions. The housing market appears to have softened more than recent rate rises alone would suggest, making conditions a bit tighter than otherwise. Offsetting this, resilient global demand linked to AI investment and higher offshore yields due to large public debt burdens could make conditions in Australia less restrictive than would otherwise be the case. The board will keep reviewing these factors when assessing the outlook and policy stance. ASX -0.18% to 5833, AUDUSD -0.213% to 0.705, 10y ACGB -3.4bp to 4.991%.
In its Q2 monetary policy report, the PBoC promised additional pragmatic policy measures and stronger countercyclical adjustments to support China’s economy. It said it will maintain ample liquidity, relatively accommodative financing conditions and low overall financing costs, while using monetary tools flexibly and in a timely manner. It struck a more confident tone on domestic conditions than in Q1, saying high-quality development has made new progress and the long-term growth foundation is more solid. The bank also urged policymakers to remain confident and take concrete steps to consolidate and expand the steady economic recovery. It highlighted efforts to improve the monetary framework, including a shift in operational focus toward the overnight money market rate and better liquidity management. CSI 300 -0.57% to 4664, USDCNY -0.006% to 6.7453, 10y CGB -0.3bp to 1.702%.
South Korea’s Financial Services Commission has said it will ease household lending restrictions and unlock about ₩30tn in additional loans this year to support real estate market stabilization. The annual household debt growth target will be raised from 1.5% to around 3%, creating more lending capacity for genuine homebuyers, including younger borrowers. The authorities said the move is aimed at supporting housing supply and easing the recent “loan rush” caused by tighter bank lending limits. To curb speculation, core safeguards such as loan-to-value and debt-service ratio rules will remain in place, and jeonse loans for non-resident single-home owners will be restricted. The announcement reflects continued concern over South Korea’s high household debt burden, while balancing financial stability against housing market support. KOSPI +3.56% to 6813, USDKRW -0.471% to 1423.7, 10y KTB -1bp to 4.285%.
U.S. initial jobless claims are forecast to rise to 202k vs. 199k.
U.S. July PPI final demand is forecast at 0.2% m/m, 4.9% y/y vs. -0.3% m/m, 5.5% y/y in June. PPI ex food and energy is forecast at 0.3% m/m, 4.1% y/y vs. 0.2% m/m, 4.7% y/y in June, with PPI ex food, energy and trade forecast at 0.3% m/m, 4.6% y/y vs. 0.1% m/m, 5.1% y/y in June.
Central bank speakers: The Fed’s Beth Hammack speaks in a moderated discussion. The Fed’s Tom Barkin speaks on the economic outlook and monetary policy.
U.S. Treasury sells $110bn in 4-week bills, $100bn in 8-week bills and $25bn in 30y bonds.
Mood: iFlow Mood remained in neutral territory on continued strong inflows into equities and fixed income.
FX: Global FX flows were fairly mixed globally. GBP, MXN and KRW saw inflows, while JPY and CZK came under selling pressure.
FI: Fixed income flows were generally biased toward inflows, with strong inflows into Argentine and Turkish sovereign bonds and gilts, while Norwegian bonds saw significant outflows.
Equities: G10 equity flows were muted. EMEA and APAC enjoyed strong inflows, including among Polish, Taiwanese, Indian, South African and Malaysian equities.
“Stay hungry. Stay foolish.” – Steve Jobs
“Risk comes from not knowing what you’re doing.” – Warren Buffett
The U.K.’s first quarterly estimate of April-June GDP showed real GDP rising by 0.4% q/q from 0.6% in Q1 and by 1.2% y/y (Q1: 0.9% y/y). Growth was driven by services (+0.5% q/q), with construction also up (+0.3% q/q), while production was flat. On the expenditure side, GDP growth was supported by gross fixed capital formation and household consumption; household spending rose 0.3% q/q and business investment increased by 1.7% q/q. Net trade remained a drag, with the trade deficit at 1.0% of nominal GDP excluding non-monetary gold. Nominal GDP rose 0.8% q/q and 4.1% y/y, while the GDP deflator increased 2.9% y/y. Real GDP per head also rose 0.4% q/q and 1.0% y/y. FTSE 100 -0.22% to 10810, GBPUSD -0.237% to 1.3483, 10y gilt +0.7bp to 4.977%.
U.K. production output was flat in Q2, following 0.2% growth in Q1. Over the quarter, manufacturing rose 1.0% and mining and quarrying increased by 0.2%, but this was offset by falls in electricity and gas (-2.3%) and water supply and sewerage (-3.7%). In manufacturing, gains in basic pharmaceutical products and computer, electronic and optical products helped lift the sector. U.K. production output fell 0.2% m/m in June, after a 0.7% drop in May 2026 and a 0.4% rise in April 2026. The m/m fall was driven by manufacturing (-0.5%), water supply and sewerage (-1.5%) and electricity and gas (-0.3%) and was partly offset by mining and quarrying (+5.1%), led by crude petroleum and natural gas extraction, which bounced back from May’s weakness.
U.K. services output rose 0.4% m/m in June, following 0.1% growth in May and a 0.1% decline in April. Services output increased by 0.5% q/q in Q2, easing from 0.8% growth in Q1. Gains were broad-based: 10 out of 14 sectors posted q/q rises, led by information and communication (+2.7%) and professional, scientific and technical activities (+1.7%). M/m gains were also spread across eight sectors, with the biggest positive contributions from professional, scientific and technical activities (+1.0%) and administrative and support service activities (+1.8%). The only m/m decline came from “activities of households as employers” (-0.3%). Administrative and support service activities and education were the main q/q drags.
U.K. trade weakened in June, with both goods imports and exports down. In current prices, goods imports declined by 0.7% m/m to £54.0bn, as lower purchases from both EU and non-EU markets more than offset a rise in machinery and transport equipment. Goods exports fell more sharply, down 6.3% m/m to £33.0bn, driven by declines to both EU and non-EU countries. By commodity, weaker exports reflected falls for fuel, chemicals, machinery and transport equipment, and material manufactures; lower crude oil shipments to Germany and Poland and reduced pharmaceutical exports to Germany were notable. In volume terms, goods imports rose 1.1% m/m, while goods exports fell 4.7% m/m. For Q2, the total goods and services trade deficit widened q/q to £8.0bn.
The July RICS Residential Market Survey shows the U.K. housing market remains weak, with buyer demand and sales still stuck in negative territory. New buyer inquiries were unchanged at a net balance of -28% for a second successive month, while agreed sales also held at -30%, suggesting subdued activity and only a limited easing in the pace of deterioration. Near-term sales expectations improved slightly to -14% but remain pessimistic. New instructions flattened at -4%, indicating a tight pipeline of listings. House prices stayed under pressure, with the national price balance at -30% and weaker readings in London, the South West and the South East, while Northern Ireland still reported gains. In the rental market, tenant demand was broadly flat at -1%, landlord instructions were again weak at -27% and rent expectations remained positive.
Spain’s CPI rose 3.6% y/y in July, up 0.4 percentage points from June, while core inflation edged up to 3.0% y/y from 2.9%. Monthly CPI increased by 0.3% m/m. The main upward drivers were transport, where annual inflation climbed to 6.2% on higher fuel and lubricants costs, and housing, which rose to 5.7% y/y on stronger electricity prices. Conversely, clothing and footwear fell 10.2% m/m due to summer sales, while food and non-alcoholic beverages were down 0.7% m/m on lower prices for fruit, nuts, vegetables, pulses and potatoes. Spain’s HICP (IPCA) accelerated to 3.9% y/y from 3.6%, with a flat 0.0% m/m reading. Inflation was positive across all regions, with Cantabria the highest at 4.3% and Extremadura the lowest at 3.0%. IBEX 35 +0.72% to 20329, EURUSD -0.122% to 1.1521, 10y Bono -0.3bp to 3.597%.
Swedish CPI inflation eased to 0.2% y/y in July from 0.7% in June and fell 0.3% m/m. CPIF inflation slowed to 0.7% y/y from 1.3%, and CPIF-XE rose to 0.6% from 0.4%. The m/m decrease was driven mainly by lower electricity and fuel prices, alongside cheaper public transport, childcare, clothing and dental services. Electricity fell by 11.6% m/m and fuels by 9.4% m/m, while public transport dropped 26.4% m/m. Offsetting this were higher package holiday and car rental prices, with seasonal rises also seen in electronics, food, and restaurant and accommodation services. Over the year, package holidays, restaurants and accommodation, rents and electricity pushed inflation higher, counteracted by food, public transport and dental services. OMX +0.23% to 3299, EURSEK -0.32% to 11.0367, 10y Swedish GB +1.2bp to 3.019%.
Japan’s Corporate Goods Price Index rose 0.1% m/m in July, after 0.5% m/m in June, leaving the PPI up 7.2% y/y. Excluding extra charges for summer electricity, the index was flat m/m and also up 7.2% y/y. Price pressure was driven by higher electric power, gas and water, beverages and foods, non-ferrous metals, plastic products and electrical machinery; these gains were partly offset by lower petroleum and coal products, chemicals, agriculture, forestry and fishery products, and scrap and waste. Export prices fell 0.6% m/m in contract-currency terms, while import prices rose 0.3% m/m, led by electric and electronic products, with declines in petroleum, coal and natural gas, metals, chemicals and food-related items. Nikkei +1.16% to 68309, USDJPY -0.132% to 159.39, 10y JGB +3.4bp to 2.891%.
New Zealand’s REINZ housing report for July showed prices broadly steady but market activity slowing. The national median price was NZ$760,000 (-0.7% y/y), while the number of sales fell to 6,090 (-10.0% y/y). The national HPI eased to 3,550 (-0.4% y/y). Supply was somewhat firmer, with inventory rising to 33,252 (+9.3% y/y) and new listings broadly flat at 7,698 (-0.5% y/y). Homes also took longer to sell, with days to sell at 50 (+2 days y/y), the fifth-slowest July on record. Performance diverged by region: West Coast and Gisborne were the strongest markets, while Wellington remained weak. REINZ said buyers are cautious, with the July OCR increase, cost-of-living pressures, global uncertainty and the upcoming election all weighing on sentiment. NZX 50 +0.64% to 13825, NZDUSD -0.495% to 0.5831, 10y NZGB -4.9bp to 4.645%.
New Zealand’s August Survey of Expectations showed inflation expectations easing at the short and medium end. One-year-ahead CPI inflation fell to 2.60% from 3.41%, while two-year-ahead expectations dropped to 2.34% from 2.53%. Longer-term expectations ticked up slightly, with five-year-ahead at 2.31% and ten-year-ahead at 2.20%. Respondents now see the OCR at 2.73% by end-September, and one-year-ahead OCR expectations rose to 3.21% from 3.01%. Unemployment expectations eased to 5.24% one year ahead and 4.90% two years ahead. Wage inflation, house prices and real GDP growth expectations all increased. The survey followed the June-quarter CPI print of 4.1% y/y and comes ahead of the RBNZ’s next Monetary Policy Statement on September 2.
The Bank of Korea said it held $250.4mn in SPDR Gold Trust shares at end-Q2, marking its first gold investment in 13 years. The holding was not present in its Q1 filing, indicating that the purchase was made during the quarter, though the exact timing was not disclosed. The ETF provides exposure to gold price movements without physical ownership. The central bank last bought gold in 2013, when it purchased 20 tons. The BoK said gold ETFs are counted as foreign securities and included in South Korea’s foreign reserves. Separately, it recently outlined plans to buy domestically produced gold to diversify reserves and hedge against geopolitical and inflation risks. KOSPI +3.56% to 6813, USDKRW -0.471% to 1423.7, 10y KTB -1bp to 4.285%.
In South Korea, foreign investors scaled back their net selling of stocks to $20.7bn in July from $32.37bn in June, while selling a $960mn of bonds after three straight months of buying. The Bank of Korea said the smaller equity outflow reflected easing rebalancing-related selling as the KOSPI fell, though geopolitical tensions kept funds flowing out. Bond outflows came despite the inclusion of KTBs in the WGBI. The won was highly volatile, with the exchange rate moving from the ₩1,550 range to the ₩1,450 range in July and averaging an 8% daily fluctuation versus 7.6% in June. The BoK said reduced foreign portfolio rebalancing had also helped the won strengthen against the U.S. dollar during the review period amid the greenback’s recent weakness globally.