Market Movers: Scrutiny
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Geoff Yu
Time to Read: 5 minutes
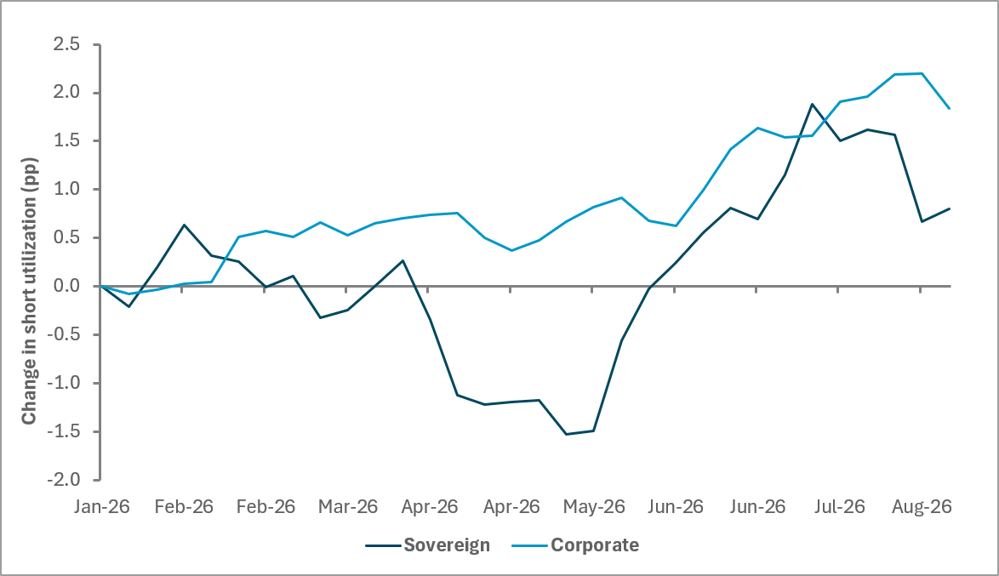
Moderate pick-up in short utilization in U.S. paper
Source: BNY
One of the reasons the relief rally from the U.S. Treasury buyback announcement could be brief, is that short utilization wasn’t high in the first place in the long end. Our data confirm that. Investors took profit on long-end protection and didn’t rebuild it as the curve steepened. The subsequent rally therefore can’t be explained solely by cash-Treasury short covering; crowded steepener exposure is more likely concentrated in curve and derivative positions. Limited protection could leave the curve vulnerable to renewed steepening if fiscal and inflation concerns persist – even a recovery to mid-June levels would require around a 1.5pp boost in short utilization, meaning that the fraction of bonds in the BNY lending program that have been sold short as a percentage of outstanding bonds in the program would rise.
In contrast, corporate short utilization has been rising consistently. There are inflation premia in play, but we’ve also highlighted that increased issuance in the tech space is starting to crowd out conventional paper, raising costs accordingly. Hence, market structure and additional spread pressures have been steadily factored into the corporate market and provide more scope for short covering comparatively, representing a tactical risk-positive opportunity. However, structurally, fixed-income vol will remain elevated.
Relief fades: Wednesday’s Treasury buyback announcement delivered an immediate rally in bonds and risk assets, but the follow-through has been less convincing. European markets are softer, and gains across Asia have been uneven. The message is not that the intervention failed, but that investors are already looking beyond the initial liquidity impulse and scrutinizing what it says about the underlying problem.
Structural doubts: Treasury has successfully lowered long-end yields and eased financial conditions, at least temporarily. But the structural backdrop hasn’t changed. U.S. government debt crossed $40tn yesterday, while deficits and financing needs remain large. Against that backdrop, larger long-end buybacks look more like buying time than removing the source of upward pressure on yields.
Price of intervention: Bond markets have calmed, which is meaningful, but the next test is whether managing the yield curve begins to conflict with monetary-policy objectives. If Treasury actions loosen conditions while inflation remains above target, the Fed may eventually need to offset some of that impulse. Gold pushing through $4,500/oz. and Bitcoin briefly touching $70,000 suggest markets don’t view the move as costless. Some of the adjustment may simply be migrating away from bond yields and into alternative stores of value.
Ahead today: Jobless claims are the main data release, but markets will continue digesting yesterday’s policy signal. Although the U.S. actions have bought time and provided relief, official-sector intervention can only go so far and may prove counterproductive over time. Fiscal restraint remains structurally elusive globally, leaving inflation with a near-permanent fiscal markup. Household demand, employment, and earnings growth will ultimately determine whether easier financial conditions are justified by the real economy.
The Swedish Riksbank left its policy rate unchanged at 1.75%, saying the move was well balanced given a mixed backdrop of stronger-than-expected growth and inflation, alongside a weaker labor market and subdued company pricing plans. The Riksbank noted that summer inflation came in above its June forecast and that underlying inflation is close to 2%, while measured inflation remains low because of temporary fiscal measures. It also highlighted ongoing uncertainty from the Middle East conflict, though the economic impact so far has been smaller than feared. The bank said the outlook is broadly unchanged, but a rate increase later this year remains possible if inflation proves more persistent. OMX +0.41% to 3,257, EURSEK +0.264% to 11.0501, 10y Swedish GB -1.1bp to 3.064%.
Japan's portfolio flow showed foreign investors accelerated JGB selling last week, with net outflows of ¥1.25tn, cutting YTD foreign net purchases to ¥4.99tn, the lowest cumulative level since early February. Despite the sharp rise in JGB yields, higher returns are not drawing foreign demand, raising the risk of further bond unwinding. At the same time, Japanese investors increased overseas allocation, buying ¥1.14tn of foreign bonds and ¥1.39tn of foreign equities, the second-largest weekly equity purchase this year. Overall, the flow mix points in the same direction for the currency: foreign selling of Japanese bonds and stronger Japanese buying of foreign assets weaken support for JPY and leave it vulnerable to further depreciation. Nikkei +1.36% to 66,217, USDJPY +0.203% to 158.49, 10y JGB -4.2bp to 2.86%.
Australia’s gross federal debt has crossed AU$1tn for the first time, marking a symbolic fiscal milestone two decades after the Howard government’s “Debt Free Day.” The Australian Office of Financial Management will push debt above the threshold after issuing AU$4bn of Treasury bonds. Gross debt is now about 34% of GDP and is forecast to reach 35.8% by 2029. Treasury expects the annual interest bill to rise to AU$29.5bn in this financial year and AU$42.2bn by 2030, while the Parliamentary Budget Office sees debt-servicing costs increasing from 4.1% in 2024–2025 to 6.2% in 2029–2030. The government said gross debt doesn’t tell the full fiscal story, while the Coalition blamed spending and warned the burden will fall on younger Australians. ASX -0.24% to 5,782, AUDUSD +0.029% to 0.7127, 10y ACGB -5bp to 5.007%.
The Reserve Bank of India’s net-short forward-dollar position remains “very manageable,” Governor Sanjay Malhotra said, despite the central bank’s large bearish dollar bet built over the past two years to support the rupee. He said the exchange rate remains market-determined, while intervention is still aimed at curbing excessive volatility and speculative activity. Malhotra defended the early closure of the FCNR(B) swap window as a data-driven calibration, not a policy reversal. He also said inflows into India have been stronger than expected and that the RBI expects at least $80bn from recent measures to attract foreign currency, including FCNR(B) deposits, external commercial borrowings, and overseas foreign-currency borrowings. He added that each additional swapped dollar offers diminishing benefits, while sterilization costs rise. SENSEX +0.83% to 77,551, USDINR -0.06% to 95.705, 10y INGB +3.8bp to 6.855%.
U.S. August Philadelphia Fed Business Outlook is forecast to ease to 25.0 vs. 41.4.
U.S. Initial Jobless Claims are forecast to rise to 210k vs. 209k.
U.S. July Leading Index is forecast to rise to 0.1% m/m vs. -0.2% m/m.
Canada July Industrial Product Price is forecast to rise to -0.5% m/m vs. -1.4% m/m.
Canada July Raw Materials Price Index is forecast to rise to -2.0% m/m vs. -6.9% m/m.
U.S. Treasury sells $110bn 4-week bills, $100bn 8-week bills and $8bn of 30y TIPS reopening.
Mood: iFlow Mood steadied at -0.116 as demand for core sovereign bonds and global equities stabilized.
FX: Currency flows were moderately biased toward outflows across G10 and APAC, including CNY, GBP and JPY, while EUR and USD were bought. LatAm and EMEA flows were mixed, with notable PEN inflows.
FI: There was broad demand for G10 government bonds, led by Eurozone sovereigns and U.K. gilts. Selling was concentrated in Peru, Norway, Poland and China.
Equities: There was strong demand across G10 and APAC equities, led by the U.S. and Taiwan. LatAm and EMEA flows were mixed.
“If a man will begin with certainties, he shall end in doubts.” – Francis Bacon
“Doubt is not a pleasant condition, but certainty is absurd.” – Voltaire
Poland's producer prices for July rose 2.8% y/y and 0.6% m/m, extending the return of annual industrial price inflation that began in March. Manufacturing prices increased 3.2% y/y and 0.7% m/m, while mining and quarrying prices rose 3.8% y/y, despite falling 0.2% on the month. Water supply, sewerage and waste management prices increased 2.3% y/y and 0.2% m/m. By contrast, electricity, gas, steam and air conditioning prices remained 0.8% below year-earlier levels, although they rose 0.3% from June. The data point to a continued rebuilding of producer price pressure across most industrial categories, led by manufacturing and mining, even as energy-related prices remain softer on an annual basis. WIG -0.73% to 151,365, EURPLN -0.033% to 4.3159, 10y PGB +1.9bp to 5.914%.
Japan’s July 2026 trade showed a sharp improvement in external demand and import momentum. Exports rose 23.2% y/y to a record July high, lifted mainly by automobiles and semiconductor-related electronic parts. Imports increased 27.8% y/y, led by crude oil and semiconductor-related electronic parts. As a result, the trade balance stayed in deficit at ¥634.5bn, marking the third straight month of deficit. On a seasonally adjusted basis, exports rose 2.8% m/m and imports edged up 0.4% m/m, leaving a deficit of ¥686.0bn. By region, exports to the U.S. (22.0% y/y), EU (19.1% y/y) and Asia (24.5% y/y) all grew strongly, while trade with China remained in deficit at ¥775.4bn, with both exports and imports expanding. Nikkei +1.36% to 66,217, USDJPY +0.152% to 158.41, 10y JGB -4.2bp to 2.86%.
China left its benchmark loan prime rates unchanged for August, marking the 15th consecutive month without a move and matching market expectations. The one-year LPR stayed at 3.00% and the five-year LPR at 3.50%. The decision signals policymakers may be leaning more on faster fiscal implementation than fresh monetary easing to support growth, as banks face near-record-low profit margins. The Politburo has pledged to accelerate already-budgeted infrastructure spending rather than launch major new stimulus, and the central bank recently reiterated an appropriately loose monetary stance without signaling explicit policy-rate or reserve-ratio cuts. CSI 300 +0.09% to 4,593, USDCNY +0.085% to 6.7239, 10y CGB -0.1bp to 1.693%.
Shanghai’s housing authorities unveiled the latest eight measures to support reasonable homebuying demand and stabilize the property market. The package expands provident fund support for down payments from only pre-sale new homes to include existing completed homes, while also allowing withdrawals for deed tax, and parking spaces and storage rooms linked to housing. It eases mortgage terms for second homes outside the outer ring, cutting the minimum down payment ratio to 15% from 20%. Shanghai also introduced temporary purchase subsidies: eligible “old-for-new” buyers can receive up to ¥50,000, and some households can stack subsidies for a maximum ¥80,000. The policy also expands relocation via housing vouchers and accelerates purchases of second-hand homes for affordable rental housing supply.
Australia’s Labour Force Survey for July 2026 showed a softer labor market with the unemployment rate edging up to 4.5% from 4.4%. In seasonally adjusted terms, employment fell 0.1% m/m to 14,807,200, after 14,823,100 in June 2026, while full-time jobs rose and part-time jobs declined. The employment-to-population ratio dropped 0.2pp to 63.9%. Participation eased 0.2pp to 66.9%, and monthly hours worked fell 0.6% to 1,998mn. Underemployment was unchanged at 6.4%, while the underutilization rate fell slightly to 10.8%. In trend terms, employment rose 0.2% m/m and the unemployment rate remained at 4.5%. The youth unemployment rate fell 0.3pp to 10.4%. ASX -0.19% to 5,785, AUDUSD +0.665% to 0.7123, 10y ACGB -5bp to 5.007%.
Malaysia’s July 2026 external trade data showed continued strong momentum. Total trade rose 37.3% y/y to RM364.7bn (+RM99.0bn), while exports jumped 38.0% y/y to RM193.6bn and imports increased 36.4% y/y to RM171.1bn. On a monthly basis, exports, imports and total trade rose 8.8% m/m, 5.5% m/m and 7.3% m/m, respectively. The trade surplus widened to RM22.5bn from RM14.8bn a year earlier and was up 42.4% m/m. Growth was driven by both domestic exports and re-exports, while imports rose across intermediate, capital and consumption goods. Year-to-date (January–July 2026), total trade, exports and imports remained firmly in positive territory.
Malaysia’s labor productivity improved further in Q2 2026 as the economy strengthened, with value added rising 6.0% q/q to RM445,896mn, up from 5.4% in Q1 2026. Total hours worked increased 0.5% q/q to 9.6bn hours, while employment rose 1.1% q/q to 16.8mn persons. As a result, labor productivity per hour worked accelerated to 5.5% q/q, reaching RM46.5 per hour, versus 4.8% in the previous quarter. KLCI +0.25% to 1,736, USDMYR +0.426% to 4.0413, 10y MGB +0.6bp to 3.763%.
Taiwan’s July 2026 export orders rose to US$97.94bn, up 2.8% m/m and 61.9% y/y, driven by strong AI, high-performance computing and cloud demand. On a seasonally adjusted basis, orders increased 0.4% m/m. By product, information and communications orders fell 2.6% m/m but jumped 89.5% y/y; electronics rose 2.0% m/m and 71.7% y/y. Optical products declined 6.8% m/m and 10.6% y/y on weak panel demand. By market, the U.S. remained the largest source at US$40.79bn, up 5.5% m/m and 88.9% y/y, followed by China/Hong Kong and ASEAN. The ministry said overseas production accounted for 45.6% of orders, down 0.6pp from a year earlier, and expects August orders to rise vs. July. TAIEX +0.48% to 44,934, USDTWD +0.038% to 31.925, 10y TGB +2.1bp to 1.88%.
Hong Kong’s CPI for July 2026 showed headline inflation at 1.7% y/y, easing from 2.0% in June, while underlying inflation was unchanged at 1.9% y/y. Price gains were led by electricity, gas and water, transport, miscellaneous services, miscellaneous goods, and meals out and takeaway food. Offsetting pressures came from durable goods and basic food, both down 0.2% y/y. The government said lower headline inflation mainly reflected rates concession effects, while fuel-related inflation stayed elevated. It expects oil-price pass-through to keep pressure on consumer prices, but overall inflation should remain moderate as broader price pressures stay contained. Hong Kong’s labor market was broadly stable in May–July 2026. The seasonally adjusted unemployment rate stayed at 3.7% (April–June 2026: 3.7%), while the underemployment rate edged up to 1.7% from 1.6%. Hang Seng +0.8% to 25,698, USDHKD -0.03% to 7.8432, 10y HKGB -1.2bp to 1.417%.