Market Movers: Rotation
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Wee Khoon Chong
Time to Read: 6 minutes
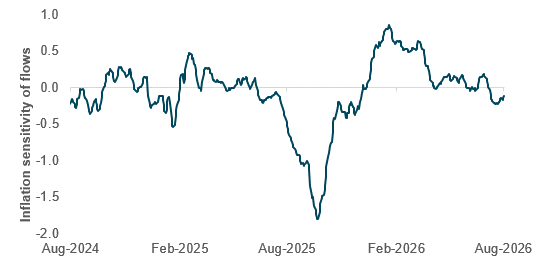
U.S. inflation-related flows
Source: BNY
We can track flows into equities that outperform in environments featuring rising inflation. This helps us to understand equity investors’ inflation expectations. After shrinking in H2 2025 as inflation started to show signs of stability, inflation-related flows turned positive again early this year. More recently, they have headed lower, suggesting inflation expectations among stock-pickers are receding.
Sentiment: Foreign investors are returning to Asian equities, with South Korea and Taiwan attracting more than $10bn of combined inflows this week. Domestic risk appetite is also recovering after the recent rout, with Shanghai margin trading balances rising for eight consecutive sessions. Together, these flows point to broader stabilization in equity sentiment in the region.
Food inflation: Upside risks are building. The drone attack on Russia’s Novorossiysk port and resulting disruption to grain shipments have raised renewed Black Sea supply concerns. The FAO Food Price Index was already moving back toward its 2026 highs, while further geopolitical disruptions and El Niño risks could reinforce food price pressures.
Bottom line: Asian risk sentiment is showing clearer signs of recovery as foreign and domestic flows improve. The next macro risk is food inflation, where Black Sea disruptions and weather risks could create a fresh supply shock.
Fitch has affirmed the U.S.’s sovereign rating at AA+ with a stable outlook, citing the country’s large economy, reserve currency dollar status, dynamic business environment and high per-capita income. It said these strengths are offset by high and rising government debt, a substantial interest burden and persistently large general government fiscal deficits. Fitch said the government has not taken meaningful action to tackle deficits and expects the deficit to widen to 7.4% of GDP in 2026 from 6.8% in 2025, driven by tax cuts and tariff rebates. It also warned that the debt-to-GDP ratio will keep rising, with higher borrowing costs adding pressure. Fitch flagged political gridlock and possible shutdown risk if elections produce divided government, while also noting challenges to institutional checks and balances. S&P Mini +0.02% to 7824, DXY -0.205% to 99.76, 10y UST +1.6bp to 4.659%.
The White House has released a trade report entitled “The Great Transshipment Scam,” warning that Chinese goods are being rerouted through middleman countries and labeling nearly all major U.S. trading partners as transshipment risks. The administration says the issue affects $40-75bn of imported goods a year and will be central to future tariff rollouts and reciprocal trade talks. Peter Navarro said the focus is on “40-plus countries” that are enabling transshipping, while U.S. Trade Representative Jamieson Greer said bad-faith exporters are undermining tariffs. The report calls for tougher Customs enforcement, including an AI-enabled “Detective Border,” and harsher penalties. It also signals that further unilateral tariffs could follow investigations into excess industrial capacity, including against China, the EU and 16 other partners.
The Trump administration has said it will impose new tariffs of up to 100% on drone imports and components, citing heavy U.S. reliance on foreign suppliers and national security concerns. A White House proclamation signed by the president sets a 100% tariff on certain larger or more sensitive drones, a 25% tariff on smaller drones, a 15% tariff on drones and components from the EU, Japan, Liechtenstein, South Korea, Switzerland and Taiwan, and a 10% tariff on drones from the U.K. Commerce Secretary Howard Lutnick found import penetration from foreign drone producers to be substantial, while domestic production is insufficient to meet security needs. The White House said the tariffs will take effect in 21 days, though some components and approved products face a 180-day delay. The move underscores Trump’s continued use of tariffs as a central trade and security policy tool.
Japan’s portfolio flow picture is turning more negative for JPY. Domestic investors are rebuilding foreign asset exposure just as foreign demand for Japanese assets is fading, reinforcing the underlying capital outflow pressure. Japanese demand for foreign assets accelerated sharply in the week ended August 7. Foreign bond purchases reached ¥1.63tn, the third-largest weekly inflow this year, while foreign equity purchases rose to ¥964bn in the biggest jump since early April. Despite the rally, Japanese investors remained net sellers of foreign bonds YTD at ¥1.21tn, while foreign equity investment has moved back above its long-term average. Foreign demand for Japanese assets remains weak. Overseas investors were net sellers of both JGBs and Japanese equities last week, extending the broader moderation in foreign inflows into Japan seen in recent months. Nikkei +0.59% to 68714, USDJPY +0.088% to 159.21, 10y JGB +0.8bp to 2.893%.
New Zealand’s Reserve Bank Financial Policy Committee has kept its loan-to-value ratio settings unchanged in its annual macroprudential review. The FPC said housing risks are currently contained, with national house prices broadly flat, mortgage lending growth modest and the share of higher-risk lending still manageable. It noted that existing borrowers are under some financial strain but that the banking system remains resilient. The current restrictions, in place since December last year, remain at 25% of new owner-occupier lending above an 80% LVR and 10% of lending to investors above a 70% LVR. Debt-to-income restrictions also remain in force as a safeguard against riskier lending. The committee will continue to monitor house prices, mortgage lending and broader financial stability risks, with the next review expected in about 12 months. NZX 50 +0.21% to 13854, NZDUSD +0.531% to 0.5875, 10y NZGB +3.5bp to 4.68%.
In his 2027 budget speech, President Prabowo Subianto said that Indonesia will target a smaller budget deficit of 2.4% of GDP in 2027, down from an expected 2.85% this year, while aiming for 6% economic growth in 2027. He stressed stricter fiscal discipline, tighter spending control across ministries and local governments, and an intensified anti-corruption drive. Prabowo also said greater state control over natural resources could support state revenues and urged state-owned enterprises to pay IDR 200tn in dividends this year, versus IDR 142tn in 2025. He framed the budget as a test of credibility, balancing growth ambitions against Indonesia’s 3% statutory deficit cap. JCI +1.19% to 6377, USDIDR +0.253% to 17825, 10y IDGB -3.9bp to 7.178%.
The Central Reserve Bank of Peru (BCRP) has held its policy rate at 4.25%. The BCRP’s forward guidance was unchanged, and it remains attentive to inflation, underlying inflation, expectations, activity and supply shocks and ready to adjust policy if necessary. Overall, the policy signal remains neutral/data-dependent, but the latest inflation and expectations readings provide a somewhat less comfortable backdrop. The August statement shows a less benign near-term inflation picture: headline inflation rose to 4.1% y/y and inflation excluding food and energy to 4.6%, while 12-month inflation expectations increased to 3.0%, the upper end of the target range. However, the BCRP continues to attribute the overshoot mainly to earlier supply shocks and expects inflation to return to the target range and converge toward 2% over the forecast horizon. Domestic activity remains constructive, with July leading indicators performing well and expectations indicators rising significantly, all remaining in optimistic territory. MSCI NUAM Peru General -1.21% to 58104, USDPEN -0.084% to 3.365, 10y PGB -2bp to 6.09%.
U.S. July retail sales advance are forecast to ease to 0.1% m/m vs. 0.2% m/m. Retail sales ex auto are forecast to rise to 0.2% m/m vs. -0.2% m/m, and retail sales ex auto and gas to ease to 0.3% m/m vs. 0.4% m/m.
U.S. August preliminary University of Michigan sentiment is forecast to ease to 54.9 vs. 55.2. The current conditions measure is forecast to ease to 54.9 vs. 54.8, with expectations forecast to ease to 55.2 vs. 55.4.
U.S. August preliminary University of Michigan 1-year and 5-10-year inflation expectations are forecast to hold at 4.2% and 3.3%, respectively.
U.S. June business inventories are forecast to ease to 0.1% m/m vs. 0.3% m/m.
Canada June manufacturing sales are forecast to fall to -0.1% m/m vs. 1.3% m/m.
Canada June wholesale sales ex petroleum are forecast to rise to 2.7% m/m vs. 0.0% m/m.
Mood: iFlow Mood fell back into risk-off territory, driven by inflows into fixed income.
FX: FX flows were mixed, with inflows into KRW while JPY and CZK saw substantial outflows.
FI: Fixed income flows were biased toward inflows globally. Argentine, U.K and Eurozone sovereigns saw inflows, while Polish bonds recorded outflows.
Equities: There were strong inflows into EM equities, with Polish, Malaysian, Taiwanese, Indian and South African equities all seeing inflows.
“Chance favors only the prepared mind.” – Louis Pasteur
“Success is where preparation and opportunity meet.” – Bobby Unser
German wholesale selling prices rose 5.3% y/y in July, up from 4.9% y/y in June and 5.9% y/y in May, while prices increased by 0.2% m/m. The gain was mainly driven by higher energy and raw material costs linked to the conflict in Iran and the Middle East. The biggest upward contributors were mineral oil products (+24.1% y/y; +4.0% m/m), non-ferrous ores, metals and semi-finished metal products (+27.8% y/y), chemical products (+13.1% y/y) and ICT devices (+9.0% y/y). Counteracting part of the rise, there were fall in prices of live animals (-18.5% y/y), milk products, eggs, edible fats and oils (-9.4% y/y) and meat and meat products (-6.1% y/y). DAX +0.64% to 26469, EURUSD +0.13% to 1.1551, 10y Bund +2.5bp to 3.156%.
French CPI rose by 0.6% m/m in July, after ‑0.3% in June. The seasonal increase in services prices (+1.6% vs. +0.5%) was driven by transport services (+10.9% after +0.5%) and accommodation services (+12.7% vs. +8.6%). Energy prices rebounded from the previous month’s decline (+2.3% vs. ‑4.2%), driven by prices of petroleum products (+2.3% vs. ‑7.0%) and gas (+6.6% vs. ‑2.7%). Conversely, the prices of manufactured products decreased compared with June (‑2.0% after ‑0.4%). Y/y, consumer prices rose by 2.1% vs. +1.8% in June and core inflation was +1.3% vs. +1% in June. CAC 40 -0.03% to 8648, EURUSD +0.13% to 1.1551, 10y OAT +3.4bp to 3.978%.
China’s financial statistics showed credit and lending growth deteriorating further in July. Outstanding aggregate social financing steadied at 7.4% y/y to ¥463.27tn, with government bonds (+14.1% y/y) and corporate bonds (+9.2% y/y) among the main drivers. Over the first seven months of the year, new aggregate financing totaled ¥22.25tn, down ¥1.74tn y/y, as government bond financing was scaled back. M2 money supply eased to 7.7% y/y from 8.0% y/y while M1 rose by 4.0% y/y and M0 by 11.6% y/y. Total deposits were up 8.1% y/y, with RMB deposits at ¥346.47tn. Financial institutions’ RMB loans eased from 5.24% y/y to 5.1% y/y to ¥282.29tn. CSI 300 +0.04% to 4666, USDCNY +0.03% to 6.7421, 10y CGB -1.1bp to 1.69%.
Australia’s June-quarter lending indicators showed new home loan commitments falling 5.4% q/q to 134,225, while the value of total new home loans was down 5.2% q/q to AU$97.6bn, after a 3.4% q/q decline in the previous quarter. The ABS said lending weakened across all borrower types and returned to around levels seen a year earlier. Investor loans drove the decline, dropping 8.6% q/q in the sharpest fall since Q3 2022, while owner-occupier loans fell 3.3% q/q. On a y/y basis, total lending was broadly flat, with value up 6.8% y/y, well below the March quarter’s 19.1% y/y pace. The ABS cited tighter lending conditions, including the RBA’s third cash rate rise in 2026, and federal budget changes to negative gearing and capital gains tax. ASX -0.17% to 5805, AUDUSD +0.241% to 0.7072, 10y ACGB +1.6bp to 5.007%.
New Zealand’s manufacturing sector expanded more slowly in July, with the BNZ-BusinessNZ Performance of Manufacturing Index easing to 54.3 points from 60.1 in June, still above the long-run average of 52.5. All sub-indices softened but remained in expansion: production led the way at 57.3, followed by deliveries at 55.8, new orders at 53.3, finished stocks at 53.2 and employment at 52.8. Commentary pointed to softer momentum after June’s exceptional reading, with sentiment turning more negative. Manufacturers cited the Middle East conflict, high fuel and raw material costs, freight pressures, weak customer spending and election-related uncertainty. However, some firms reported steady order books and stronger export sales. Overall, the report suggests continued expansion, but at a more moderate and cautious pace. NZX 50 +0.21% to 13854, NZDUSD +0.531% to 0.5875, 10y NZGB +3.5bp to 4.68%.
South Korea’s Financial Services Commission said household loans across all financial sectors rose by ₩620bn in July, from ₩830bn in June, as banks tightened mortgage and credit lending. Mortgage loan growth slowed to ₩350bn from ₩450bn in June, while other loans rose by ₩270bn, from ₩380bn previously. Bank household loans increased by ₩540bn, sharply below June’s ₩760bn, with banks’ own mortgage lending and policy loans both moderating. The commission said the slowdown likely reflects active voluntary risk management by financial institutions, despite the usual seasonal pickup in July. Secondary financial sector lending was broadly steady, while some mutual finance and savings institutions showed mixed trends. Chair Lee Eog-weon said the deceleration came even during the summer travel season, underscoring tighter lending discipline. KOSPI +2.42% to 6978, USDKRW +0.474% to 1414.55, 10y KTB +1.5bp to 4.3%.
South Korea’s export/import price and trade indexes for July showed firmer export prices and softer import prices in won terms. The export price index rose 1.0% m/m and 49.1% y/y, while the import price index fell for a second month, reflecting lower prices and a stronger won at -1.0% m/m but still increased by 18.7% y/y. On a USD basis, exports grew 20.0% y/y by volume and 64.2% y/y by value, while imports were up 14.7% y/y in volume terms and 25.8% y/y in value terms. The net barter terms of trade index improved by 24.7% y/y, reflecting stronger export prices relative to import prices. Manufacturing drove the export gains, while import prices softened across key categories, notably intermediate and capital goods.
Malaysia’s economy expanded by 6.0% y/y in Q2, up from 5.4% in Q1, while seasonally adjusted GDP rose 2.5% q/q after -0.03% in Q1. Growth was driven by services, manufacturing and construction, partly offset by a contraction in agriculture. On the expenditure side, private consumption and gross fixed capital formation supported activity, while government consumption strengthened. External demand also improved sharply, with exports and imports both recording double-digit growth. GDP at current prices was MYR 544.0bn, while constant-price GDP was MYR 445.9bn. Across H1, the economy grew by 5.7%, beating the 4.5% recorded in the same period of 2025. Bank Negara Malaysia is maintaining its 5% GDP and 1.5-2.5% CPI forecasts for 2026. KLCI -0.28% to 1730, USDMYR -0.008% to 4.0868, 10y MGB +0.7bp to 3.743%.
India’s WPI inflation eased marginally to 9.78% y/y in July, from 9.87% in June, while the headline index declined to 110.0 from 110.2. This was driven by fuel and power inflation, which slowed sharply to 20.05% from 27.41%, with its index falling to 105.4 from 111.1. However, underlying price pressures broadened elsewhere: primary articles inflation accelerated to 8.52% from 7.0%, while the rate for manufactured products rose to 8.29% from 7.48%. The WPI Food Index also accelerated to 6.65% from 6.14%. Key inflation drivers included mineral oils/petroleum products, food articles, basic metals, non-food articles, manufactured food products and chemicals. Overall, headline wholesale inflation edged lower, but the rise in food, primary and manufactured product inflation points to persistent and increasingly broad-based pipeline price pressures. SENSEX -0.3% to 77846, USDINR +0.015% to 95.4312, 10y INGB +0.2bp to 6.76%.
Taiwan has revised its real Q1 GDP growth up to 15.43% y/y from 14.55% and its estimated Q2 growth to 12.93% y/y, with seasonally adjusted annualized growth at 5.70% q/q. H1 GDP growth was 14.15%. It has also lifted its full-year GDP forecast for 2026 to 11.05% from 9.64%, implying stronger growth in H2 at 11.42% y/y in Q3 and 5.37% y/y in Q4. It projected 2027 GDP growth at 6.04%. Inflation is forecast at 2.07% in 2026 and 1.90% in 2027. For household income, 2025 average disposable income per household rose 3.9% to NT$$1.21mn, with the median up 3.4% to NT$1.018mn. Income inequality was little-changed. TAIEX -0.46% to 45811, USDTWD +0.478% to 32.015, 10y TGB +0.1bp to 1.92%.