Market Movers: Rethinking the Narrative
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Bob Savage
Time to Read: 7 minutes
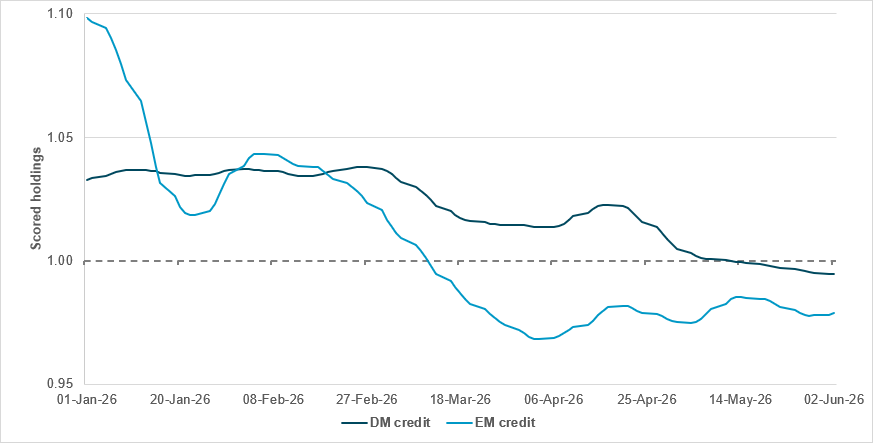
Corporate credit continues to struggle but below the radar
Source: BNY
Before the Iran conflict, one of the biggest sources of potential (rather than realized) risk aversion was in private credit. Questions over quality, the impact of AI on certain industries and the general effect of the end of easing cycles had started to impact sentiment. The onset of the conflict has generated more immediate concerns, but the structural factors which led to weak performance in credit in general have not gone away. If anything, they are likely to escalate again.
Over the past month, out of the close to 30 major credit markets we track, barely five were net bought, while some rather large outflows were seen in major economies. Comparing market segments, we find developed market credit holdings continuing to outperform their EM peers, but the gap is now relatively narrow compared with the beginning of Q2. However, rotation between the two markets is a secondary matter, as we can see both DM and EM corporate credit are now underheld relative to their one-year rolling averages. This is classic tightening cycle behavior, as flows rotate back into front-end instruments with higher risk-free rates. Despite the sales, overall holdings levels for both DM and EM credit were stable for most of May, indicating asset allocators believe the current level of risk premiums is already adequate to account for adjustments in policy expectations.
The narrative for June and ongoing equity outperformance is being rethought today, even as we remain stuck with oil and Iran as the headline news stories. The focus on an Israel/Lebanon ceasefire agreement helped to boost hopes that the U.S. and Iran will agree an MoU to open the Strait of Hormuz and discuss a peace deal. Oil is down 1% – its first drop in three days – while APAC shares have fallen back on tech profit-taking, with the rise in EMEA equity markets being led by consumer discretionary and software. U.S. futures are lower, despite oil and a slightly weaker USD, even with KRW at a 2009 low of 1540.55 and IDR at a new record low. Bond yields are mixed: higher in Asia and mostly lower elsewhere.
Bottom line: Investors are in the uncomfortable “return to stagflation” narrative, with oil inventories below their five-year average and skews pointing to higher prices despite the hopes of the moment. The economic data from the U.S. will be influential, and today’s disappointing Challenger job cuts clash with ISM numbers that beat expectations along with the Beige Book yesterday, which supported both higher growth and inflation risks. Jobs tomorrow will matter accordingly. The May Challenger report showed a 3.4% y/y jump in job losses to 97,006 – the worst May showing 2020. Whether this will temper the hawkish-leaning commentary from Fed speakers will be something to watch today, as will the reaction to front-end rates, with 2y yields still solidly over 4%. The mismatch between previous correlations and the resurrection of old ones – like gold/oil – should bring liquidity and safe haven concerns back as a key area of focus.
RBA Governor Michele Bullock has testified on the economic outlook, saying the board has raised the cash rate by 75bp this year to help bring inflation back to target. She said inflation had fallen into the target band in early 2025 but then rose again in the second half of the year as stronger growth, tight labor market conditions and higher oil prices pushed costs higher. She also warned that the Middle East conflict could add to inflation and modestly weigh on growth, while noting tighter policy is already easing housing market conditions. Bullock said headline inflation may peak above 4.5% in the June quarter, with underlying inflation above target until mid-2027. ASX -0.04% to 5558, AUDUSD +0.057% to 0.7133, 10y ACGB +0.6bp to 4.918%.
BoJ officials are reportedly leaning toward a 25bp rate hike to 1.0% at the June policy meeting, with policymakers also seeing room for further increases later in 2026. The discussion reflects concerns over persistent upside inflation risks linked to higher energy prices and yen weakness. Governor Kazuo Ueda recently signaled a higher likelihood of tightening if inflation risks outweigh growth concerns. Separately, the BoJ is expected to consider slowing the pace of bond purchase reductions from next fiscal year, as officials judge that government bond market functioning has improved and balance sheet shrinkage will continue even with a more gradual tapering approach. Nikkei -1.36% to 67471, USDJPY -0.107% to 159.9, 10y JGB +3.1bp to 2.67%.
The U.S. House of Representatives yesterday passed a largely symbolic war powers resolution on Iran by 215-208, rebuking President Trump’s handling of the conflict. The Democrat-led measure, introduced by Rep. Gregory Meeks, would direct Trump to remove U.S. armed forces from hostilities with Iran unless Congress authorizes military action. It does not itself end the war, but signals congressional disapproval. Four Republicans joined all Democrats in supporting the motion. Republican leaders, including Speaker Mike Johnson and Foreign Affairs Chair Brian Mast, argued the vote would weaken Trump’s leverage as his administration pursues a nuclear deal with Iran. The vote also gives momentum to a similar Senate war powers resolution, which has already advanced but has not yet had a final vote. S&P Mini -0.21% to 7556, DXY -0.09% to 99.44, 10y UST -1.8bp to 4.477%.
The OECD has warned that the Middle East conflict has become the main driver of the global outlook, with energy and input prices surging since February, lifting inflation while weighing on real incomes and growth. It cut its projected global GDP growth for 2026 to 2.8% from 3.4%, while leaving 2027 unchanged at 3.1%. Its outlook presents two scenarios: a time-limited disruption, where growth slows modestly before recovering, and a prolonged disruption, where higher energy prices, supply shortages, tighter financial conditions and weaker confidence would depress activity further. Inflation could rise by around 0.4 percentage points in 2026 and 1.3 percentage points in 2027 under the prolonged scenario. The OECD is urging central banks to remain vigilant where temporarily higher headline inflation resulting from the energy price shock can be looked through provided longer-term inflation expectations remain well-anchored, and says governments should keep energy relief temporary, targeted and well-designed. Brent -1.064% to 96.77, WTI -1% to 95.06, Omani crude +4.927% to 96.49, Dubai crude +1.748% to 95.547.
South Korea’s ruling Democratic Party (DP) is poised for a sweeping victory in the June 3 local elections, winning most metropolitan and provincial races and extending control across the country. Meanwhile the People Power Party (PPP) remains largely confined to its southeastern strongholds. The DP has secured 12 out of 16 key regional posts, including Busan, Incheon, Daejeon, Ulsan, Sejong, Gyeonggi, Gangwon, both Jeolla provinces and Jeju, reversing its poor showing in the 2022 local elections. The PPP has held onto Daegu and North Gyeongsang, and was leading narrowly in South Gyeongsang. In Seoul, the PPP’s Oh Se-hoon edged ahead amid ballot shortage controversies. In by-elections, the DP won nine out of 14 National Assembly seats, while the PPP took four and an independent one. The results reinforce the DP’s political dominance after its 2025 presidential win. KOSPI -1.84% to 8639, USDKRW +1.08% to 1535.35, 10y KTB -4.3bp to 4.136%.
U.S. Q1 final non-farm productivity forecast to ease to 0.4% q/q vs. 0.8% q/q, with unit labor costs expected to rise to 2.4% q/q vs. 2.3% q/q.
U.S. weekly initial jobless claims are expected be steady at 215k.
Central bank speakers: The Fed’s Tom Barkin gives a fireside chat, the Fed’s Mary Daly speaks at the Bloomberg Technology Summit, BoE Governor Andrew Bailey speaks at the Investment Association.
U.S. Treasury sells $75bn in 4-week bills and $75bn in 8-week bills.
Mood: iFlow Mood has stabilized in risk-off territory at -0.337, reflecting continued selling of global equities alongside persistent demand for core government bonds.
FX: Flows were dominated by heavy outflows from BRL, CAD and NZD, while CHF, MXN and SEK attracted the strongest inflows. Among the majors, USD, EUR, GBP and JPY were bought, whereas CNY and AUD saw net selling.
Fixed income: Demand for government bonds remained broad-based, led by China, Mexico, Chile, Canada and the Eurozone. U.K. gilts and U.S. Treasurys also attracted modest inflows, while Indonesian government bonds recorded the largest outflows.
Equities: Heavy selling persisted across EMEA, LatAm and most APAC markets, except for China and Thailand. Within G10, flows were mixed, with outflows from Europe, the U.K. and Japan offset by inflows into U.S. and Australian equities.
“The stories we tell literally make the world. If you want to change the world, you need to change your story.” – Michael Margolis
“The visionary starts with a clean sheet of paper and re-imagines the world.” – Malcom Gladwell
The U.S. Challenger report for May showed job cuts rising to 97,006, up 16% from April in the highest May total since 2020. The increase marked a third straight monthly gain and lifted YTD cuts to 397,755, roughly flat vs. 2024 after adjusting for last year’s federal workforce distortion. Technology led with 38,242 cuts, its highest monthly total since August 2024, while AI was cited as the top reason for layoffs for a third month running, reaching a record 38,579 cuts and accounting for 40% of May totals. Hiring plans remained historically subdued, with 80,472 announced in the first five months of 2026. S&P Mini -0.21% to 7556, DXY -0.09% to 99.44, 10y UST -1.8bp to 4.477%.
Euro area retail trade fell 0.4% m/m in April, while EU retail trade declined by 0.5%, reversing March gains of 0.8% and 1.1%, respectively. On a y/y basis, retail sales volumes still rose, up 1.0% in the euro area and 0.9% in the EU, though growth slowed from March. M/m weakness was driven by lower non-food sales and reduced automotive fuel purchases, partly offset by higher food, drink and tobacco sales. Among member states, Denmark, Romania, Belgium and Slovakia posted the sharpest m/m declines, while Lithuania, Malta and France recorded increases. Euro Stoxx 50 +0.38% to 6077, EURUSD +0.026% to 1.16, BBG AGG Euro Government High Grade EUR -2.5bp to 3.245%.
Eurozone construction activity remained in contraction in May, although the downturn softened, with the S&P Global Construction PMI Total Activity Index rising to 43.7 points from 41.7 in April. New orders still fell sharply, but the pace of decline moderated, while firms continued to cut employment and purchasing but at a slower rate. The survey showed broad-based weakness across housing, commercial and civil engineering, with France weakest and Italy closest to stabilization. Input costs remained elevated, though inflation eased vs. April, and supplier delivery times worsened at the fastest pace since December 2022. The outlook is still pessimistic, but less so than in April.
Spain’s industrial production rose 2.0% in April (seasonally and calendar-adjusted), while the unadjusted index increased by 4.2%. On a m/m basis, industrial output fell 0.4% after seasonal adjustment, a sharper decline than in March. By sector, capital goods posted the strongest y/y gain at 3.6%, while durable consumer goods remained the weakest at -6.6%. Output rose y/y in 14 regions and fell in three, led by Murcia, Castilla-La Mancha and Andalusia, while Extremadura, the Balearic Islands and Asturias lagged. The INE also revised recent data and noted the future adoption of CNAE 2025. IBEX 35 +0.4% to 18285, EURUSD +0.078% to 1.1606, 10y Bono -1.8bp to 3.443%.
Spain’s inventory stocks in the trade sector rose by 3.9% y/y in Q1, up 0.8 percentage points vs. Q4 2025. All sectors posted positive annual rates, with motor vehicle and motorcycle sales and repair showing the strongest increase at 11.9%, followed by wholesale trade at 2.7% and retail trade at 1.0%. Within the quarter, the y/y change came in at 3.9% in January, eased to 3.5% in February and then accelerated to 4.1% in March – the highest monthly reading of the period. The INE also said it had revised the last five months of ECSE trade series data.
Spanish mortgage foreclosure certifications initiated and registered in Q1 rose 20.1% y/y to 6,602. Foreclosures on dwellings owned by individuals jumped 35.8%, while those on primary residences climbed 38.1%. Urban properties accounted for most cases, at 6,275 filings, and total housing cases reached 4,607, up 34.5%. Used homes dominated at 89.5%, though new homes showed the fastest growth, jumping 98.0% y/y. Andalusia, Catalonia and Valencia recorded the highest numbers, while La Rioja, Navarra and Cantabria had the fewest cases.
U.K. construction output fell at the fastest pace in six years this May, with the S&P Global Construction PMI dropping to 38.2 points from 39.7 in April, its 17th month below the neutral 50-point level. The decline was broad-based, led by residential work, while commercial activity also weakened and civil engineering fell again. New orders contracted at the fastest rate in six years as clients delayed projects amid elevated borrowing costs, rising inflation and uncertainty. Employment and purchasing also declined. Input price inflation accelerated to its fastest pace since June 2022, driven by energy, fuel, transport and shipping delays, while business confidence eased further. FTSE 100 -0.04% to 10328, GBPUSD +0.023% to 1.3421, 10y gilt -2.8bp to 4.903%.
Swiss consumer prices for May 2026 rose 0.2% m/m and 0.6% y/y. The CPI reached 101.3, while core inflation increased by 0.1% m/m and 0.3% y/y. The m/m gain was driven mainly by higher housing rents, hotel prices, fruiting vegetables, petrol, and car rental and car sharing. In contrast, air transport and heating oil prices declined. Domestic goods rose 0.2% on the month, while imported goods fell 0.1%. The HICP climbed 0.1% m/m and 0.9% y/y, indicating modest inflationary pressure overall. SMI +0.25% to 13252, EURCHF +0.009% to 0.91874, 10y Swiss GB -0.4bp to 0.424%.
Swiss unemployment came in at 3.0% in May, with the unemployment count falling by 2,627 m/m to 140,275, though this was still 12,331 higher than a year earlier. Seasonally adjusted unemployment rose by 2,583 to 144,652, lifting the adjusted jobless rate to 3.1%. Youth unemployment fell modestly m/m, while unemployment among older workers also eased, both remaining at 2.7%. The number of jobseekers fell to 225,475, but open vacancies decreased m/m to 44,717 despite remaining above year-earlier levels. There was also a fall in short-time working, with 12,066 people affected in February, down 9.9% from January.
Swedish inflation for May 2026 came in at 0.8% y/y on preliminary CPI data, up sharply from April’s -0.1%. The CPI rose 1.0% m/m, while the CPIF inflation rate increased to 1.5% from 0.8% and CPIF XE moved up to 0.5% from 0.0%. Statistics Sweden said the higher reading was mainly driven by rising energy and services prices. The regular May inflation release is scheduled for June 11. The data indicate a clear pickup in price pressures after the softer April outcome, although the preliminary nature of the figures means the final print may differ. OMX +0.39% to 3147, EURSEK -0.208% to 10.8896, 10y Swedish GB +1.7bp to 2.895%.
Hungarian retail sales rose 3.6% y/y in calendar-adjusted terms in April and were down 1.2% m/m on a seasonally adjusted, calendar-adjusted basis. On a raw basis, retail trade increased by 1.7%. Growth was driven by automotive fuel sales (+9.1%), non-food retailing (+2.6%) and food shops (+3.4%). Internet and mail order sales rose 2.7%. Domestic retail turnover reached HUF 1.742tn at current prices, with food shops accounting for 48% of sales. In January to April, retail volumes were 4.8% above a year earlier. Budapest SI +0.24% to 135048, EURHUF -0.248% to 355.18, 10y HGB +12bp to 5.47%.
Czechia’s flash CPI inflation for May came in at 2.1% y/y. Prices rose by 0.1% from April, in only a modest m/m increase. The release indicates that inflation remained relatively contained in May, with the annual rate just above the 2% threshold. This is a preliminary estimate, and the final inflation reading is scheduled for June 10, 2026. The data point will be closely watched for signs of how domestic price pressures are evolving and whether the recent inflation trend is stabilizing or embarking on another upward turn. Prague SE -0.63% to 2511, EURCZK +0.067% to 24.224, 10y CZGB -2.9bp to 4.804%.
Czech Q1 data showed a tighter labor market, with employment broadly stable but unemployment rising. Total employment increased by 1.1% y/y to 5.284 million, while the employment rate for those aged 15-64 held at 75.5%. Unemployment climbed to 3.2% from 2.6%, and long-term unemployment also increased. The average gross monthly wage rose to CZK 50,282, up 8.1% in nominal terms and 6.4% in real terms, supported by inflation of 1.6%. Growth was strongest in construction, accommodation and professional services, while manufacturing and some trade sectors were weaker. Regional wage growth varied, but Prague still had the highest pay level.
Türkiye recorded softer labor market conditions in April, with the seasonally adjusted unemployment rate edging up to 8.2% from 8.1% even as the number of unemployed people fell by 5k to 2.868 million. Employment dropped by 356k to 32.166 million, pulling the employment rate down to 48.1%, while the labor force shrank by 361k to 35.034 million and participation eased to 52.4%. Youth unemployment dropped to 14.5%, and average weekly actual working hours rose slightly to 42.1. The composite labor underutilization rate improved to 30.1%, down 1.2 percentage points from the previous month. BI 100 +1.21% to 14135, USDTRY +0.027% to 45.975, 10y TGB -13bp to 34.69%.
Australia saw a sharp improvement in the international trade in goods balance in April – it came in at a surplus of AU$1.791bn from a March deficit of AU$1.024bn. Exports increased by AU$318.0bn, or 7.2% m/m, driven by higher general merchandise shipments, especially of non-rural goods, while non-monetary gold fell. Imports rose only AU$365mn, or 0.8% m/m, led by intermediate and other merchandise goods, partly offset by lower capital goods and consumption goods. The release noted stronger export quantities in iron ore, hard coking coal and thermal coal, while LNG volumes declined. On the import side, crude petroleum quantities fell sharply m/m, despite a strong y/y increase, alongside weaker gasoline volumes. Overall, the data point to firmer export momentum and only modest import growth. ASX -0.04% to 5558, AUDUSD +0.057% to 0.7133, 10y ACGB +0.6bp to 4.918%.
New Zealand’s housing market trod water in May, with the Cotality NZ Home Value Index showing the median national property value flat m/m at NZ$808,187, after slipping 0.1% q/q and 0.6% y/y. Values remain 17.0% below the early-2022 peak, underscoring a subdued market. Among major centers, Christchurch led gains at 0.4% m/m, while Dunedin and Tauranga rose 0.2% each and Hamilton edged up 0.1%; Auckland fell 0.2% and Wellington dropped 0.3%. Cotality said buyers and sellers remained cautious, leaving the market “in neutral,” while softer confidence, weaker retail spending and higher interest rates were cited as headwinds. The outlook remains fragile, with further modest decreases possible in the coming months. NZX 50 -0.1% to 13102, NZDUSD +0.12% to 0.5868, 10y NZGB -0.7bp to 4.551%.
New Zealand’s value of building work put in place fell in Q1, with the seasonally adjusted total building volume down 3.5% q/q, after a revised 0.6% q/q decline in Q4 2025. The residential volume fell 2.2% q/q following a 1.1% q/q rise previously, while the non-residential volume dropped 4.0% q/q after a 5.3% q/q fall. In value terms, total building work was NZ$7.2bn, down 5.9% y/y from the March 2025 quarter. Residential work fell 2.5% y/y to NZ$4.6bn, and non-residential work was down 11% y/y to NZ$2.6bn. By region, activity was weakest in Wellington and Waikato, while the rest of the South Island edged higher.
New Zealand’s ANZ World Commodity Price Index rose 0.7% m/m in May as all commodity groups posted modest gains. Dairy prices increased by 0.1% m/m, with higher milk powder prices offsetting lower butter prices; over the year, skim milk powder rose 25.8% y/y while butter fell 29.2% y/y. Meat and fiber rose 0.4% m/m, led by wool, which surged 14.0% m/m and was up 75.3% y/y, the biggest jump since October 2011. Horticulture climbed 3.4% m/m, and forestry gained 0.6% m/m. Aluminum rose 1.8% m/m and 49.1% y/y amid the Middle East supply disruptions. The NZD Commodity Price Index fell 0.3% m/m due to a slightly stronger New Zealand dollar.
The S&P Global Singapore PMI fell to 56.7 points in May from 57.9 in April, indicating a still-strong expansion in business conditions. Growth in output and new orders remained robust, with the latter still the second-strongest on record. Firms lifted purchasing activity at a record pace to support demand, while inventories also rose sharply. However, input cost inflation intensified to a record high, driven by higher vendor prices, fuel and transportation costs, and a record rise in wages. Despite these pressures, companies continued to pass some costs on to customers, though output charge inflation eased to a four-month low. Confidence for the next 12 months remained positive but softened vs. April, alongside a second straight decline in employment as firms cut temporary and part-time staff. STI -0.89% to 5093, USDSGD +0.055% to 1.2841, 10y SGB +3.5bp to 2.052%.