Market Movers: Resilience
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoff Yu
Time to Read: 5 minutes
Gold and U.S. corporate bonds benefit from inflation fear
Source: BNY
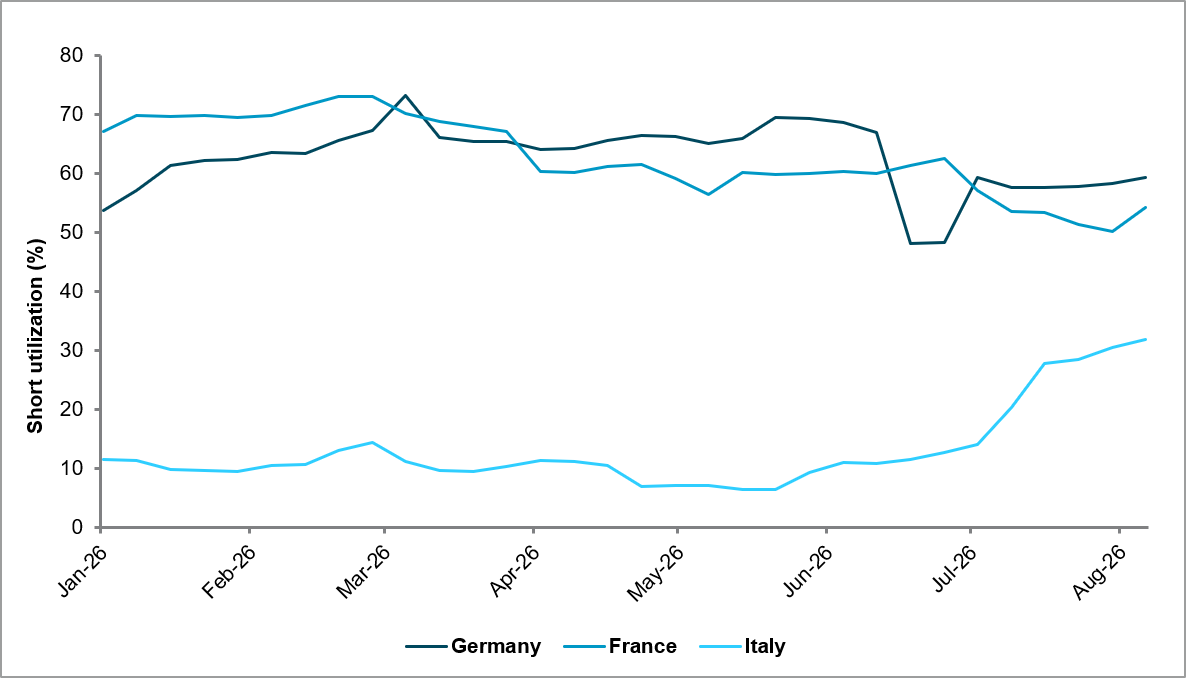
Eurozone short utilization suggests markets are only beginning to adjust to renewed inflation and steepening risk. After falling sharply through much of June and July, aggregate Eurozone short utilization has rebounded in August, but remains near the lower end of its recent range. That leaves the region relatively under-protected if global bond yields continue to rise, particularly given that the ECB remains the most hawkish major central bank.
Germany looks the most exposed. Bund auction yields are already at multi-decade highs, yet short utilization has reacted far less than elsewhere. The recent 5 percentage point (pp) increase only reverses around one-third of the decline since early July. Germany’s stronger fiscal position, lower relative inflation risk and firmer euro provide some insulation, but the low starting point means Bunds remain the clearest channel for further adjustment if global duration continues to reprice.
France is better protected. OAT short utilization fell sharply in late June but has since recovered around half of that decline. Absolute short utilization is already structurally high because of persistent fiscal concerns, so the hurdle for adding further protection is higher. This makes France a less obvious expression of incremental steepening risk than Germany.
Italy appears best prepared. BTP short utilization has risen steadily since mid-July, from mid-single digits to around 32%. That suggests investors have already built substantial protection against stagflation and supply risks. With Italy comparatively well hedged and France already carrying high structural shorts, the burden of further Eurozone adjustment increasingly falls on Germany.
Bond pressure: Bond markets remain the main source of tension, but risk assets are showing more resilience. Long-end yields have eased from Tuesday’s extremes, offering some relief after the global duration selloff amid limited fresh catalysts. Higher borrowing costs remain the clearest transmission channel from fiscal and inflation concerns into broader financial conditions, even as central banks appear reluctant to lean further against them.
Tech stabilizes: Asia still struggled, with the KOSPI down 5.8% and semiconductor weakness spreading across the region. But SK Hynix’s announcement of a major share buyback has helped steady sentiment after the close. The message is mixed: investors remain willing to cut crowded AI exposure, but balance sheets are increasingly being deployed to support valuations and shareholder returns.
Inflation contained: European inflation has not delivered a fresh upside shock. U.K. headline CPI rose to 2.9% in July, matching expectations, while underlying measures remained more stable. Euro-area inflation also remains elevated rather than disorderly. Inflation is still too high for comfort, but manageable enough to avoid forcing an immediate policy response. Even supply shock-prone South Africa delivered a downside inflation surprise, validating the South African Reserve Bank’s surprise hold last month.
Risk absorbed: The Gulf remains an uncomfortable backdrop. Brent is holding above $92/bbl as U.S.–Iran tensions persist and Strait of Hormuz traffic remains impaired, but alternative routes and logistical workarounds are limiting the immediate supply shock. Markets are therefore absorbing geopolitical risk rather than ignoring it.
Ahead today: FOMC minutes are the key event, but they are unlikely to settle the bond debate. With Chair Kevin Warsh deliberately limiting forward guidance, markets will continue looking to incoming inflation, labor and fiscal data for direction. Resilience is returning after several difficult sessions, but it’s not complacency. Bond yields, technology positioning and Gulf supply risks still warrant vigilance.
ECB President Christine Lagarde said Europe's post-war growth model is eroding as global trade fragments, cheap energy disappears and geopolitical risk reshapes investment decisions. She argued that the euro area’s resilience increasingly depends on domestic demand, which drove all of last year's 1.5% growth and contributed positively to Q2 2026 expansion of 0.4% q/q. The policy challenge is to turn that resilience into higher long-run productivity by deepening the Single Market and integrating capital markets. Lagarde highlighted AI as a key test, noting euro area firms expect around 9% of investment to go into AI this year, but fragmented regulation and financing still prevent firms from scaling. Her message was that Europe must convert market size into scale, investment and productivity. Euro Stoxx 50 +0.02% to 6,470, EURUSD +0.173% to 1.1596, BBG AGG Euro Government High Grade EUR +4.4bp to 3.5%.
President Donald Trump paused the scheduled 50% tariffs on certain Canadian imports for three days after holding trade talks with Canadian Prime Minister Mark Carney, saying the two countries “have a deal,” subject to final documents. The tariffs, announced last month, were due to hit roughly $20bn of Canadian goods, including hockey sticks, wine and other consumer-oriented products. They were imposed under Section 338 of the Tariff Act of 1930 in response to what Washington called Canadian trade discrimination in motor vehicles, alcohol and dairy. The move came amid broader U.S.–Canada trade tensions, with Trump already imposing tariffs on metals, lumber and auto parts. The article does not provide any official Canadian response or further details on the terms of the reported deal. S&P/TSX 60 Index Future +0.19% to 2,148, USDCAD -0.159% to 1.3876, 10y CGB -2.3bp to 3.697%.
The Reserve Bank of Australia (RBA) is still concerned about the inflation outlook, and Deputy Governor Andrew Hauser said further rate increases cannot yet be ruled out. He said inflation remains too high, with pressures coming both from external shocks, including possible renewed Middle East-driven fuel cost spikes and domestic factors such as excessive pressure on capacity, weak productivity, and limited capacity growth. Hauser said the RBA remains worried about upside inflation risks even after leaving the cash rate unchanged at its meeting last week. He added that if those risks materialize and inflation doesn’t keep falling, the RBA will raise rates again. The comments reinforce the central bank’s hawkish bias despite recent policy restraint and suggest officials remain alert to both global and domestic inflation risks. ASX -0.01% to 5,786, AUDUSD -0.24% to 0.7071, 10y ACGB -4.1bp to 5.057%.
Bank Indonesia (BI) kept its benchmark policy rate unchanged at 5.75% for a second straight month in its first decision under Acting Governor Destry Damayanti. The central bank said the hold is aimed at supporting rupiah stability, containing imported inflation, and preserving sustainable growth amid heightened global volatility and Middle East tensions. BI expects the rupiah to continue strengthening and will use monetary tools, market intervention, and foreign inflow incentives to support the currency. It also signaled continued macroprudential support to maintain liquidity and lending. BI left its 2026 growth forecast unchanged at 4.9%–5.7% and reiterated coordination with the government. The decision signals policy continuity after Perry Warjiyo’s exit, with no abrupt shift toward easing. JCI -0.64% to 6,409, USDIDR -0.135% to 17,833, 10y IDGB -4.4bp to 7.119%.
FOMC Meeting Minutes
U.S. Treasury sells 17-week bills and $16bn of 20y bonds.
Mood: iFlow Mood remained negative at -0.118, as demand for core sovereign bonds outpaced buying of global equities.
FX: Global currencies were broadly sold, with selective buying in LatAm currencies and EUR. USD, JPY, GBP and CNY recorded outflows.
FI: Government bond demand was led by Eurozone sovereigns and U.K. gilts, with moderate inflows across most of the iFlow universe. Norway, Peru, Poland and China saw notable outflows.
Equities: There was solid demand for G10 and EM APAC equities, led by the U.S. and Taiwan, alongside buying in Poland and Turkey. LatAm flows were mixed, while Hungary, Peru, Indonesia and Singapore recorded outflows.
“You may encounter many defeats, but you must not be defeated.” – Maya Angelou
“Sometimes life’s going to hit you in the head with a brick. Don’t lose faith.” – Steve Jobs
Euro area inflation for July rose to 2.9% y/y from 2.8% in June, while prices increased 0.2% m/m. The increase was driven primarily by energy, where inflation accelerated to 10.3% from 8.5%, and services, which rose to 3.3% from 3.2%. Core inflation excluding energy, food, alcohol and tobacco also edged higher to 2.5% from 2.4%, indicating some persistence in underlying pressures. By contrast, food, alcohol and tobacco inflation slowed to 1.2% from 1.5%. Services remained the largest contributor to headline inflation at 1.55pp, followed by energy at 0.94pp. Across the EU, inflation remained uneven, ranging from 0.3% in Sweden to 8.2% in Romania. Euro Stoxx 50 +0.02% to 6,470, EURUSD +0.173% to 1.1596, BBG AGG Euro Government High Grade EUR +4.4bp to 3.5%.
U.K. inflation for July 2026 came in firmer, with CPIH rising 3.1% y/y from 2.8% in June and CPI increasing 2.9% from 2.6% previously. On a monthly basis, both measures rose 0.3%, compared with little change in July 2025 for CPIH and 0.1% for CPI. The increase was driven mainly by housing and household services and furniture, while transport partially offset the rise. Core CPIH picked up to 2.9%, helped by stronger goods inflation, while core CPI was unchanged at 2.6% as goods inflation rose, but services inflation eased slightly. FTSE 100 +0.03% to 10,731, GBPUSD +0.17% to 1.3555, 10y gilt -3.2bp to 5.048%.
South Africa’s CPI for July slowed to 4.3% y/y from 5.0% in June, while prices rose 0.2% m/m. Goods inflation eased sharply to 3.4% from 4.8%, while services inflation moderated to 5.0% from 5.2%. Underlying pressures were firmer, with CPI excluding food, nonalcoholic beverages, fuel and energy at 4.2% y/y, while trimmed mean inflation was lower at 3.1%. The main annual contributors were housing and utilities, up 5.2% and adding 1.3pp, transport, up 8.9% and adding 1.2pp, and insurance and financial services, up 5.7%. Monthly inflation was restrained by transport, which fell 2.7%, including a 7.8% decline in fuel prices. JSE TOP 40 +0.16% to 105,805, USDZAR -0.296% to 16.2129, 10y SAGB -2.1bp to 8.667%.
Japan machine orders for June 2026 rose 9.7% from the previous month for private-sector demand excluding ships and electric power, rebounding for the first time in two months. The Cabinet Office said the underlying assessment was left unchanged at showing a pickup in movement, as the increase followed a sharp 12.4% decline in May and did not yet confirm a firm trend. The three-month moving average also turned positive, up 1.5% m/m, suggesting some stabilization in business investment demand. Overall orders increased 11.3% in the April to June quarter, while the July to September outlook for the same private demand category pointed to a 3.8% decline. Nikkei -3.16% to 65,326, USDJPY -0.282% to 159.16, 10y JGB -5.8bp to 2.902%.
Australia’s Wage Price Index for the June quarter 2026 rose 0.8% q/q for a fifth straight quarter, lifting annual wage growth to 3.2% y/y, unchanged vs. Q1 but down slight from 3.4% y/y in Q2 2025. Private-sector wages increased 0.7% q/q and 3.1% y/y (3.2% in March quarter 2026), while public-sector wages rose 0.9% q/q and 3.4% y/y. The largest industry contributors to quarterly growth were public administration and safety and health care and social assistance, while information media and telecommunications posted the strongest quarterly rise at 1.2%. Wage growth was mainly driven by individual agreements, which accounted for 53% of quarterly growth. ASX -0.01% to 5,786, AUDUSD -0.24% to 0.7071, 10y ACGB -4.1bp to 5.057%.
New Zealand’s June 2026 quarter business price indexes showed broad price increases. Output PPI rose 1.6% q/q and input PPI increased 2.9% q/q. Farm expenses price index (FEPI) climbed 3.8% q/q and capital goods price index (CGPI) rose 1.8% q/q vs. the March 2026 quarter. The main drivers of output prices were electricity and gas supply, dairy product manufacturing, and road transport. On the input side, the largest contributions came from rail, water, air and other transport, electricity and gas supply, and road transport. NZX 50 +0.46% to 13,930, NZDUSD -0.069% to 0.5872, 10y NZGB -3.8bp to 4.705%.
South Korea’s Q2 2026 household credit data showed total household credits rising by ₩25.9tn to ₩2,019.8tn at end-June, up 1.3% from the previous quarter-end and the fastest pace since Q3 2021. Household loans increased by ₩24.9tn to ₩1,891.3tn, while merchandise credits rose by ₩0.9tn to ₩128.5tn. By lender type, commercial and specialized banks drove the gain, adding ₩13.3tn after a ₩0.2tn decline in Q1 2026. Non-bank depository corporations increased lending by ₩3.1tn, and other financial corporations by ₩8.6tn. Housing-related loans also expanded, with the main growth concentrated in banks and other financial institutions. Overall, the report points to stronger household borrowing momentum in Q2 versus Q1. KOSPI -5.8% to 6,471, USDKRW -1.177% to 1,394.25, 10y KTB +6.3bp to 4.373%.
South Korea’s state-run Korea Development Institute (KDI) raised its 2026 growth forecast to 3.2% from 2.5%, citing an AI-driven boom that is keeping global demand for semiconductors stronger than expected. The KDI said this is boosting exports and facility investment, with spillovers to private consumption likely to emerge in 2027. It also lifted its 2027 growth outlook to 2.2% from 1.7%. Export volumes are now seen rising 8.7% in 2026 and 5.0% in 2027. The institute said exports of computers, electronics and optical instruments are surging, and the current account is posting an unprecedented surplus. Key risks include a possible turn in the semiconductor cycle, weaker chip demand if AI investment cools, intensifying competition, U.S. tariff uncertainty, and Middle East geopolitical tensions.