Market Movers: Repricing
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Wee Khoon Chong
Time to Read: 4 minutes
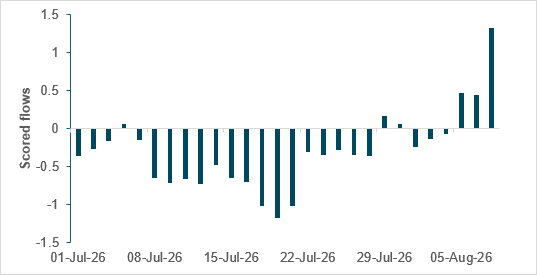
Flows into DM metals and mining industry
Source: BNY
After a month of sustained outflows from developed market equities in the metals and mining sector, scored flows over the past three days have shown sharp inflows into these assets. The flows have coincided with a swift runup in the prices of several precious metals: since last week, gold has gained nearly 8%, platinum almost 6% and silver more than 13%. Copper, meanwhile, is up just over 1.5%, leaving it short of its highs of the middle of last week.
The immediate causes of the gains in metal prices were positive developments in the Strait of Hormuz and the weak July non-farm payrolls (NFP) report. Optimism earlier in the week around a potential deal to reopen the Strait of Hormuz reduced energy-led inflation fears, which had served as a headwind for gold by keeping rate hike expectations elevated. Similarly, the weak July NFP announcement, which came in at -23k against a consensus of 80k, led markets to further scale back Fed hike expectations.
At country level, South Africa, which is often considered a proxy for global mining equity demand, has registered inflows into its equity markets every day since July 28. Over the past week, the South African rand and Australian dollar – both currencies associated with mining – have each appreciated against the U.S. dollar.
Oil has surged, but the stress remains contained: Market sensitivity to geopolitical tensions and higher oil prices is fading. Equities were mixed, with tech outperforming, while credit spreads and bond yields were broadly steady. USD edged higher.
AI boom has lifted Asian growth: Singapore has raised its 2026 GDP forecast sharply to 4.5-5.5% from 2.0-4.0%, citing stronger global AI investment. The trend is visible across Asia: South Korea’s exports rose 45.3% y/y in the first ten days of August, led by a 155.4% surge in chip exports. Seoul also announced a ₩5tn ($3.5bn) semiconductor fund targeting materials, components and fabless firms. Taiwan’s July chip sales hit a record TW$467bn ($14.5bn), up 44% y/y.
JPY remains an intervention/rates trade: Higher oil prices and U.S. Treasury yields remain headwinds for the energy-importing economy. USDJPY rose for a second day and broke through the 159 mark after touching 155.23 last week. Intervention risk may deter fresh JPY shorts, but persistent fiscal concerns leave little fundamental case for sustained yen appreciation.
Bottom line: Two trades are emerging beneath otherwise calm markets: AI-led Asian growth and renewed metals exposure. Flows are now confirming the precious metals rally, while semiconductor demand is feeding directly into regional exports and growth. Oil remains a headwind but is no longer the dominant cross-asset driver.
The RBA has left its cash rate target unchanged at 4.35%, commenting that policy rates remain somewhat restrictive but that further hikes are still possible if upside inflation risks materialize. The board said inflation rose materially in H2 2025 and remains too high, with trimmed mean inflation still elevated and little changed from the March quarter. It noted that some of the inflation pickup reflects capacity pressures, while higher global oil and fuel prices are feeding through to other goods and services. Financial conditions have tightened, consumer spending is slowing gradually, housing momentum has softened and labor market conditions have eased a little more than expected. The board highlighted heightened uncertainty from the Middle East conflict and said inflation is not expected to return to the midpoint of its target range until late 2027. The bank has lowered its OCR forecast and sees no further hikes until 2028. ASX -0.36% to 5855, AUDUSD -0.213% to 0.7052, 10y ACGB +4bp to 5.035%.
The White House has said it is extending the Jones Act waiver for 90 days, meaning foreign ships will continue to be allowed to move fuel and other industrial commodities between U.S. ports. The administration said the waiver has supported a “significant increase” in domestic deliveries of essential products such as gasoline, diesel and jet fuel. The move follows an initial suspension in March, which was introduced after the Iran bombardment and the closure of the Strait of Hormuz pushed up energy prices. Oil and gasoline prices have since eased from their April highs, but U.S. crude remains more than 20% above pre-war levels. The Jones Act waiver was due to expire on August 15 and has become a political flashpoint, weighing protection for the shipbuilding industry against higher costs for businesses and consumers. S&P Mini +0.01% to 7778, DXY +0.024% to 99.834, 10y UST +1.3bp to 4.719%.
U.S. July NFIB Small Business Optimism is forecast to ease to 97.5 points vs. 97.4.
U.S. ADP weekly employment change is due; last week’s reading was 15.0k.
U.S. July existing home sales are forecast to ease to 4.05 million vs. 4.09 million.
The New York Fed will release its quarterly Household Debt and Credit Report.
U.S. Treasury sells $95bn in 6-week bills and $58bn in 3y notes.
Mood: iFlow Mood has continued to improve on strong equity inflows and is now risk-neutral at -0.079.
FX: FX flows were mixed across the world. In the G10 space, GBP and EUR registered inflows while USD and JPY faced selling pressure. In EM, MXN led the world in inflows, while there were outflows from BRL.
FI: Fixed income flows were modest worldwide, although Norwegian sovereign bonds saw sizable outflows.
Equities: Global equities were generally well-bought, with substantial inflows into Taiwanese, Polish, Indian and South African equities.
“Price is what you pay. Value is what you get.” – Warren Buffett
“The four most dangerous words in investing are: ‘This time it’s different.’” – Sir John Templeton
Dutch exports rose 3.1% y/y in June, after a 4.8% increase in May. The gain was driven mainly by higher shipments of petroleum products, machinery and electronic products. Imports also increased, with goods imports up 1.4% y/y in June, supported by machinery, food, beverages and tobacco, and petroleum products. Statistics Netherlands also said export conditions were less unfavorable in August than in June, helped by a more favorable real exchange rate, less negative opinions among Dutch manufacturers on foreign orders, a smaller contraction in German manufacturing output and improved producer confidence in Germany and the Eurozone. The report points to still-positive export momentum, though the pace eased m/m. AEX +0.17% to 1113, EURUSD -0.174% to 1.1535, 10y NGB +2.1bp to 3.293%.
The Netherlands’ inflation for July rose to 3.2% y/y, up from 2.9% in June and above the 3.1% flash estimate. On a m/m basis, CPI increased by 1.6%. The acceleration was driven mainly by motor fuels and energy: motor fuels rose 22.0% y/y vs. 17.3% in June, while energy prices were 1.1% y/y higher after a 1.8% y/y decline previously. Higher import duties on consumer goods from outside the EU also lifted prices. Housing costs provided some offset, as rental property prices rose 4.3% y/y, slower than 4.7% in June. The HICP measure showed 3.0% y/y inflation, above June’s 2.5%. Inflation in the Netherlands remained above the euro area’s 2.9% y/y in July.
The U.K. British Retail Consortium Retail Sales Monitor showed total sales rising 1.3% y/y in July, slowing from 1.9% in June. Same-store sales increased by 1.0% y/y, down from 1.7% previously. Food sales outperformed, rising 3.8% y/y vs. 2.8% in June, while non-food sales fell 0.7% y/y after a 1.2% gain. Same-store food sales rose 3.2% y/y, while same-store non-food sales declined by 0.8% y/y. The BRC said the report measures actual retail value and does not adjust for prices, while same-store sales offer a cleaner spending gauge but tend to understate overall retail growth. FTSE 100 -0.35% to 10863, GBPUSD +0.023% to 1.3504, 10y gilt +6.8bp to 4.989%.
Turkish trade sales volume decreased by 4.5% y/y but rose 1.9% m/m in June. Within the sector, wholesale and retail trade and repair of motor vehicles and motorcycles fell 13.8% y/y and 5.7% m/m. Wholesale trade sales declined by 9.4% y/y but increased by 4.0% m/m. By contrast, retail trade sales grew by 11.8% y/y and 0.7% m/m. Overall, the data point to mixed trade conditions in June, with retail holding up while wholesale and vehicle-related activity weakened. BI 100 +0.23% to 13812, USDTRY -0.056% to 47.7393, 10y TGB 0bp to 34.79%.
Australia’s NAB business survey for July showed business conditions improving by 1 point m/m to 4 from 3 in June, while business confidence was unchanged at -6. Trading and profitability held steady, but employment improved to 3 from 1. Forward orders slipped to -3 from 0, and capital expenditure eased to 3 from 1. Capacity utilization rose to 83.0% from 82.1%. Cost and price pressures remained elevated: labor costs increased by 2.2% q/q, purchase costs by 2.3% q/q and final product prices by 1.1% q/q. Export conditions were flat, with exports at 0 and exporters’ sales at 0, suggesting no clear pickup in external demand. Overall, the survey points to modestly firmer operating conditions, but confidence remains weak and forward momentum limited. ASX -0.36% to 5855, AUDUSD -0.213% to 0.7052, 10y ACGB +4bp to 5.035%.
South Korean exports surged 45.3% y/y in the first ten days of August, driven by strong global demand for memory chips. Outbound shipments reached $21.3bn, the highest ever for this period, while imports rose 23.1% y/y to $19.5bn, leaving a trade surplus of $1.8bn. Chip exports jumped 155.4% to $9.95bn, supported by the AI boom, and accounted for 46.8% of total exports, up sharply from a year earlier. Petroleum product exports also rose 65.3% to $1.99bn, while automobile shipments fell 80.9% to $182mn. By destination, exports to China more than doubled to $6.7bn and shipments to Vietnam increased by 45.4% to $2.39bn, while U.S.-bound exports dipped 0.2% to $2bn. KOSPI +0.73% to 6346, USDKRW -0.008% to 1418.1, 10y KTB +2bp to 4.235%.
Singapore’s Ministry of Trade and Industry has upgraded its 2026 GDP growth forecast to 4.5-5.5% from 2.0-4.0%, citing a stronger-than-expected H1 performance and a brighter external outlook amid a global AI investment boom. Singapore’s economy grew 5.9% y/y in Q2, easing from 6.3% in Q1, while q/q growth picked up to 1.4% from 1.2%. Growth was led by manufacturing (12.5% y/y), wholesale trade (8.3% y/y) and finance and insurance (6.2% y/y), with AI-related demand supporting electronics, precision engineering and machinery-related activity. By contrast, food and beverage services contracted (-1.5% y/y), hurt by more outbound travel and lower visitor arrivals. The MTI said the outlook for AI-linked sectors has improved, while sectors exposed to Middle East supply disruptions, including chemicals and transport, remain under pressure. STI +0.53% to 5729, USDSGD -0.118% to 1.281, 10y SGB +2.8bp to 2.306%.