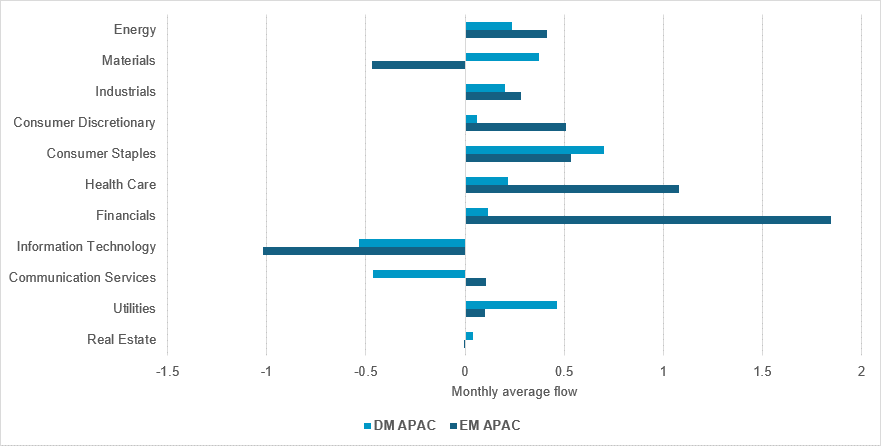Market Movers: Renewal
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 5 minutes
Rotation, not (yet) capitulation, in Asian tech
Source: BNY, GPIF
Tech pressure is becoming an APAC allocation shift, not a clean exit from technology. Information technology remains the weakest sector across both EM and DM APAC over the past month, but the latest flow signal shows the selling impulse losing force: weekly tech flows have recovered to nearly flat. That is significant because investors are no longer simply dumping the sector. They are redirecting marginal capital toward areas with cleaner near-term support, especially industrials, health care and utilities.
The key distinction is between flow and stock. New money is moving away from technology, but existing positioning has not been fully unwound. Global IT holdings still sit near the 56th percentile, and EM APAC IT exposure remains elevated, which means the legacy overweight remains a risk if sentiment weakens again. The sector picture also differs across the region. In DM APAC, consumer staples are leading, which is consistent with a more defensive allocation tilt.
In EM APAC, financials are seeing stronger inflows, likely linked to expectations of tighter policy and better rate sensitivity. The practical takeaway is clear: APAC tech should be treated as a fading leadership trade rather than a broken one. It may make sense to reduce exposure where positioning is crowded; however, it would be a mistake to assume investors have completed a full sector rotation until holdings fall further and non-tech inflows become more persistent.
Diplomatic channel: Renewal is the theme, but the tone is fragile rather than optimistic. After nine days of strikes, Iran is still signaling a military response, but it is also keeping diplomacy alive. Foreign Ministry spokesman Esmaeil Baghaei said Tehran has received proposals from mediators aimed at preventing a wider conflict and rejected the idea that Iran faces a binary choice between negotiations and war. The message is that diplomacy and defense can move together. For markets, that keeps the conflict in a managed but unstable phase. Oil is still up after the strikes, but the survival of a diplomatic track is helpful for risk sentiment at the margin.
U.K. reset: The U.K. provides the clearest political renewal story. Andy Burnham becomes prime minister today, with cabinet appointments now the immediate market test. His renewal agenda gives investors a framework, but credibility matters more than rhetoric. His choice of chancellor is central for U.K. assets: a reassuring name would support the narrative; a surprise appointment risks reviving fiscal sensitivity. Our flow data show no positive external reaction in gilts.
Risk repair: Markets are looking for renewed risk appetite after last week’s equity weakness, but the repair still needs validation. There is support coming from central banks, which are sounding a more cautious note on further hikes this week as inflation pressure eases. Earnings still need to confirm the growth story. Without corporate resilience or calmer rates, the equity unwind will extend rather than rotate.
Bottom line: Renewal is visible in diplomacy, U.K. politics and market sentiment, but it is not secure. Iranian mediation, Burnham’s cabinet and earnings need to validate the reset. Today’s U.S. calendar is light, leaving Canada CPI as the main North American release: a softer print would help the BoC stay on hold, while a firmer print would complicate the pause narrative. If the evidence disappoints, renewal will quickly become another false start.
Iran’s Foreign Ministry said it has received proposals from several mediators seeking to prevent the conflict from widening, while insisting that diplomacy and military defense remain complementary. Spokesman Esmaeil Baghaei said diplomatic efforts had remained active in recent days and that Iran would continue talks aimed at halting U.S. actions even as its armed forces responded militarily. He rejected the idea that Tehran faces a simple choice between negotiations and war, arguing that both diplomacy and defense serve the same national interest. The comments suggest Iran wants to preserve diplomatic channels while maintaining deterrence, with the foreign ministry and Revolutionary Guards presented as pursuing the same objective through parallel political and military tracks. Brent +0.284% to 88.35, WTI -0.255% to 82.28, Omani crude +6.344% to 80.97, Dubai crude +1.93% to 75.187.
Andy Burnham is set to become U.K. prime minister today after a rapid rise that began with his victory in a by-election and Sir Keir Starmer’s resignation. In his Downing Street remarks, Burnham is expected to promise concrete improvements in living standards, outline domestic priorities and project hope and unity. He faces immediate questions over cabinet appointments and policy direction, including who will serve as chancellor and how he will distinguish his administration. Key challenges include immigration, welfare, weak productivity, social care, relations with President Trump and support for Ukraine. He has signaled continuity with Labour manifesto pledges while also favoring devolution, regional investment, North Sea drilling and possible public control of Thames Water. FTSE 100 -0.32% to 10566, GBPUSD +0.112% to 1.3467, 10y gilt +2.1bp to 4.972%.
The RBI has intervened in foreign exchange markets to support the rupee after it slipped toward a record low, selling dollars both onshore and offshore as oil prices surged and pressured sentiment. The currency fell as 0.2% to 96.4575 per dollar, close to the all-time low of 96.965 reached in late May, while benchmark 10y government bond yields rose 4 basis points to 6.82%. Authorities have also tried to attract foreign currency inflows by easing rules for domestic bond investment and encouraging dollar deposits from non-resident Indians, but the recent measures have not fully offset stronger importer demand for dollars and higher crude driven external pressure. SENSEX -0.77% to 77553, USDINR -0.241% to 96.5137, 10y INGB +4.9bp to 6.829%.
China’s “national team” moved first to stabilize A-shares. China Reform Holdings said it had deployed more than ¥50bn via stock buyback and shareholding relending funds to buy stocks in central state-owned enterprises (SOEs), while China Chengtong said it had completed nearly ¥10bn of purchases and will keep adding to SOEs, tech stocks and ETFs. The moves, together with announced buybacks, share purchases and fund self-buying, signal continued official support for market stability. The authorities have also kept building the “stable market” mechanism since the tools were created in September 2024. Separately, the CSRC is expected to soon meet securities firms, fund managers and listed companies to gather views on promoting healthy and stable capital markets. The backdrop is a sharp A-share correction, especially in technology names. CSI 300 +0.13% to 4535, USDCNY +0.062% to 6.772, 10y CGB +0.1bp to 1.735%.
U.S. June leading index is forecast to fall to -0.1% m/m vs. 0.1% m/m.
Canada June CPI is forecast at -0.2% m/m, 3.0% y/y vs. 1.0% m/m, 3.2% y/y in May, CPI ex food and energy is forecast at 1.7% y/y vs. 1.6% y/y.
Canada June CPI core median and core trim are forecast to be unchanged at 2.1% y/y and 2.0% y/y, respectively.
U.S. Treasury sells $92bn in 13-week bills and $79bn in 26-week bills.
Mood: Dip buying has continued. iFlow Mood edged up to -0.132 but remained negative. Investors kept buying the recent equity correction while demand for core government bonds stayed firm, signaling resilient risk appetite rather than broad de-risking.
FX: USD and JPY remain in demand. Flows were mixed in G10 but remained biased toward outflows across the rest of the iFlow universe, led by APAC. USD, SEK and JPY attracted the strongest inflows, while EUR and GBP were lightly sold. EUR positioning slipped back into underheld territory, while JPY extended further into overheld territory.
Fixed income: Safety remains in favor. Investors continued adding to U.S. Treasurys, Eurozone sovereigns, JGBs and U.K. gilts while selling higher-beta sovereign debt, led by Hungary, Chile and Indonesia.
Equities: EM is still attracting capital. Investors sold G10 equities but continued buying APAC, EMEA and LatAm. India and Thailand led inflows, followed by China and Chile, while Canada, Hungary and Singapore recorded the largest outflows.
“Life starts all over again when it gets crisp in the fall.” – F. Scott Fitzgerald
“We step out from the old to the new.” – Jawaharlal Nehru
The latest U.K. Rightmove survey said asking prices for newly advertised homes fell 1.0% m/m in the four weeks to July 11, well below the 10-year July average of -0.2%. Prices were 0.4% y/y lower, after a 0.5% y/y drop in June. Rightmove blamed weak demand on the men’s World Cup and record temperatures distracting buyers, alongside still-elevated borrowing costs. The average two-year fixed mortgage rate eased to 4.92% from 5.07% in June, but remained above February’s 4.25%. Sales agreed in H1 were 6% below a year earlier, though broadly in line with H1 2024. Listings were down 1% y/y, but near a 12-year seasonal high. FTSE 100 -0.32% to 10566, GBPUSD +0.112% to 1.3467, 10y gilt +2.1bp to 4.972%.
Polish producer price inflation recorded a modest m/m dip and a firmer y/y increase in June. Prices of sold industrial production fell 0.2% vs. May, after increases had been recorded since February, while they rose 1.7% y/y. On a m/m basis, mining and quarrying saw a 1.7% drop and manufacturing edged down 0.1%, partly offset by a 0.4% rise in electricity, gas, steam and hot water supply. Compared with June 2025, mining, manufacturing, and water and waste management prices were up, while energy prices were down. WIG +0.74% to 142922, EURPLN -0.146% to 4.3355, 10y PGB +1.9bp to 5.586%.
Polish industrial output rose 7.6% y/y in June, after a 0.4% fall a year earlier, and increased by 2.0% m/m. In H1, industrial production was up 3.9% y/y. After seasonal adjustment, output was 5.5% higher than a year earlier and 0.1% above May. The strongest y/y gains were in intermediate goods (+11.9%), non-durable consumer goods (+7.4%) and capital goods (+7.3%), while durable consumer goods fell 1.2%. 26 out of 34 sectors recorded y/y growth, led by other transport equipment, paper and waste recovery, while tobacco, textiles and furniture declined.
New Zealand’s merchandise trade data for June showed a strong pick-up in both exports and imports, with goods exports rising 25% y/y to NZ$8.1bn (from June 2025) and goods imports up 28% y/y to NZ$8.1bn. The monthly trade balance was a slim surplus of NZ$23mn vs. a downwardly revised NZ$577mn. Export growth was led by dairy and food products, especially milk powder, butter and cheese, as well as preparations of cereals, flour, milk and starch, driven by infant formula. By destination, exports to China, the U.S. and Australia all rose sharply, with gains in meat, dairy, fruit and aluminum. Import growth was dominated by petroleum and petroleum products, particularly automotive diesel, jet fuel and motor spirit, alongside higher imports from China, the EU, Australia and South Korea, led by machinery, vehicles and fuel. NZX 50 +0.01% to 13696, NZDUSD +0.137% to 0.5851, 10y NZGB +5.4bp to 4.705%.
The BoK has warned that South Korea may face “Dutch Disease” as semiconductor-led growth becomes increasingly concentrated. In a report, it said the chip boom could draw human resources and investment away from other industries, weakening their industrial base. It highlighted the scale of the sector’s dominance, estimating that combined operating profit at Samsung Electronics and SK Hynix would rise sharply this year, far exceeding profits across other listed firms. The central bank urged financial authorities to remain conservative and prioritize stability when setting government spending plans, despite expectations of a near-term boost in corporate and dividend income tax revenues. The report frames the semiconductor surge as a broader macroeconomic risk, not just a sectoral success, and warns of potential distortions if growth remains overly dependent on a narrow industrial base. KOSPI -4.46% to 6516, USDKRW +0.504% to 1479.55, 10y KTB -3.2bp to 4.3%.
Malaysia’s external trade remained strong in June, with total trade rising 44.7% y/y to MYR 340.9bn. Exports jumped 45.4% y/y to MYR 177.9bn, driven by higher domestic exports and re-exports, while imports climbed 43.9% y/y to MYR 163.0bn. The trade surplus widened by 64.9% y/y to MYR 14.9bn. On a m/m basis, imports increased by 13.2% and total trade by 4.0%, but exports fell 3.2% and the surplus narrowed sharply. Over January-June, total trade expanded by 22.4% to MYR 1.8tn, supported by exports (+27.5%) and imports (+16.9%), while the surplus surged 159.8% to MYR 147.1bn. Imports by end-use rose across intermediate, capital and consumption goods. KLCI -0.33% to 1726, USDMYR +0.13% to 4.0915, 10y MGB +1bp to 3.647%.