Market Movers: Relevance
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 7 minutes
Sintra seasonality in play; Lagarde boost likely to be followed by a weak July
Source: BNY
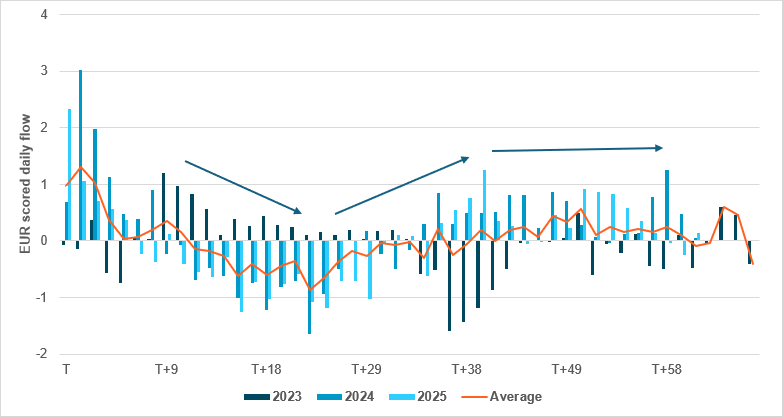
EUR has displayed a consistent post-Sintra seasonal pattern over the past three years. Relatively hawkish messaging from ECB President Christine Lagarde has typically triggered renewed EUR buying from late June into early July, before those gains faded as the initial policy repricing ran its course. While 2024 and 2025 also saw a late-August recovery in EUR flows, those episodes were supported by specific macro and political factors that appear less likely to recur this year.
In 2023, higher-for-longer rates supported bonds but wider rate differentials and increased FX hedging capped EUR gains. In 2024, gradual easing, French political uncertainty and weak Eurozone asset flows remained headwinds, but EUR recovered temporarily in August, likely driven by hedge unwinding rather than stronger underlying demand. In 2025, defense-led fiscal expansion, higher real yields and improving European sentiment underpinned both EUR and fixed income demand, while cross-border hedging remained contained.
EUR buying is expected to re-emerge over the next few weeks, providing an opportunity to position for near-term strength before flows fade through July. The probability of another late-summer rally is lower, as today’s macro backdrop resembles 2023 more than 2024 or 2025, with weaker fiscal support and tighter policy pressure from supply shocks. That favors Eurozone fixed income over equities and suggests any early-July EUR strength should be viewed as tactical rather than the start of a sustained breakout.
Sentiment this week – a short one because of the U.S. public holiday – has started on a firm footing as markets look ahead to U.S. labor market data, the ECB’s Sintra symposium and the U.S.’s 250th anniversary celebrations. A brief resumption of hostilities between the U.S. and Iran over the weekend barely registered, reflecting confidence that escalation would once again give way to accommodation before markets reopened. With energy markets continuing to normalize, attention is shifting from geopolitical risks to whether the recent dovish repricing in monetary policy can be sustained. That confidence may prove misplaced. While oil-driven inflation pressures have eased, a new wave of supply-side constraints linked to the global artificial intelligence investment cycle is beginning to emerge, raising the risk that inflation may prove more persistent than markets currently expect.
Regional rebalancing: The South Korean government is supporting efforts by the country’s leading memory and storage chip companies to invest up to ₩1.35qn in fabrication plants and data centers. The efforts are intended to strengthen the country’s leading position in the industry. However, the location of the plants also has a clear element of geographical “rebalancing” – something that is at the forefront of industrial policy globally, with decision-makers seeking to divert technology infrastructure investment into hitherto under-developed regions. The chip plants will be built in the southwest of the country, which is economically less developed than the Seoul region and the industrial southeast.
Backtracking: There are further signs that the ECB may be backtracking on its policy trajectory. Governing Council member Mārtiņš Kazāks has stated that there is currently “no need” for multiple ECB hikes in a “rushed” way, and markets are barely holding on to expectations of a full 25bp hike for the remainder of the year. The latest ECB inflation expectations survey points to significant easing in household fears about inflation, and the increasing lack of energy price sensitivity to developments in the Gulf should translate into softer headline inflation globally in the coming months. We doubt that President Christine Lagarde will pledge anything more than “maximum vigilance” in upcoming Sintra comments.
China easing: Any shift in the PBoC’s liquidity management will have implications for global financial conditions. The new overnight reverse repo facility has debuted at 1.25%, which is 15bp below the key 7-day reverse repo rate and also below the 1.30-1.35% consensus range before the operation. Evidently, the weak round of data seen over the past month has increased the impetus for stimulus, and we firmly believe that fiscal measures are on the way. However, such responses can only go so much without fundamental change in corporate “involution,” and the message is clear as Beijing’s city government issued yet another summons to platform firms to improve profitability.
Bottom line: The conflict’s impact on inflation is likely at its lowest ebb, but a new wave of supply constraints is already emerging and is likely to persist well beyond current forecast horizons. South Korea’s ₩1.350qn (roughly $1tn) public-private investment program for its semiconductor sector underscores the extraordinary scale of capital expenditure required to sustain the global artificial intelligence buildout. With these projects targeted for completion by the end of President Lee’s current term in 2030, the race to secure critical minerals, industrial materials, specialized equipment and intermediate inputs is set to intensify, reinforcing supply-side inflationary pressures well beyond the current cycle. Any relief for central banks may therefore prove short-lived, and this week’s Sintra forum presents a timely opportunity for Fed Chair Kevin Warsh and his peers to reinforce a tough but credible message that the fight against inflation is far from over.
Fed Chair Kevin Warsh will announce more taskforce details in the coming weeks as he pushes to reshape the institution, reports the New York Times. In a June 2 letter to Fed staff, he pledged open discussions and a future-focused institution. He has set up five taskforces covering communication, the $6.7tn balance sheet, data priorities, productivity and jobs, and inflation models, with outside experts playing a leading role. At his first policy meeting, the Fed issued a shorter statement that stressed price stability and removed forward guidance. The move has supported market expectations of higher volatility, while investors debate whether rates will rise or remain on hold. S&P Mini +0.69% to 7453, DXY -0.066% to 101.291, 10y UST +1.2bp to 4.38%.
The U.S. and Iran have agreed to halt attacks on each other ahead of renewed talks this week on the Strait of Hormuz and related issues, after several days of retaliatory strikes threatened a fragile interim truce. A U.S. official said technical discussions will continue on the memorandum of understanding reached this month, with both sides stepping back for now and shipping allowed to move more freely. The confrontation began after an Iranian strike on a container ship triggered U.S. retaliation, followed by further exchanges over vessel attacks. Markets reacted cautiously, with Brent crude rising and U.S. equity futures gaining as tensions eased slightly. Brent +0.903% to 72.64, WTI +1.228% to 70.08, Omani crude +3.847% to 66.69, Dubai crude -0.575% to 79.214.
ECB President Christine Lagarde will give what may be her final Sintra opening keynote address tonight, opening the three-day flagship ECB symposium with the theme “Shaping Europe’s future: innovation, growth and stability.” The highlight of the sessions is a policy panel she will share with Federal Reserve, Bank of England and Bank of Canada counterparts. ECB officials will feature heavily in discussions relating to growth and productivity, but the stasis seen across national governments continues to hinder long-term prospects and the current asset allocation outlook remains heavily biased against Europe due a widening innovation gap versus the U.S. and Asia. Euro Stoxx 50 -0.16% to 6212, EURUSD +0.132% to 1.1399, BBG AGG Euro Government High Grade EUR 0bp to 3.148%.
The PBoC has set the rate on its new overnight liquidity tool at 1.25%, below the 1.30-1.35% consensus range, in a move widely viewed as a mild dovish surprise and a de facto easing signal. The bank also carried out ¥300bn of overnight reverse repurchase operations, while its seven-day reverse repo benchmark stayed at 1.4%. The action is the first use of this facility to manage liquidity and is intended to better control short-end borrowing costs, smooth cash market volatility and support a more market-oriented framework for short-term rate setting. Market reaction was modest, with government bond yields edging lower after the announcement. CSI 300 +1.21% to 4927, USDCNY -0.106% to 6.7932, 10y CGB -1.2bp to 1.714%.
China blacklisted more Japanese firms on Monday as its dispute with the Takaichi government intensified. The Ministry of Commerce added 20 Japanese organizations to its export control list and placed another 20 entities under closer monitoring. The measures ban Chinese exports with commercial or military uses to the blacklisted firms, while also restricting overseas entities from supplying Japanese companies with dual-use technology originating in China. Targets include defense-related institutes, Mitsubishi units, Mitsui E and S, and Japan Nuclear Fuel. Beijing said that Japan has not reversed its remilitarization path, while Tokyo has rejected that claim. The move raises supply chain risks, especially for rare earths and defense manufacturing, and extends tensions linked to Taiwan comments. Nikkei +0.15% to 69468, USDJPY +0.075% to 161.86, 10y JGB +1.9bp to 2.64%.
U.S. June Dallas Fed Manufacturing Activity is forecast to rise to 1.0 vs. 0.4.
Central bank speakers: ECB Forum on Central Banking in Sintra; ECB President Christine Lagarde speaks in Sintra.
U.S. Treasury sells $92bn in 13-week bills and $79bn in 26-week bills.
Mood: Selling pressure in core sovereign bonds continues to build, while global equities remain under broad selling pressure. iFlow Mood was little changed at -0.119.
FX: Mixed, moderate flows. USD and NZD attracted inflows, while CAD, JPY and NOK saw outflows. JPY scored holdings turned negative.
FI: There was broad-based demand for sovereign bonds, led by the Eurozone, the U.K and India. Selling was concentrated in Philippine, Colombian and Japanese government bonds.
Equities: Flows remained biased toward outflows, led by South Korea, the Philippines, Taiwan and the U.K. Selected inflows were seen in India, Malaysia, China and Türkiye.
“The world ahead is more uncertain – and that uncertainty is likely to make inflation more volatile.” – Christine Lagarde, 2025 Sintra Keynote
“Data dependence does not mean data point dependence.” – Christine Lagarde, 2024 Sintra Keynote
“Faced with a more persistent inflation process, we need a more persistent policy.” – Christine Lagarde, 2023 Sintra Keynote
Euro area monetary developments for May showed a firmer expansion in liquidity and credit. Broad money M3 rose 3.2% y/y, up from 2.7% in April, while M1 increased to 4.0% from 3.8%. Lending also strengthened, with adjusted loans to households edging up to 3.1% from 3.0% and adjusted loans to non-financial corporations rising to 4.0% from 3.4%. Household deposits were unchanged at 2.9%, corporate deposits accelerated to 4.2% and deposits by investment funds excluding money market funds improved sharply but remained slightly negative at -0.4%. Euro Stoxx 50 -0.16% to 6212, EURUSD +0.132% to 1.1399, BBG AGG Euro Government High Grade EUR 0bp to 3.148%.
European Commission business and consumer survey results for June showed a firmer economic mood in the EU and euro area. The Economic Sentiment Indicator rose by 1.3 points in both regions, to 95.1 in the EU and 95.0 in the euro area, while the Employment Expectations Indicator fell sharply to 92.9 and 92.2, respectively, leaving both below their long-term average of 100. The Commission said confidence had improved in most sectors, led by consumers, services, industry and retail trade, but construction weakened. Selling price expectations eased from April’s peaks, and economic uncertainty fell for a second successive month. The survey covered June 1 to 22.
UK household and corporate lending data for May showed a softer pace of credit growth. Net borrowing of mortgage debt by individuals fell to £2.9bn from £4.4bn in April, while mortgage approvals for house purchases dropped to 56,200 and remortgaging approvals eased to 33,300. Consumer credit was broadly steady at £1.7bn, with weaker credit card borrowing partly offset by stronger other consumer credit. Private non-financial corporations borrowed a net £1.1bn, down sharply from £5.4bn in April. Sterling money growth strengthened to £11.0bn, but net lending to the private sector slowed markedly to £0.6bn from £11.5bn in April. FTSE 100 -0.29% to 10477, GBPUSD +0.099% to 1.3213, 10y gilt +1.7bp to 4.748%.
Spanish inflation came in at 3.2% y/y in June in the advanced consumer price index, unchanged from May, while monthly CPI rose 0.6%. The National Statistics Institute said the main upward pressure came from electricity and gas, which rose more than in June 2025, while fuels and lubricants for personal vehicles pulled inflation lower after falling y/y. Core inflation edged down one-tenth to 2.9%. The harmonized index of consumer prices was also stable at 3.6% y/y, with its core measure at 3.3% and monthly growth at 0.6%. The figures are preliminary and will be revised next month. IBEX 35 -0.46% to 19279, EURUSD +0.132% to 1.1399, 10y Bono +0.3bp to 3.346%.
Spanish retail sales rose 1.3% y/y in constant prices on a seasonally and calendar-adjusted basis in May, after a 0.6% rise in the previous month. Monthly sales increased by 0.6%, with all distribution channels up except small chains, which fell 0.2%, while e-commerce posted the strongest gain at 1.6%. Excluding fuel stations, sales rose 0.8% m/m. By product, food was up 0.2% and other goods were 1.4% higher. Retail employment rose 0.4% y/y, while sales decreased y/y in 11 regions and increased in six.
Japanese commercial sales for May came in at ¥52.549tn, up 5.0% y/y and 1.4% m/m on a seasonally adjusted basis. Wholesale sales rose 4.9% to ¥39.102tn, while retail sales increased by 5.3% to ¥13.447tn. Within wholesale, gains were led by mineral and metal materials, other wholesale, agricultural and marine products, machinery and chemicals, while pharmaceuticals and building materials declined. Retail growth was broad-based, with strong gains in automobile and machinery sales. Department stores, supermarkets, convenience stores, drugstores, home centers and large home appliance retailers all posted y/y increases. Nikkei +0.15% to 69468, USDJPY +0.075% to 161.86, 10y JGB +1.9bp to 2.64%.