Market Movers: Reassurance
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoff Yu
Time to Read: 5 minutes
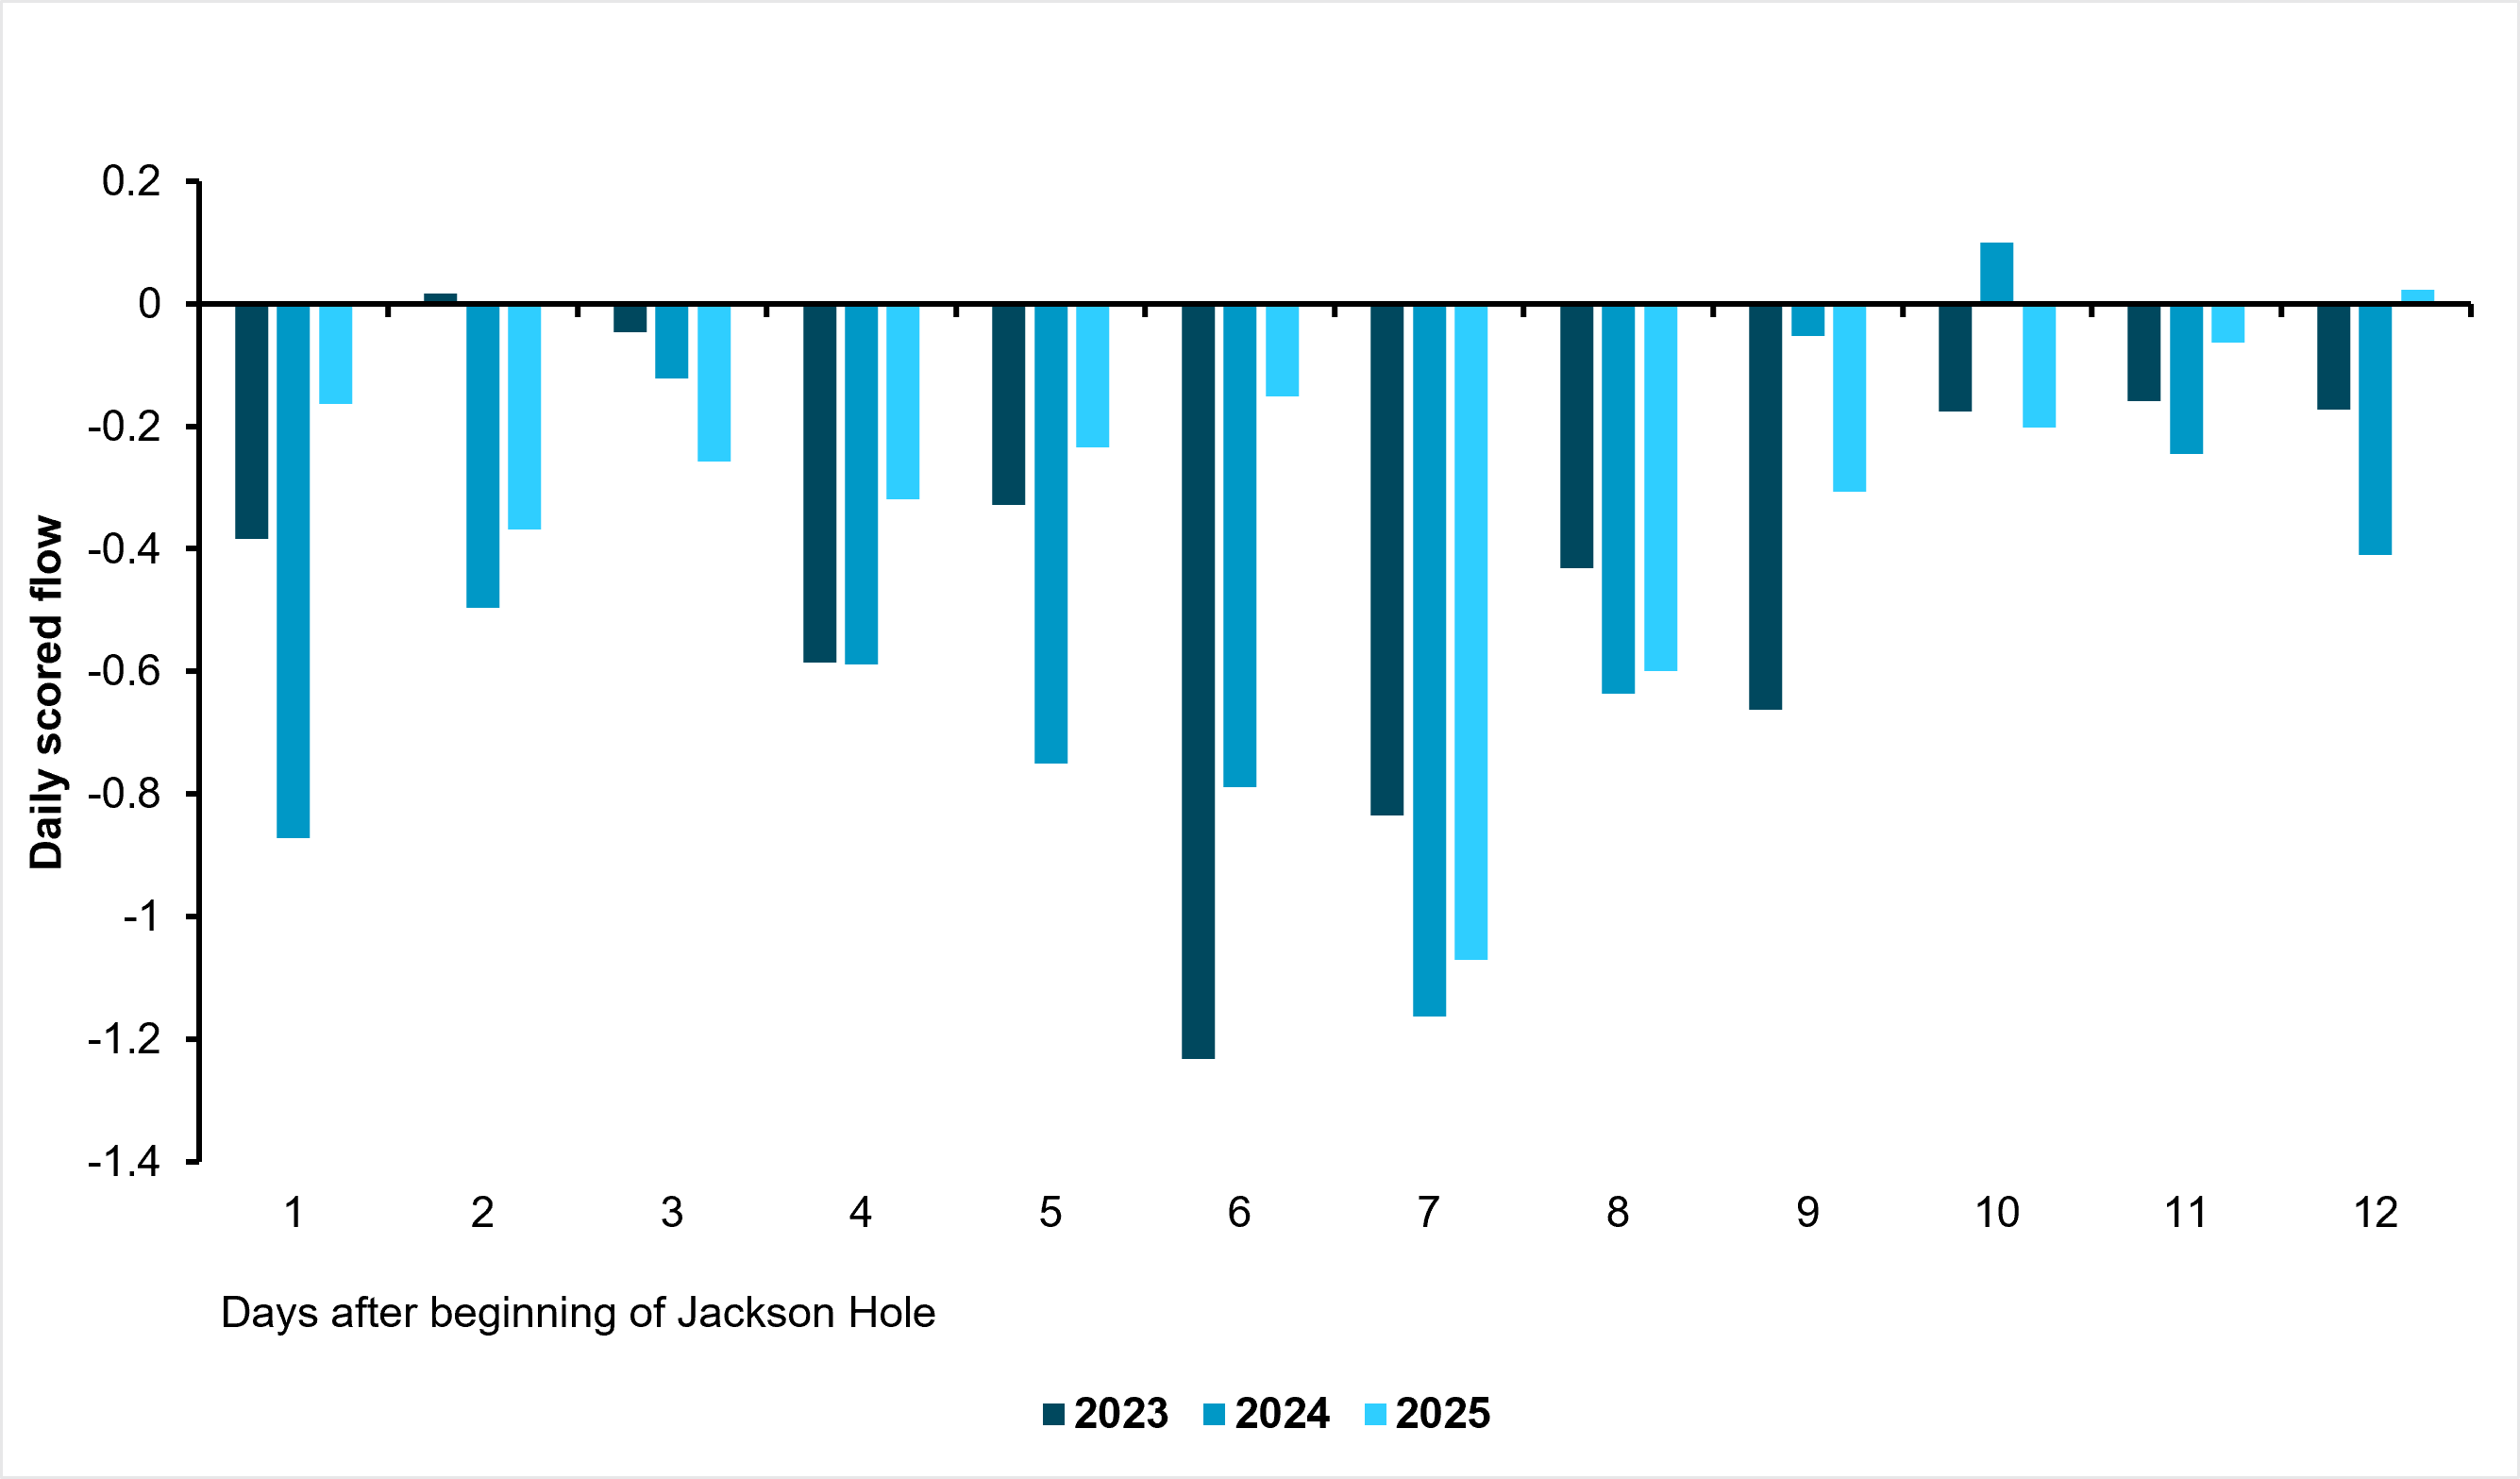
Seasonal dollar selling in play after Jackson Hole
Source: BNY
The clearest pattern across the 2023–2025 Jackson Hole episodes is persistent dollar selling into and through month end, irrespective of the precise policy message. In 2023, the dollar initially extended gains after then Fed Chair Jerome Powell’s relatively hawkish speech, but iFlow subsequently showed a significant pick-up in sales over the following two weeks. Stronger dollar performance created a natural rebalancing opportunity, with the two-week flow average at -0.41. This suggests that even when the policy signal supported the dollar, month-end portfolio adjustments and hedging flows worked in the opposite direction.
The same seasonal pattern was stronger in 2024 and persisted in 2025. After the explicitly dovish 2024 Jackson Hole pivot, dollar selling accelerated and the two-week flow average fell to -0.72. Importantly, selling began before the traditional month-end window, as the policy signal reinforced an already favorable seasonal backdrop. In 2025, the dollar again weakened after Jackson Hole and selling persisted through the subsequent two weeks, including another clear month-end outflow, although the average moderated to -0.30. The historical message is therefore consistent: Jackson Hole has repeatedly been followed by dollar outflows around month end, with the speech determining the magnitude rather than the direction of the seasonal flow.
AI intact: Nvidia has reassured markets that the AI investment cycle remains intact. Revenue and earnings comfortably beat expectations and guidance stayed strong, supporting tech and semiconductor assets even as broader global equity sentiment remains muted. The immediate test has passed, although questions around the ultimate return on enormous AI spending remain. However, the lack of breadth in gains points to a lack of diversified drivers in global growth.
Oil relief: Improving Hormuz flows are providing further reassurance on inflation. Kuwaiti and Qatari crude shipments have reportedly recovered to around 70% of pre-conflict levels, while broader traffic through the strait is also rising. Brent is falling again as supply fears ease, removing some of the energy-driven pressure on the global disinflation outlook.
Hikes continue: South Korea and the Philippines have both shown that central banks will still tighten when inflation demands it. The Bank of Korea (BOK) raised rates 25bp to 3.00%, while the Bangko Sentral ng Pilipinas (BSP) delivered a third consecutive 25bp hike to 5.00%. Supply pressures and fiscal complications may make policymaking harder, but they don’t remove the inflation mandate. We continue to see undervalued APAC currencies such as KRW as the best expression of potential dollar weakness, rather than G10 names.
China keeps talking: Beijing is pairing tough rhetoric with reassurance that dialogue remains open. China has threatened “necessary measures” against U.S. actions while continuing high-level engagement ahead of the prospective Trump–Xi summit. Neither side appears eager to sacrifice the broader relationship. The lack of impact from recent escalation in U.S.–Canadian tensions suggests trade and tariffs have moved to the periphery of market drivers.
Ahead today: The U.S. calendar is light, with advance wholesale inventories the main release as Jackson Hole officially opens – the Kansas City Fed will release the official agenda at 8 p.m. ET. For now, markets have received enough reassurance to keep the larger risk narrative contained.
Brent crude is holding near $87/bbl, well below its late-April peak above $120, as rising oil flows through the Strait of Hormuz ease fears of a prolonged supply shock. Kuwait and Qatar have restored shipments to around 70% of pre-war levels, while total flows through the strait have climbed to roughly 7mn to 8mn barrels a day from about 4mn in mid-July. The recovery has been supported by shuttle operations and greater use of producer-controlled tanker fleets despite security risks and elevated freight costs. With more Gulf barrels reaching the market, the supply disruption premium in oil has continued to compress, even though Washington and Tehran remain deadlocked over control of the strait. Brent -2.902% to 86.01, WTI -2.842% to 80.02, Omani Crude -3.03% to 86.41, Dubai Crude -1.071% to 89.139.
China pushed back against possible new U.S. tariffs while signaling that high-level communication between Beijing and Washington remains open. The Commerce Ministry said it firmly opposes reported U.S. consideration of an additional 7.5% tariff on Chinese imports linked to a Section 301 investigation into alleged overcapacity across 16 economies, describing the move as unilateral and protectionist. Beijing said it will closely assess any further U.S. measures and reserved the right to take all necessary steps in response. Separately, the Foreign Ministry said China and the U.S. remain in contact over arrangements for potential interaction between their leaders later this year. The combined message suggests Beijing is preparing to resist further trade pressure while keeping the diplomatic channel open. CSI 300 +0.85% to 4,591, USDCNY +0.003% to 6.7206, 10y CGB +1.1bp to 1.696%.
The Trump administration is considering broader semiconductor tariffs that could raise costs across the U.S. AI and data center buildout, potentially extending beyond chips to servers, laptops and other electronics. One approach would tie tariff relief to commitments to expand domestic chip production, while reducing exemptions previously available for data centers, research and other uses. The technology industry is warning that U.S. production capacity remains far below near-term demand, especially for advanced semiconductors sourced from Asia, so higher duties could delay investment, raise equipment costs and weaken competitiveness before new domestic fabs come online. The policy therefore highlights a tension between reshoring semiconductor manufacturing and sustaining the rapid AI infrastructure expansion the U.S. is trying to lead. Nasdaq Mini -0.18% to 29,225, DXY +0.076% to 98.99, 10y UST +1.4bp to 4.643%.
The BOK raised its policy rate by 25bp to 3.00%, delivering a second consecutive hike as strong semiconductor demand lifts growth and adds to inflation pressure. The BOK raised its 2026 GDP forecast to 3.3% from 2.6% and its 2027 forecast to 2.9% from 2.1%; core inflation projections were also revised higher to 2.5% for both years. Policymakers highlighted robust exports, investment and gradually improving consumption, but warned that stronger demand could reinforce inflation, housing prices and household debt. The won strengthened after the decision, while the Kospi also rose. The BOK’s projections point to further tightening, though at a slower pace, suggesting the focus is shifting from front-loaded hikes toward more measured normalization. KOSPI +0.97% to 6,808, USDKRW +0.062% to 1384.9, 10y KTB -0.9bp to 4.318%.
U.S. July Advance Goods Trade Balance is forecast to narrow to -$100.5bn vs. -$101.5bn. Goods Imports are forecast at -0.3% m/m vs. -2.4% m/m prior. Goods Exports are forecast at -1.0% m/m vs. -1.8% m/m prior.
U.S. July Retail Inventories are forecast at 0.2% m/m vs. -0.2% m/m prior.
U.S. July preliminary Wholesale Inventories are forecast to remain unchanged at 0.2% m/m.
U.S. Initial Jobless Claims are forecast to rise to 208k vs. 206k.
U.S. August Kansas City Fed Manufacturing Activity is forecast to rise to 10.0 vs. 9.0.
Canada June Payroll Employment Change, 24.1k prior.
Canada Q2 Current Account Balance is forecast to swing to $3.9bn vs. -$7.18bn.
Central banks: ECB Publishes Account of July 22–23 Meeting, National Bank of Poland Publishes Minutes of Rate Meeting.
U.S. Treasury sells $100bn 4-week bills, $90bn 8-week bills and $44bn 7y notes.
Mood: iFlow Mood continued to narrow, remaining in risk-neutral territory at –0.0873.
FX: Global flows were contained, with inflows into GBP and KRW, and outflows from AUD and SEK.
Fixed Income: G10 flows were mixed, with flows into European and Swiss sovereign bonds. Meanwhile, New Zealand and Norwegian bonds were under selling pressure.
Equities: Global equity flows were quiet aside from notable inflows for Polish stocks.
“Although the world is full of suffering, it is full also of the overcoming of it.” – Helen Keller
“Nothing in life is to be feared; it is only to be understood.” – Marie Curie
Germany’s consumer climate for August slipped to -29.6 from a revised -29.3 in July, remaining at a very weak level, as softer income expectations and a renewed rise in saving offset slightly better spending intentions. Income expectations fell 2.3 points to -14.5, while willingness to save increased 3.1 points to 17.0, underscoring continued household caution. Willingness to buy improved 3.5 points to -9.9, and economic expectations rose for a third consecutive month to -6.3 from -8.7. Inflation concerns also increased modestly following higher fuel prices after the subsidy’s expiration. Overall, sentiment remains subdued, suggesting private consumption is likely to stay constrained despite tentative improvement in the broader economic outlook. DAX +0.14% to 26,303, EURUSD -0.078% to 1.1666, 10y Bund +0.3bp to 3.204%.
Norway's mainland GDP rose 0.3% q/q in Q2 2026, close to the economy’s estimated normal growth rate, with activity supported by services, parts of manufacturing, aquaculture, and public spending. Public administration output increased 0.5%, while manufacturing activity rose 1.2% and mainland business investment climbed 2.9%. Construction remained weak, falling 0.9%, while household consumption slipped 0.1%. Oil and gas investment surged 9.9%, and higher energy prices linked to the Middle East conflict lifted nominal exports and the trade surplus despite lower oil and gas export volumes. Employment increased 0.2%. The data point to modest underlying growth, with fiscal support offsetting the drag from high interest rates and continued weakness in rate-sensitive sectors. OSE -0.66% to 2,084, EURNOK +0.179% to 10.893, 10y NGB -1.2bp to 4.376%.
Japan’s final machine tool orders for July rose 50.4% y/y to ¥193.1bn, extending the strong expansion seen in recent months, although orders fell 5.1% m/m from June. Domestic orders increased 50.2% y/y to ¥53.2bn, while foreign orders rose 50.5% to ¥139.9bn, confirming that external demand remained the main driver. By sector, electrical and precision machinery orders surged 104.0% y/y, including a 192.3% rise in electrical machinery, while industrial machinery increased 70.1% and construction 75.0%. Autos were up 15.3% y/y, but aircraft orders fell 21.4%, and die casting declined 44.1%. The data point to still-strong capital goods demand despite some monthly cooling. Nikkei +0.62% to 66,262, USDJPY -0.126% to 158.99, 10y JGB +0.1bp to 2.904%.
The BSP raised its Target Reverse Repurchase rate by 25bp to 5.00%, with the overnight deposit and lending rates lifted to 4.50% and 5.50%, respectively. The BSP said preemptive tightening was warranted despite easing headline inflation because oil prices remain volatile, severe El Nino conditions could lift food prices, and potential wage increases may generate broader second-round effects. Inflation is still expected to exceed the 4.0% upper tolerance bound in both 2026 and 2027, while core inflation points to widening price pressures, before headline inflation returns close to the 3.0% target by 2028. BSP said medium-term growth fundamentals remain intact and signaled further action if required to restore price stability. PSEi -0.86% to 6,137, USDPHP -0.175% to 61.63, 10y PHGB +0.7bp to 7.175%.