Market Movers: Protection
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 6 minutes
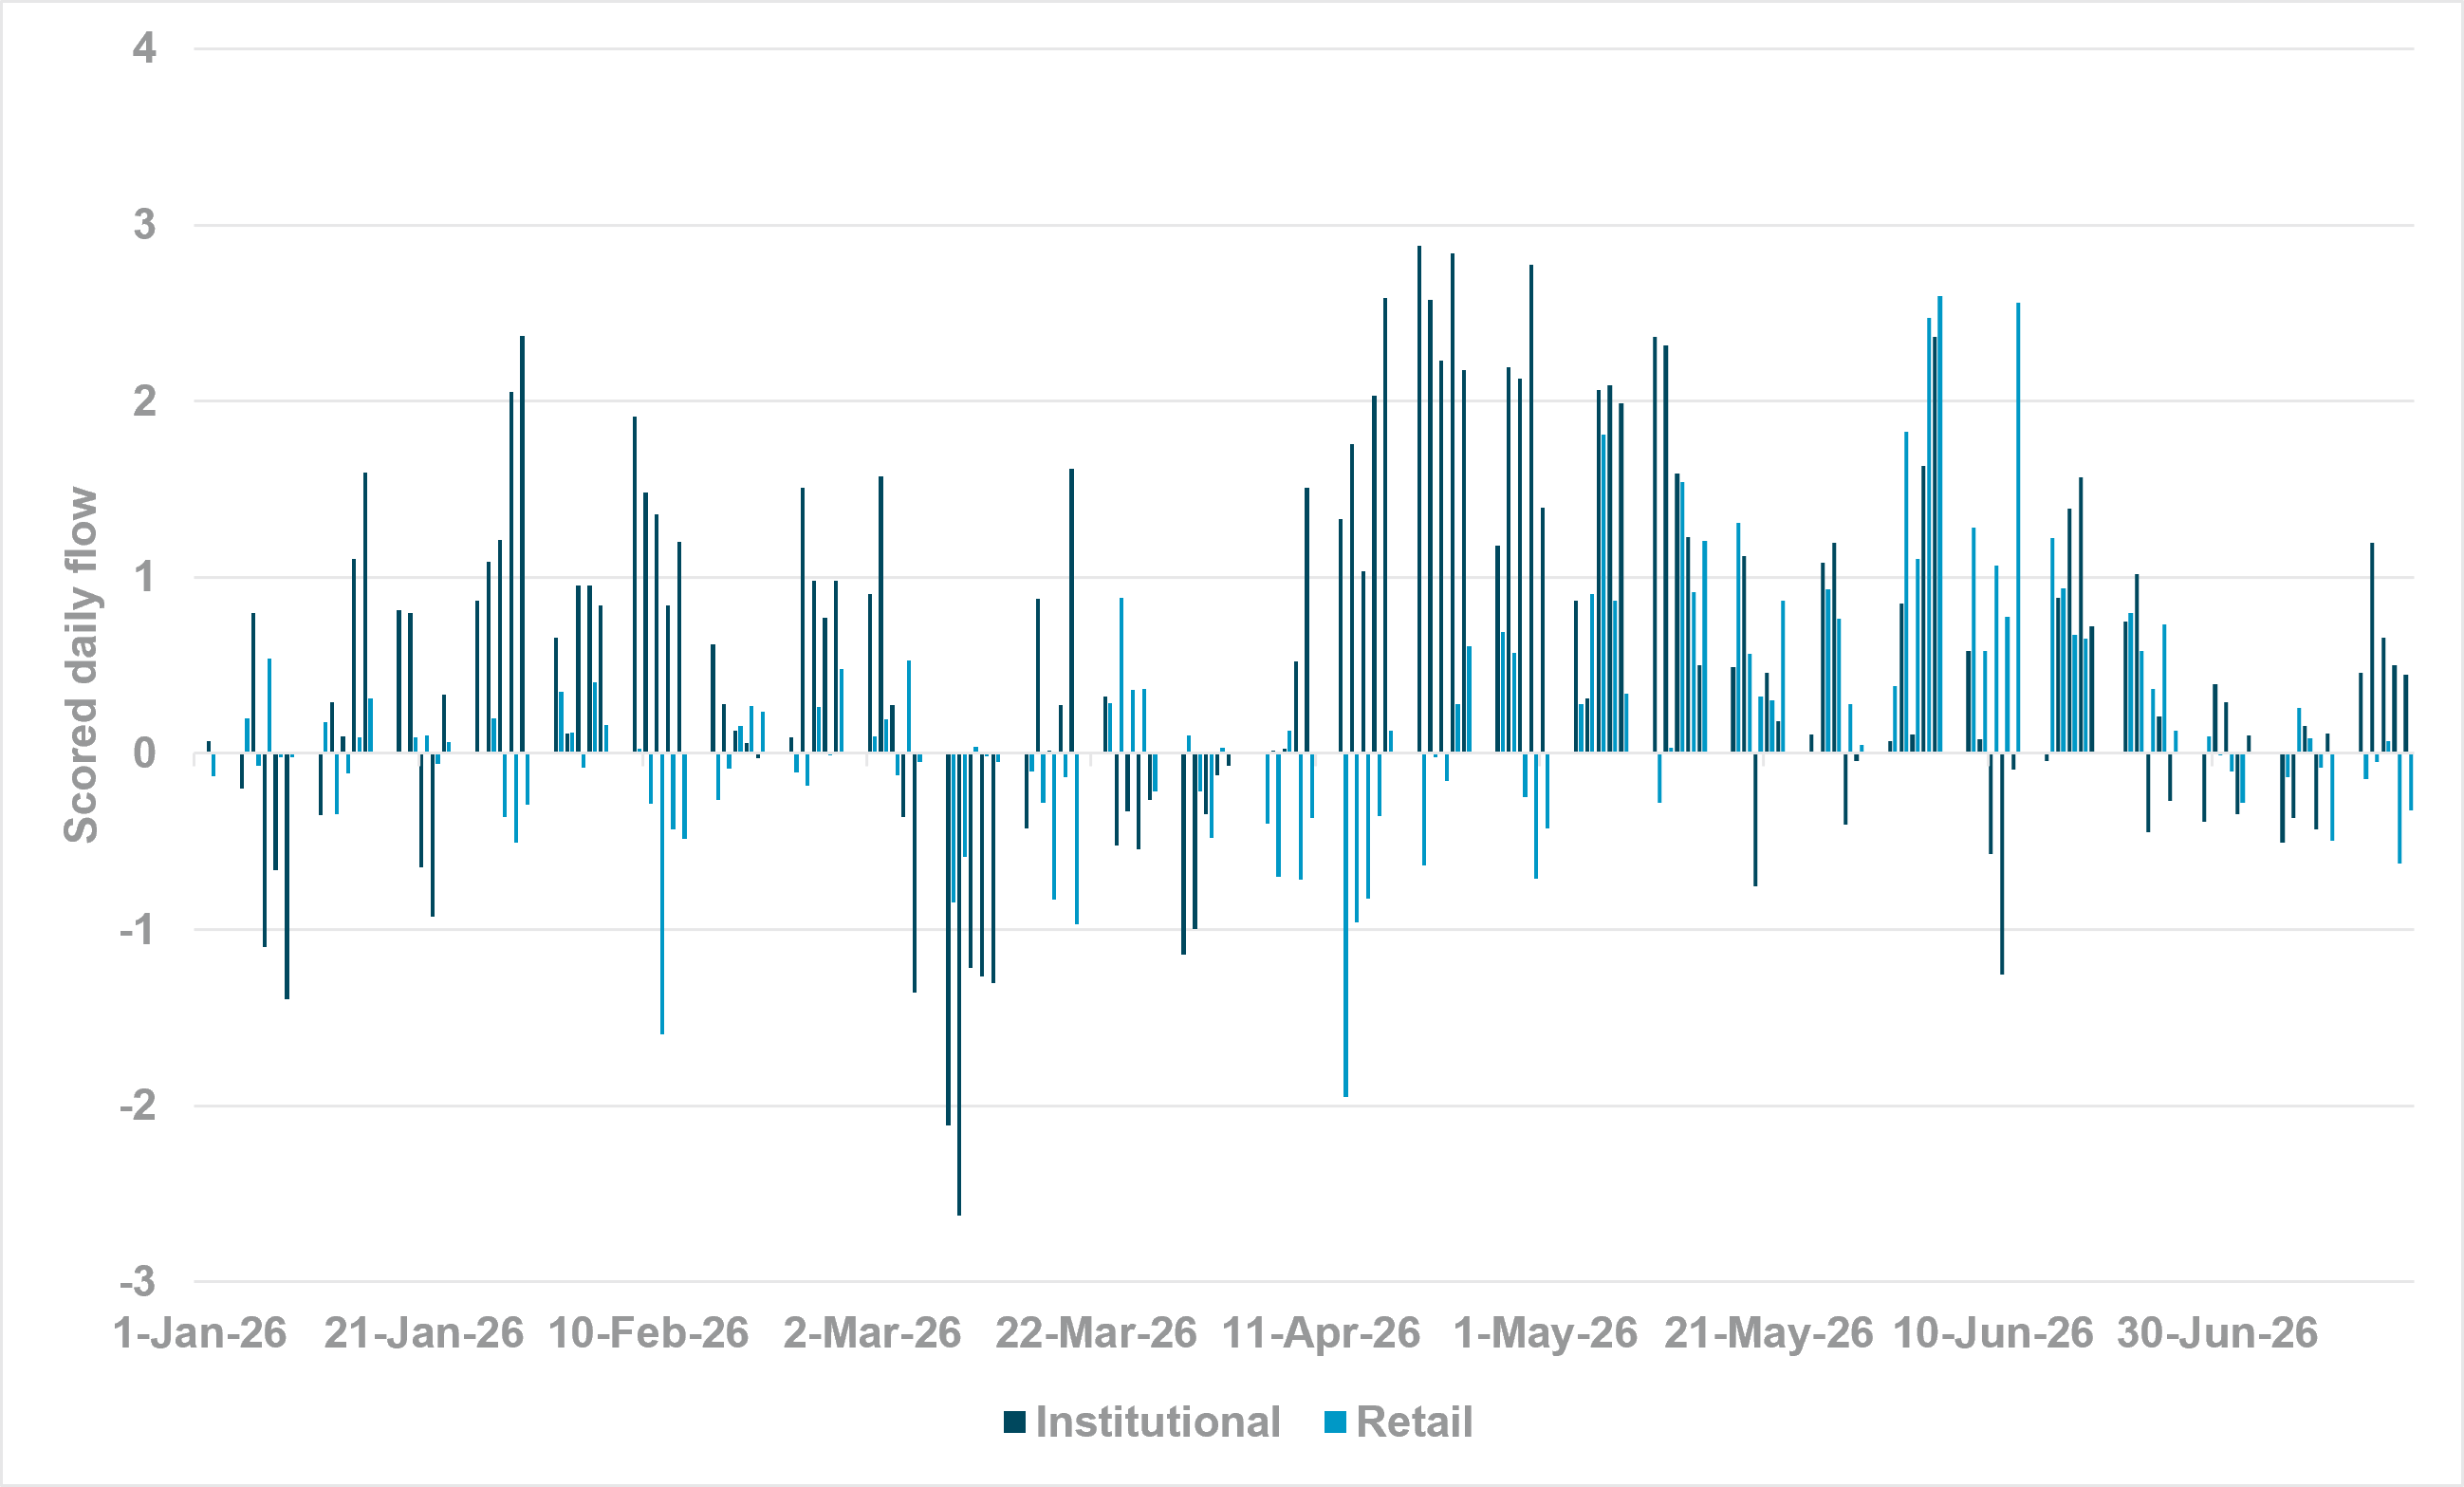
Institutional flow recovery in China supports official narrative
Source: BNY, GPIF
China’s “national team” of regulators and state backed funds moved to calm A-share volatility on Monday after global tech deleveraging and profit-taking spilled into domestic markets. The China Securities Regulatory Commission held an investor symposium, signaling stronger supervision, investor protection and a commitment to stable market operations. At the same time, the so-called national team injected about ¥60bn through stock buyback re-lending facilities, with centrally administered state firms buying shares in SOEs, technology companies and ETFs. The intervention was framed as a stabilization measure rather than a response to weaker fundamentals, with officials and market participants pointing to resilient GDP growth, strong high-tech manufacturing and continued AI-related momentum as longer term support for Chinese equities.
Our data indicate that this had been expected, as institutional flows last week jumped materially after material sales throughout much of June. As key levels approached, the signaling was clear, and we expect both domestic and cross-border participation to push higher. Whether retail participates is a different question: this group moved from clear selling interest in early April to strong purchases in mid-June – even absorbing some institutional sales – but the recent momentum turn is clear. Institutional pickup in Chinese equities, with official backing, is a clear upside risk to APAC sentiment heading into month end, especially with the customary end-July politburo meeting due to set the growth agenda for the rest of the year.
Imperfect hedges: Markets are trying to own protection, but the hedge is imperfect. In the Gulf, a tenth day of strikes keeps the shipping-risk channel alive and leaves oil trading with a geopolitical premium. Gold has edged higher, but higher oil is not just a risk-off signal; it’s also an inflation shock. That is why Treasurys haven’t behaved like a simple safe haven. De-escalation efforts, including talk of a proposed U.S.–Iran truce, complicate the picture further. Investors are paying for protection while still having to price the possibility that the shock fades.
Trade defense: Canada shows the difference between protecting an economy and raising trade barriers. Washington’s additional 50% duties on certain Canadian goods are a direct trade shock, while Canada is trying to preserve market access and limit domestic damage. Mark Carney’s signal that talks could intensify matters because Ottawa is defending its most important export relationship. For asset allocators, pricing tariff risk is becoming the new normal in Canada, not just a short-term political threat.
Fiscal shield: The U.K. is testing fiscal protection. Prime Minister Andy Burnham’s removal of VAT on household electricity bills offers direct relief to consumers and a modest cushion to real incomes. There’s also talk of business-rates relief. But gilt and sterling weakness underline the trade-off. Household protection can quickly become a credibility problem if investors question whether fiscal easing is fully funded or part of a broader political shift. The measure itself is manageable; the signal is what markets are watching.
Market backstop: China’s national team is offering market protection, not macro repair. State-backed equity purchases can stabilize benchmarks and reduce downside pressure, but they don’t solve weak domestic demand or the property drag. Beijing can protect prices, but confidence still requires a stronger growth impulse.
Bottom line: Protection is the theme, but it’s partial and expensive. Energy hedges, tariff talks, household tax relief and state-backed equity buying can cushion shocks, but none removes the underlying risks. Markets are not short of protection mechanisms; they’re short of clean resolutions.
The U.S.–Iran conflict intensified for a tenth straight day while mediators tried to restore a fragile truce, with the Houthis in Yemen threatening a new maritime front in the Red Sea. The U.S. Central Command said it hit command centers, launch sites and air defenses in Iran, while Iran struck U.S. military sites in Kuwait and Jordan. The U.K. navy reports also pointed to attacks on vessels near the Strait of Hormuz. The standoff has lifted Brent crude to $88.45 a barrel and pushed U.S. gasoline above $4 per gallon. Disruptions to Hormuz shipping could further tighten global oil supplies and raise geopolitical risk. Brent -0.729% to 88.57, WTI -0.505% to 82.81, Omani Crude +2.597% to 81.79, Dubai Crude +0.108% to 75.268.
New U.K. Prime Minister Burnham announced a cut in the household energy bills tax, scrapping the 5% VAT charge from October 1 as the first step in his cost-of-living package. The government said the move will save families about £45 a year, cost £850mn in 2026–27 and be financed by abandoning the previous administration’s digital ID plan. Officials said the measure could trim headline inflation by 0.1 percentage point. Burnham said the policy is meant to give households breathing space, while critics questioned the funding plan and noted that broader energy price pressures remain elevated. FTSE 100 +0.06% to 10,531, GBPUSD +0.008% to 1.3432, 10y gilt -1.6bp to 5.016%.
The Trump administration said it will impose a fresh 50% tariff on select Canadian goods, escalating U.S.–Canada trade tensions. The levies, due to take effect in 30 days, target milk and cream, hockey equipment and alcohol, while excluding major resource imports such as energy, potash, fish and critical minerals, as well as goods already covered by separate auto and steel duties. The move was justified under Section 338 of the 1930 Tariff Act and tied to what Washington called unfair Canadian treatment of U.S. alcohol, cars and dairy. U.S. officials said there will be no USMCA exemptions. Canada said it had seen similar threats before. The announcement adds strain to already fragile trade talks after the U.S. declined to renew USMCA, with the Canadian dollar slipping on the news. S&P Mini +0.55% to 7,525, DXY -0.062% to 100.887, 10y UST -0.6bp to 4.586%.
Japan’s Cabinet approved its first economic and fiscal policy guidelines under Prime Minister Sanae Takaichi, marking a clear shift toward aggressive, strategic fiscal spending with no explicit call for fiscal consolidation. The blueprint treats the next fiscal year from April as the first year of “responsible and proactive” spending and targets ¥370tn of combined public-private investment by fiscal 2040, with a focus on 17 areas, especially semiconductors. It also introduces a new budget allotment from fiscal 2027 and ends the traditional push for a single-year primary surplus, instead seeking to steadily lower the debt-to-GDP ratio over time. The government aims for real growth above 1% and nominal growth above 3% and plans to decide on a possible food tax cut by early August. It reiterated that monetary policy remains the Bank of Japan’s (BOJ) responsibility. Nikkei +3.26% to 66,232, USDJPY -0.093% to 162.55, 10y JGB +3.3bp to 2.732%
The Bank of Korea said it will launch a pilot program in September for a 24-hour offshore won settlement network, the BOK Won International Wire Network, as part of efforts to improve foreign investors’ access to South Korea’s financial market. The system is being tested with four local banks, and related regulations are set to be revised by August before the pilot begins. Full implementation is scheduled for January. The network will operate from 9 a.m. to 9 a.m. the next day on business days, excluding weekends and public holidays. It will allow offshore investors to trade the won more freely with other foreign investors through accounts opened at banks in their home countries. The BOK said the move should support South Korea’s bid for inclusion in the MSCI Developed Markets Index. KOSPI +3.56% to 6,748, USDKRW +0.183% to 1475.45, 10y KTB +4.2bp to 4.342%.
The Hungarian Central Bank is expected to cut its benchmark rate by 25bp to 5.75%.
U.S. ADP Weekly Employment Change, 19.8k prior.
U.S. July Philadelphia Fed Nonmanufacturing Activity, -25.8 prior.
U.S. Treasury sells $95bn in 6-week bills.
Mood: Investors continue to put cash to work, adding to both global equities and core sovereign bonds. Risk appetite remains resilient, with demand tilting toward duration over equities.
FX: Defensive USD demand persisted against CAD and GBP outflows. Flows were moderate and mixed across EMEA, LatAm and APAC, led by outflows from SGD and CNY.
FI: Investors rotated into core duration. Buying concentrated in Eurozone sovereigns, JGBs, U.S. Treasurys and U.K. gilts, while APAC and EMEA bonds faced broad selling, led by Malaysia and Hungary.
Equities: EM remained the preferred destination for equity risk, driven by strong buying in Thailand. G10 equities saw broad selling led by Canada and Sweden.
“You have to take away the punch bowl when the party is warming up.” – William McChesney Martin
“If you’ve got a bazooka in your pocket, and people know it, you may not have to take it out.” – Henry Paulson
Euro area bank lending survey for Q2 2026 showed credit standards tightening moderately for firms and households, with net 7% of banks reporting tighter standards for enterprise loans, net 9% for housing loans, and net 12% for consumer credit and other household lending. Loan demand for firms rose slightly, at net 3%, helped by inventories, working capital and refinancing needs, while housing loan demand fell sharply to net -15% and consumer credit demand slipped to net -2%. Banks said higher risk perceptions, lower risk tolerance and weaker economic outlook were the main drivers, and they expect further tightening and softer household demand in Q3. Euro Stoxx 50 +0.45% to 6,255, EURUSD +0.071% to 1.1422, BBG AGG Euro Government High Grade EUR 0bp to 3.419%.
Germany’s ZEW economic sentiment for July 2026 rose sharply, with the indicator climbing 15.8 points to 26.3, signaling a stronger improvement in expectations for the next six months. The assessment of the current situation also improved, though it remained deeply negative, at -77.6 after a 3.4-point gain from June. ZEW said the outlook is being helped by reforms, with export-oriented sectors and domestic demand seeing sustained growth, while uncertainty linked to the Iran conflict and oil prices still clouds the recovery. Sector balances improved broadly, led by mechanical engineering and domestic demand, although autos weakened further. Eurozone sentiment also improved. DAX +0.09% to 24,870, EURUSD +0.071% to 1.1422, 10y Bund -0.1bp to 3.149%.
U.K. labor market data for March to May 2026 and June 2026 showed a softer employment backdrop, with payrolled employees falling by 85,000 y/y and the early June estimate down 71,000, while monthly changes were broadly flat. The unemployment rate rose to 4.9% and the employment rate slipped to 75.1%, while economic inactivity edged down to 20.9%. The claimant count increased in June to 1.689mn, vacancies fell by 7,000 to 712,000, and earnings growth remained positive, with regular pay up 3.4% and total pay up 4.3%. Real pay also rose modestly, and labor disputes led to 26,000 lost working days in May. FTSE 100 +0.06% to 10,531, GBPUSD +0.008% to 1.3432, 10y gilt -1.6bp to 5.016%.
U.K. public sector net borrowing for June 2026 came in at £16.0bn, down £7.9bn, or 33.1%, from June 2025 and £0.3bn below the Office for Budget Responsibility forecast, helped by lower inflation linked debt interest costs. For the fiscal year to June 2026, borrowing totaled £57.6bn, or 1.9% of GDP, slightly below a year earlier but still above forecast. The public sector’s current budget deficit reached £42.0bn year to date, while net debt rose to £2,989.9bn, or 94.9% of GDP, near early 1960s highs. Central government net cash requirement was £19.2bn, above last year but below forecast.
Japan’s Government Pension Investment Fund (GPIF) is making its first direct in-house investment in a Japan-focused private equity fund, committing ¥20bn to a 10-year vehicle run by Advantage Partners. The move comes amid speculation that GPIF may allocate more capital to domestic assets, after Prime Minister Takaichi said last week that home-market investment should be a key initiative for the fund and support Japan’s economy. GPIF, one of the world’s largest pension funds, had more than ¥293tn in assets as of the fiscal year ended March 31, and currently splits holdings roughly evenly across domestic and foreign stocks and bonds. The investment signals a notable shift toward domestic private markets, with potential implications for Japan’s asset allocation and broader capital flows. Nikkei +3.26% to 66,232, USDJPY -0.093% to 162.55, 10y JGB +3.3bp to 2.732%.
Japanese insurers bought the most super-long JGBs in three years in June, signaling that demand from a key buyer is stabilizing as yields look more attractive. Life and casualty insurers bought a net ¥630.5bn of JGBs with maturities over 10 years, the largest amount since July 2023. The move suggests some investors are warming again to long-dated debt after yields peaked in mid-May. The report also notes policy support, including a proposal to add government bonds to a tax-free investment program and Takaichi’s comments encouraging the GPIF to raise investment in Japanese financial assets. Meanwhile, overseas investors sold the most 2y and 5y notes since December 2022, as demand weakened after the BOJ raised rates in mid-June and signaled further hikes if the economy warrants.
New Zealand’s Q2 2026 CPI rose 1.5% q/q and 4.1% y/y vs 0.9% q/q, 3.1% y/y in Q1. The higher inflation was driven mainly by fuel and housing costs. Tradeable inflation accelerated to 2.7% q/q and 4.9% y/y (Q1: 0.7% q/q, 2.5% y/y), while non-tradeable eases to 0.6% q/q and 3.4% y/y (Q1: 1.1% q/q, 3.5% y/y). The core measure excluding food, household energy and vehicle fuels increased 0.4% q/q and 2.5% y/y. On the quarter, the biggest upward contributors were petrol (+20.1%), other vehicle fuels and lubricants (+47.7%), and purchase of housing (+1.6%), while fruit (-8.5%) and domestic accommodation services (-12.0%) pulled lower. Over the year, petrol (+27.5%), electricity (+12.0%) and other vehicle fuels and lubricants (+71.0%) were the main upside drivers, partly offset by oils and fats (-9.1%) and real estate services (-4.6%). NZX 50 -0.29% to 13,656, NZDUSD +0.171% to 0.5863, 10y NZGB -2.4bp to 4.681%.
China’s five major insurers – PICC, China Life, Ping An, CPIC and New China Life – jointly voiced strong support for capital market development, highlighting their role as long-term, patient capital. They said China’s economy remains resilient, with improving industrial profits and a better export mix, while industrial upgrading and technological innovation are increasingly visible in listed companies. China Life said its investment platform made net equity purchases of more than ¥10bn in a single day, underscoring active support for market stabilization. The insurers said they will keep raising equity allocation, focus on strategic emerging industries, advanced manufacturing, new infrastructure, technology growth and new quality productive forces, and continue value, long-term and stable investing. They also stressed commitment to steady dividends and investor returns. CSI 300 +3.05% to 4,738, USDCNY +0.058% to 6.7645, 10y CGB -0.3bp to 1.734%.
HKEX is set to advance listing reforms aimed at boosting Hong Kong’s competitiveness, according to sources. The exchange is expected to allow confidential filings, letting applicants keep certain listing details private until approval, reversing its current requirement for immediate public disclosure. It’s also likely to lower market capitalization thresholds for start-ups and other innovative issuers, including weighted voting right companies and overseas-listed firms seeking secondary listings. The move follows consultations begun in March and could be announced by month end. Market participants reportedly broadly support confidential filings, which HKEX sees as important to attract start-ups that currently prefer the U.S., U.K. or Singapore. The reforms are part of HKEX’s effort to compete with global peers and win back IPO momentum. Hang Seng +0.11% to 25,170, USDHKD -0.014% to 7.8419, 10y HKGB -1.2bp to 1.417%.
South Korea’s trade data for July 1–20 showed exports at a record high for this period, but momentum cooled from June. Exports rose 52.3% y/y to $54.9bn (down from $61.9bn in the same period last month), while the daily average eased -8.2% m/m due to lesser number of working days this year, despite a 62.9% y/y gain. Semiconductors led growth, surging 180.6% y/y to $22.1bn, while passenger cars fell 10.6% y/y and auto parts dropped 9.6% y/y. Shipments to China, the U.S., and Vietnam all rose sharply. Imports increased 20.0% y/y to $42.7bn, led by higher crude oil and gas purchases. The trade balance posted a $12.2bn surplus, narrowing from $17.4bn, last month’s comparable period. KOSPI +3.56% to 6,748, USDKRW +0.183% to 1475.45, 10y KTB +4.2bp to 4.342%.
Taiwan’s June external orders surged on strong AI, high-performance computing (HPC) and cloud-service demand. Orders totaled US$95.26bn, up 6.5% m/m and 59.4% y/y, with seasonally adjusted growth of 8.1%. On a quarterly basis, Q2 orders rose 17.4% q/q. By product, electronics and information/communication equipment led gains, while optical equipment slipped as panel stocking demand cooled. By market, the U.S. remained the largest source, followed by China/Hong Kong, Europe, ASEAN and Japan. The share of overseas production was 47.1%, up 0.8 percentage point y/y. The ministry said AI infrastructure investment and cloud providers’ capex should keep demand supported, but geopolitical risks and trade policy remain headwinds. For July, surveyed firms were slightly cautious, with more expecting orders to be flat than to rise. TAIEX +4.2% to 44,233, USDTWD -0.3% to 32.345, 10y TGB +4.1bp to 1.74%.
Indonesia will fully roll out its single-gateway export system for strategic natural-resource commodities on September 1, 2026, bringing forward the original January 1, 2027 deadline. President Prabowo Subianto said the system is now in transition and will be used to tighten oversight of exports, boost foreign exchange earnings, and curb fraud. The policy, run through Danantara Sumberdaya Indonesia, covers key commodities including coal, crude palm oil and ferroalloys. Prabowo said the aim is to give the state clearer visibility on export volumes, buyers, actual prices and foreign exchange repatriation. He cited under-invoicing and transfer pricing as major leakages and used palm oil as an example of large price discrepancies between Indonesian export records and overseas purchase prices. JCI +1.54% to 6,328, USDIDR +0.375% to 17875, 10y IDGB +1.3bp to 7.29%.