Market Movers: Pause
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 6 minutes
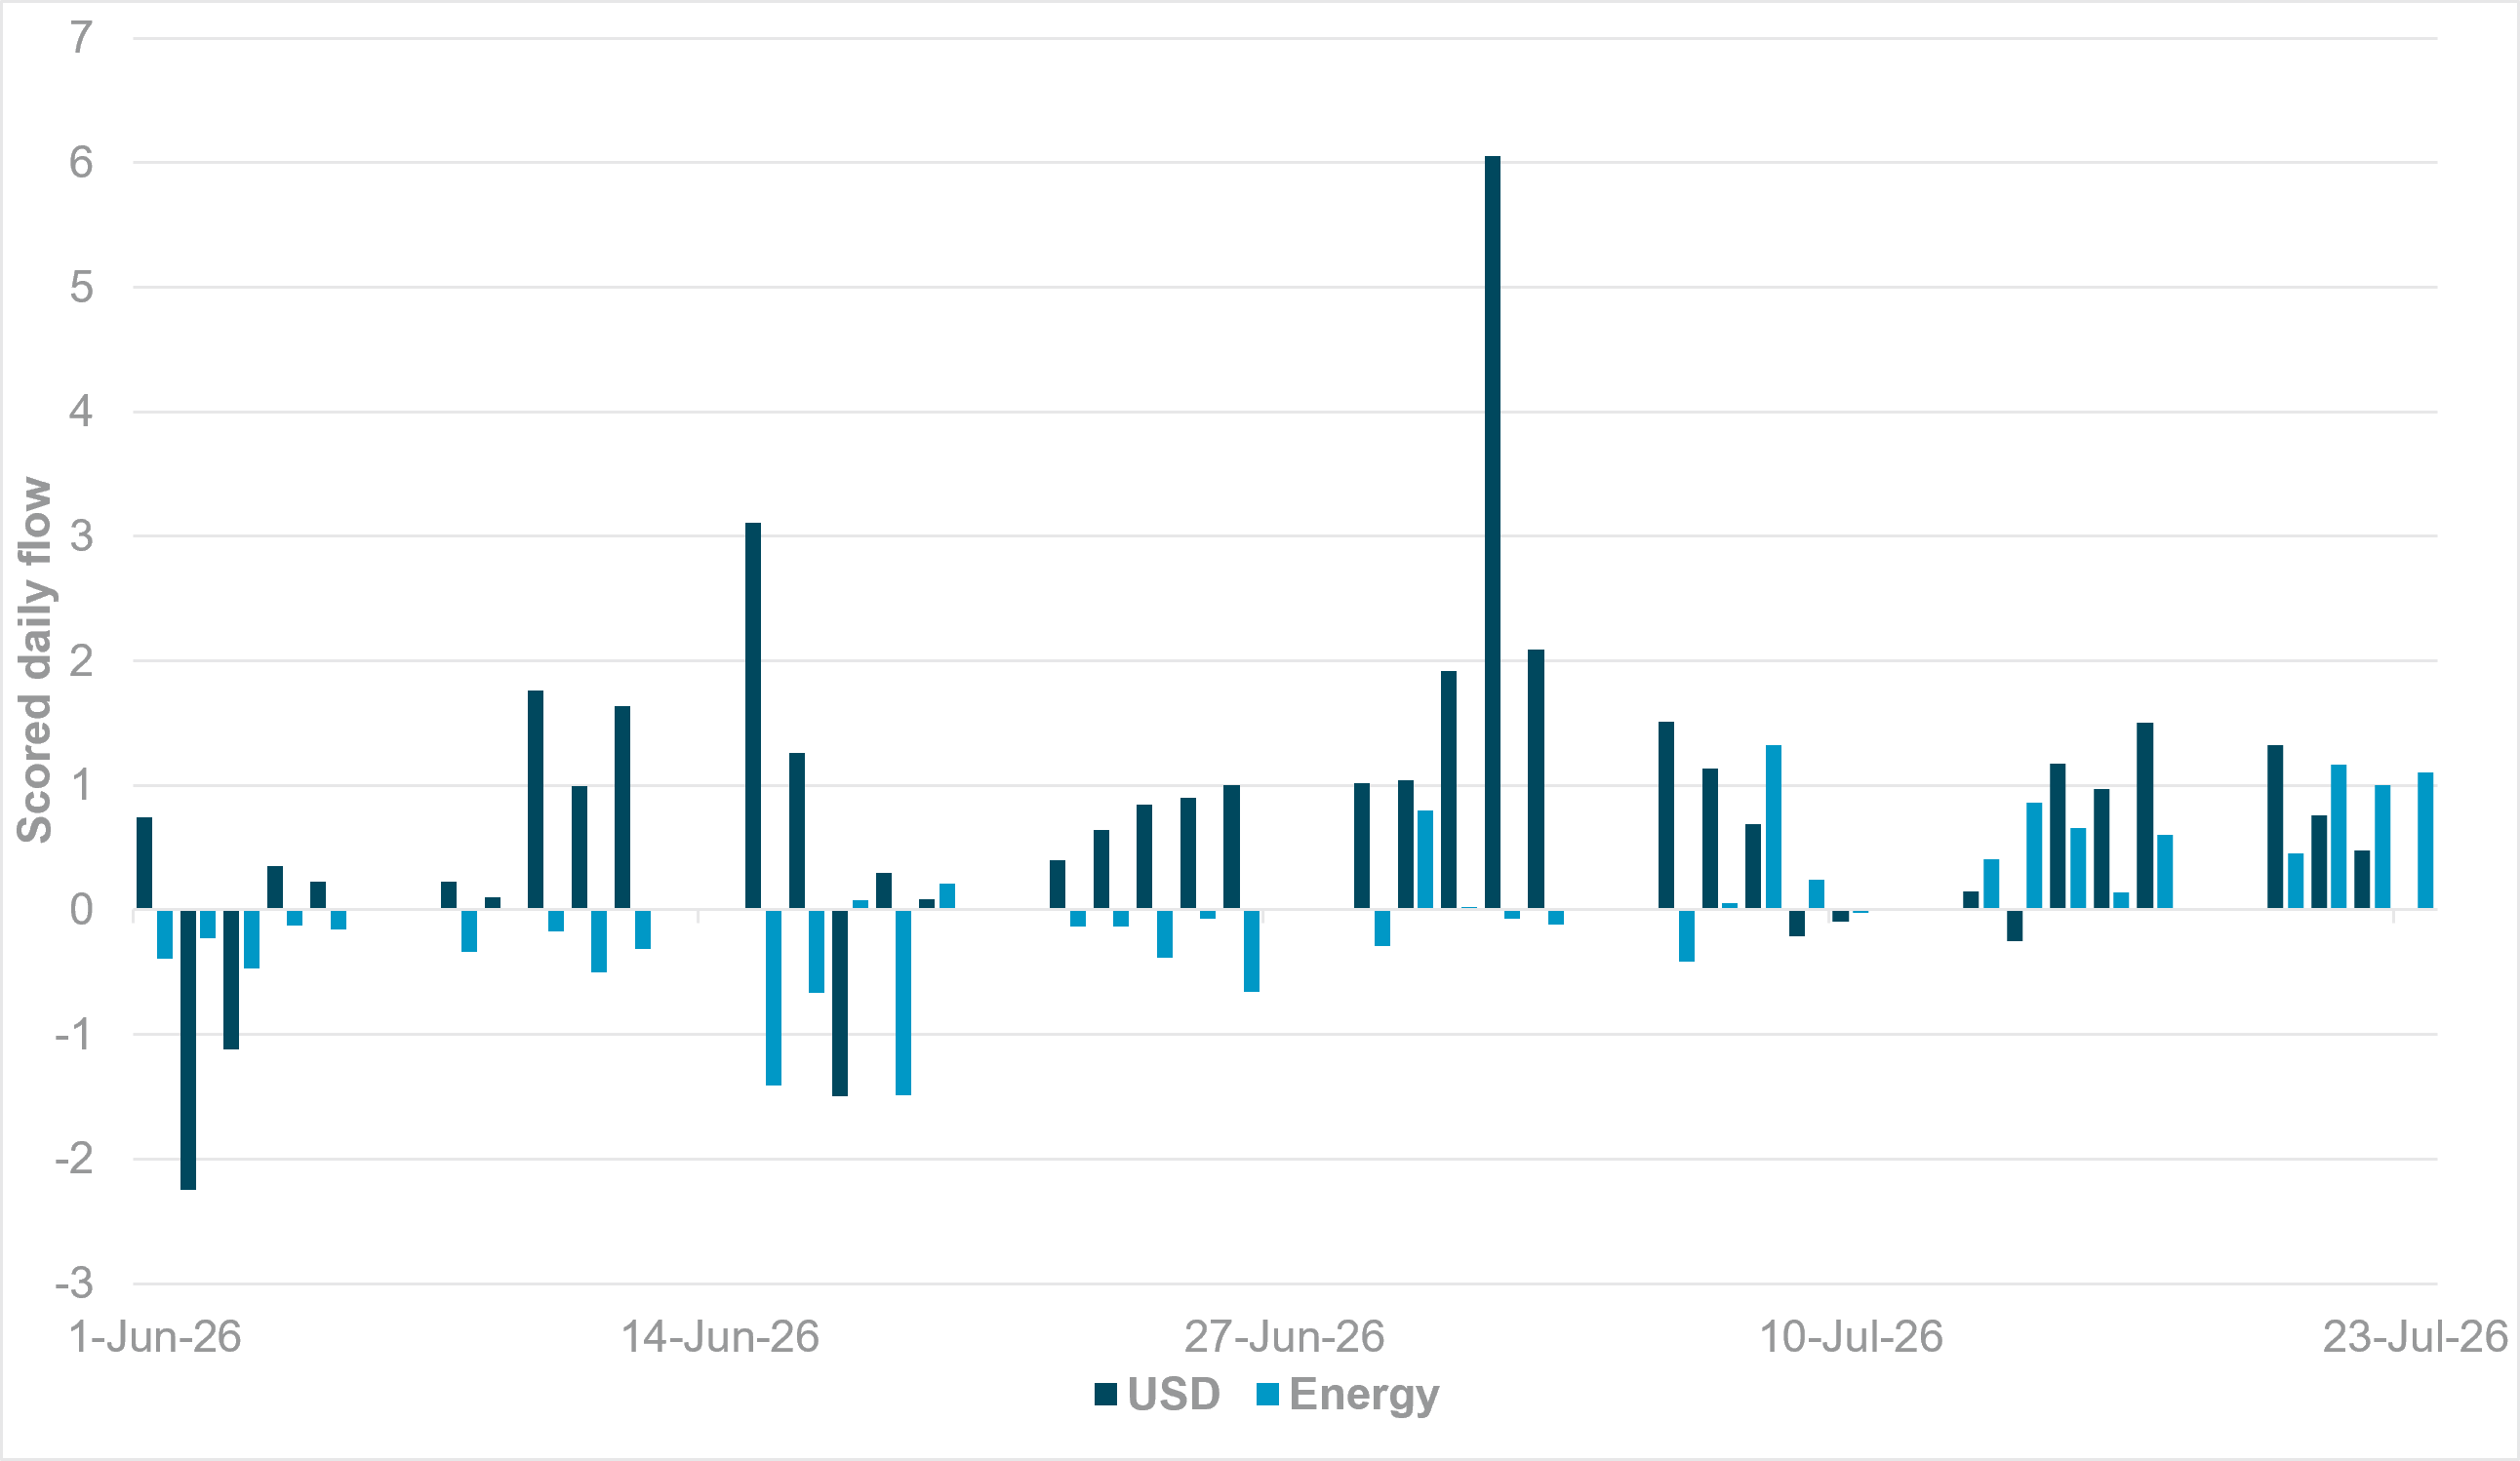
USD and energy main beneficiaries of current risk aversion
Source: BNY
Escalation risk is reinforcing a familiar hedge basket: cross-border USD demand is exceptionally strong, CHF remains the secondary safe haven, and energy, utilities, cash and front-end sovereigns are attracting flows. NOK has failed to benefit from higher oil, while materials remain under pressure. Crowding is the main risk, leaving USD and CHF vulnerable to de-escalation or a turn in rate expectations.
The dollar was the clearest beneficiary in the first phase of the conflict, supported by risk aversion and the U.S. terms-of-trade advantage as a major oil producer. Since the second week of July, momentum has shifted back toward USD buying, although flows have not reached surge levels. Escalation will affect the dollar mainly through rate expectations, and markets are holding long positions ahead of this week’s Fed decision.
Similarly, global energy equities have seen the biggest flow shift since escalation resumed. Falling oil prices first drove a sharp reduction in overheld positions and accelerated selling, but flows reversed completely in July as Gulf risks rebuilt. Buying intensity has risen alongside the gradual escalation, lifting the rolling two-month average back into marginally positive territory. With global energy positioning now substantially lower than before the sell-off, there’s room for a material rebuild in holdings if Gulf tensions persist or intensify.
Pause: Markets have been given a welcome pause after the U.S. and Iran refrained from further direct strikes over the weekend. Oil prices are lower, easing the immediate inflation and growth shock and supporting bonds and equities. The relief is conditional rather than conclusive: shipping through Hormuz remains constrained, while continued threats to regional energy infrastructure leave supply risk elevated.
Asia relief: Lower oil has helped Asia’s energy-importing markets, while the successful Shanghai debut of ChangXin Memory Technologies added a powerful technology catalyst. The listing of China’s largest memory-chip maker reinforced confidence in the region’s AI and semiconductor complex, lifting sentiment across China, Korea and Japan. Japan’s domestic backdrop is less comfortable. Inflation is becoming a political as well as a monetary constraint, with Prime Minister Sanae Takaichi pledging stronger action as polling shows living costs weighing on her popularity. The regional rally, therefore, reflects immediate relief from energy prices and optimism around technology, rather than a clear improvement in underlying macro conditions.
Policy pause: Monetary policy remains in flux. One sharp fall in oil is not enough to remove hikes from pricing after weeks of elevated energy costs and renewed inflation concerns. ECB policymaker Peter Kazimir said overnight that one more increase is needed, underscoring central banks’ focus on second-round effects rather than a single day’s price move. Nonetheless, the trade-off remains difficult. The head of Germany’s Ifo Institute acknowledged that a hike would be “problematic” for Germany, even if justified for the euro area.
Data pause: U.S. durable-goods orders are due today. The core capital-goods components will matter more than the volatile headline as markets assess whether investment demand can withstand higher rates and energy costs. With the Fed in blackout ahead of Wednesday, any material surprise could carry more weight than usual for front-end yields and the dollar.
Bottom line: The pause is welcome, but not yet durable. Expect nervy trading as markets wait for more news from the Middle East, Wednesday’s Fed decision and the major technology earnings reports due this week.
The top U.S. military commander in the Middle East advised halting the bombing campaign around the Strait of Hormuz, saying it had reached the limit of its effectiveness and most designated targets had already been hit. CENTCOM Adm. Brad Cooper’s recommendation, along with concerns from other advisers, helped shape President Trump’s decision to pause U.S. strikes against Iran for the first time in two weeks. Cooper said the campaign had significantly degraded Iran’s ability to attack ships and that without a move back to major combat operations, there was little point continuing the existing air campaign. Separately, Joint Chiefs Chairman Gen. Dan Caine warned that shortages of air defense interceptors could strain protection of U.S. forces and allies. U.S.-Iran talks remain ongoing, while Washington and London discuss a coalition to secure the strait. Brent -6.128% to 90.85, WTI -5.633% to 84.28, Omani Crude -9.498% to 88.24, Dubai Crude -1.48% to 78.929.
Japanese Prime Minister Sanae Takaichi said stronger economic growth and improved competitiveness would reinforce market trust in the yen, even as her government faces pressure from rising living costs and sliding approval ratings. Speaking in parliament, she stressed that exchange rates are set by markets and the Bank of Japan remains responsible for monetary policy, although it must coordinate closely with the government on economic policy. The remarks came as the yen has weakened to multi-decade lows and Takaichi’s popularity has fallen, with recent polls showing growing public dissatisfaction over inflation. She also faces delays on a proposed food sales tax cut, while market concerns over fiscal expansion continue to push bond yields higher. Nikkei +0.5% to 64,931, USDJPY -0.171% to 163.55, 10y JGB -3bp to 2.786%.
ECB Governing Council member Peter Kazimir said the ECB will likely need at least one more interest rate hike to keep inflation risks contained, even if tensions in the Middle East ease somewhat. He warned that a further escalation would justify even tighter policy in coming quarters and said the central bank must focus on the impact of higher energy costs on prices across the euro area. Kazimir added that the full inflationary effect of the energy shock hasn’t fully emerged yet and that second round effects can build quietly before becoming costly to reverse. His comments strengthened expectations for a 25bp hike in September. Euro Stoxx 50 +0.78% to 6,330, EURUSD +0.229% to 1.1396, BBG AGG Euro Government High Grade EUR 0bp to 3.461%.
Singapore’s Monetary Authority tightened policy again in July, raising the rate of appreciation of its policy band “very slightly” while leaving the width and center unchanged. The move builds on the April tightening and reflects heightened uncertainty, with the MAS saying it stands ready to curb excessive volatility. Policymakers expect core inflation to pick up from July and remain elevated as external price pressures persist and pass through more broadly to domestic consumer prices. MAS kept its core inflation forecast at 1.5%–2.5% for this year, noting medium-term price risks should moderate only from around mid-2027. The central bank also flagged a positive output gap, supported by above-trend growth and AI-related momentum, even as renewed Middle East tensions and higher oil prices threaten to lift inflation. STI +0.37% to 5,609, USDSGD +0.07% to 1.2897, 10y SGB +4.7bp to 2.461%.
With Bank Indonesia (BI) Governor Perry Warjiyo’s resignation, Senior Deputy Governor Destry Damayanti was appointed acting governor. The leadership change has increased near-term uncertainty for the rupiah. Warjiyo’s resignation comes as BI is shifting away from rate hikes toward macroprudential tools and more active FX intervention, making policy continuity a key market focus. Damayanti is expected to provide short-term stability and has said she will maintain rupiah stability, but the permanent appointment remains unclear. Leadership changes have historically triggered sharp repricing in IDR assets, with the 2025 finance minister reshuffle cited as a recent reminder. BI is likely to intensify FX operations and liquidity support to curb rupiah volatility during the transition. Overall, USDIDR is seen biased higher until investors gain clarity on the next governor and the policy direction. JCI -0.15% to 6,187, USDIDR -0.345% to 18,005, 10y IDGB +2.1bp to 7.375%.
U.S. June preliminary Durable Goods Orders is forecast to rise 1.5% m/m vs. -4.5% m/m. Durable Goods ex Transportation is forecast to ease 0.9% m/m vs. 1.4% m/m.
U.S. June preliminary Cap Goods Orders Nondef Ex Air is forecast to ease 0.9% m/m vs. 1.4% m/m.
Cap Goods Ship Nondef Ex Air is forecast at 0.6% m/m vs. 0.1% m/m prior.
U.S. July Dallas Fed Manufacturing Activity is forecast at 2.0 vs. 0.0 prior.
U.S. Treasury sells $92bn 13-week bills, $79bn 26-week bills, $69bn 2y notes and $70bn 5y notes.
Mood: iFlow Mood narrowed further to -0.113, driven by stronger equity demand alongside continued steady buying of core sovereign bonds.
FX: GBP and CAD led currency outflows, while USD and CHF attracted the strongest inflows. Flows across APAC were mixed, while LatAm currencies remained biased toward outflows and EMEA currencies saw net inflows.
FI: Demand remained firm for major sovereign bonds and Chinese government bonds, while Peru and Poland recorded the largest sovereign bond outflows.
Equities: Demand for emerging market equities strengthened, led by LatAm and APAC, while G10 equities continued to see net selling.
“The object in war is to attain a better peace – even if only from your own point of view.” – B. H. Liddell Hart
“He will win who knows when to fight and when not to fight.” – Sun Tzu
Euro area monetary developments for June 2026 showed M3 growth rising to 3.3% y/y from 3.0% in May, while the three-month average remained at 3.0%. M1 slowed to 3.4% from 3.7%, but short-term deposits other than overnight deposits accelerated to 2.8% from 1.4%, and marketable instruments increased to 4.5% from 3.2%. On the credit side, adjusted loans to households were unchanged at 3.0% and adjusted loans to nonfinancial corporations stayed at 4.0%. Households deposit growth eased, while deposits from nonfinancial corporations picked up and the private sector remained the main support for M3. Euro Stoxx 50 +0.78% to 6,330, EURUSD +0.229% to 1.1396, BBG AGG Euro Government High Grade EUR 0bp to 3.461%.
German business confidence improved in July as the Ifo Institute reported a rise in its business climate index to 86.6 from 85.7 in June, marking a third straight monthly increase and coming in above market expectations for no change. The survey, based on around 9,000 monthly responses from companies, showed firms were somewhat less pessimistic about the outlook despite continued uncertainty linked to tensions in the Persian Gulf and volatile oil prices. The institute said expectations for business activity improved, but the overall reading remained weak after the sharp drop seen following the outbreak of war in Iran. Even with the recent recovery, sentiment is still far below normal levels and suggests the rebound may prove fragile. DAX +1.11% to 25,376, EURUSD +0.229% to 1.1396, 10y Bund -3.7bp to 3.135%.
Japan’s May 2026 leading indicators were revised slightly lower from the flash estimate. The Composite Index (CI) leading index was 116.5, down from 116.8 in the flash, while the coincident index was revised to 117.9 from 118.5 and the lagging index to 111.4 from 111.5. Despite the small downgrades, the Cabinet Office said the coincident index “shows improvement,” keeping the overall assessment unchanged. The revision reflected changes to several component series, including updated inventory ratios, machine orders, industrial production, and retail and wholesale sales. The leading index remains on an improving trend, though its m/m rise slowed further. The coincident index also eased slightly from April after a strong gain, while the lagging index edged down modestly. Nikkei +0.5% to 64,931, USDJPY +0.196% to 163.51, 10y JGB -3.4bp to 2.782%.
China’s industrial enterprise profits rose strongly in January–June 2026, with profits of industrial firms above designated size up 18.7% y/y (from +15.4% y/y in Q1, implied by the text), supported by faster revenue growth and improving industrial prices. Revenue increased 6.5% y/y, while June industrial profits alone rose 15.1% y/y. By sector, mining profits grew 33.5%, manufacturing 20.1%, and utilities fell 4.2%. Electronics was the standout, with integrated circuit manufacturing profits surged 2,580% y/y, while the electronics industry overall made 96.9% y/y in profit. Raw materials manufacturing also jumped 71.7%, helped by nonferrous metals and chemicals. The statement said unit costs continued to decline, with costs per bn yuan of revenue falling and profit margins improving to 5.70%. It warned, however, that external uncertainty, commodity volatility, weak demand and funding pressure remain key headwinds. CSI 300 +1.11% to 4,701, USDCNY +0.065% to 6.7667, 10y CGB 0bp to 1.724%.
South Korean President Lee Jae Myung ordered officials to keep oil price caps in place until oil price uncertainty “completely recedes,” citing renewed Middle East tensions and the risk of prolonged volatility. He also told authorities to maintain related measures, including oil tax cuts, and to prepare additional steps if conditions worsen. Lee emphasized protecting vulnerable groups such as truck drivers, heavy equipment operators, farmers and migrant workers from higher fuel costs, and urged tighter monitoring for market irregularities, including cornering and price-fixing in essential goods. Separately, he highlighted his Brazil and San Francisco visits, calling for stronger AI cooperation with global tech firms and follow-up measures to turn announced projects into economic benefits. He also said South Korea should expand diplomacy with South American countries amid shifts in the international order. KOSPI +0.97% to 6,756, USDKRW -0.732% to 1469.75, 10y KTB +4.8bp to 4.445%.
In South Korea, pension funds, led by the National Pension Service (NPS), have turned net buyers in the KOSPI in July so far, with a net purchase of ₩68.4bn from early this month to the 24th, after persistent net selling from January to June. The shift follows NPS resuming domestic asset rebalancing, easing fears of a large “sell-off bomb.” Analysts said the recent KOSPI correction likely helped reduce domestic stock weights naturally, limiting the need for aggressive selling. NPS said a large-scale disposal in a short period is impossible, while the health ministry said it will monitor rebalancing to minimize market impact. Sector-wise, SK Hynix was the biggest net buy, while SK Square led net selling.
Hong Kong external merchandise trade statistics for June 2026 showed a sharp rise in both exports and imports. Total exports of goods jumped 53.4% y/y to HK$641.1bn, while imports climbed 45.4% to HK$693.0bn, leaving a visible trade deficit of HK$52.0bn. For the first half of 2026, exports rose 39.1% and imports increased 40.6% from a year earlier, with a deficit of HK$294.6bn. On a seasonally adjusted quarterly basis, Q2 exports and imports gained 13.8% and 9.0%, respectively. The government said exports surged on strong global demand for AI-related electronic products, especially to Asia and the U.S. Hang Seng +1.02% to 25,217, USDHKD -0.004% to 7.8423, 10y HKGB -1.2bp to 1.417%.