Market Movers: Patience
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoff Yu
Time to Read: 6 minutes
Funders/quality names struggling for traction
Source: BNY
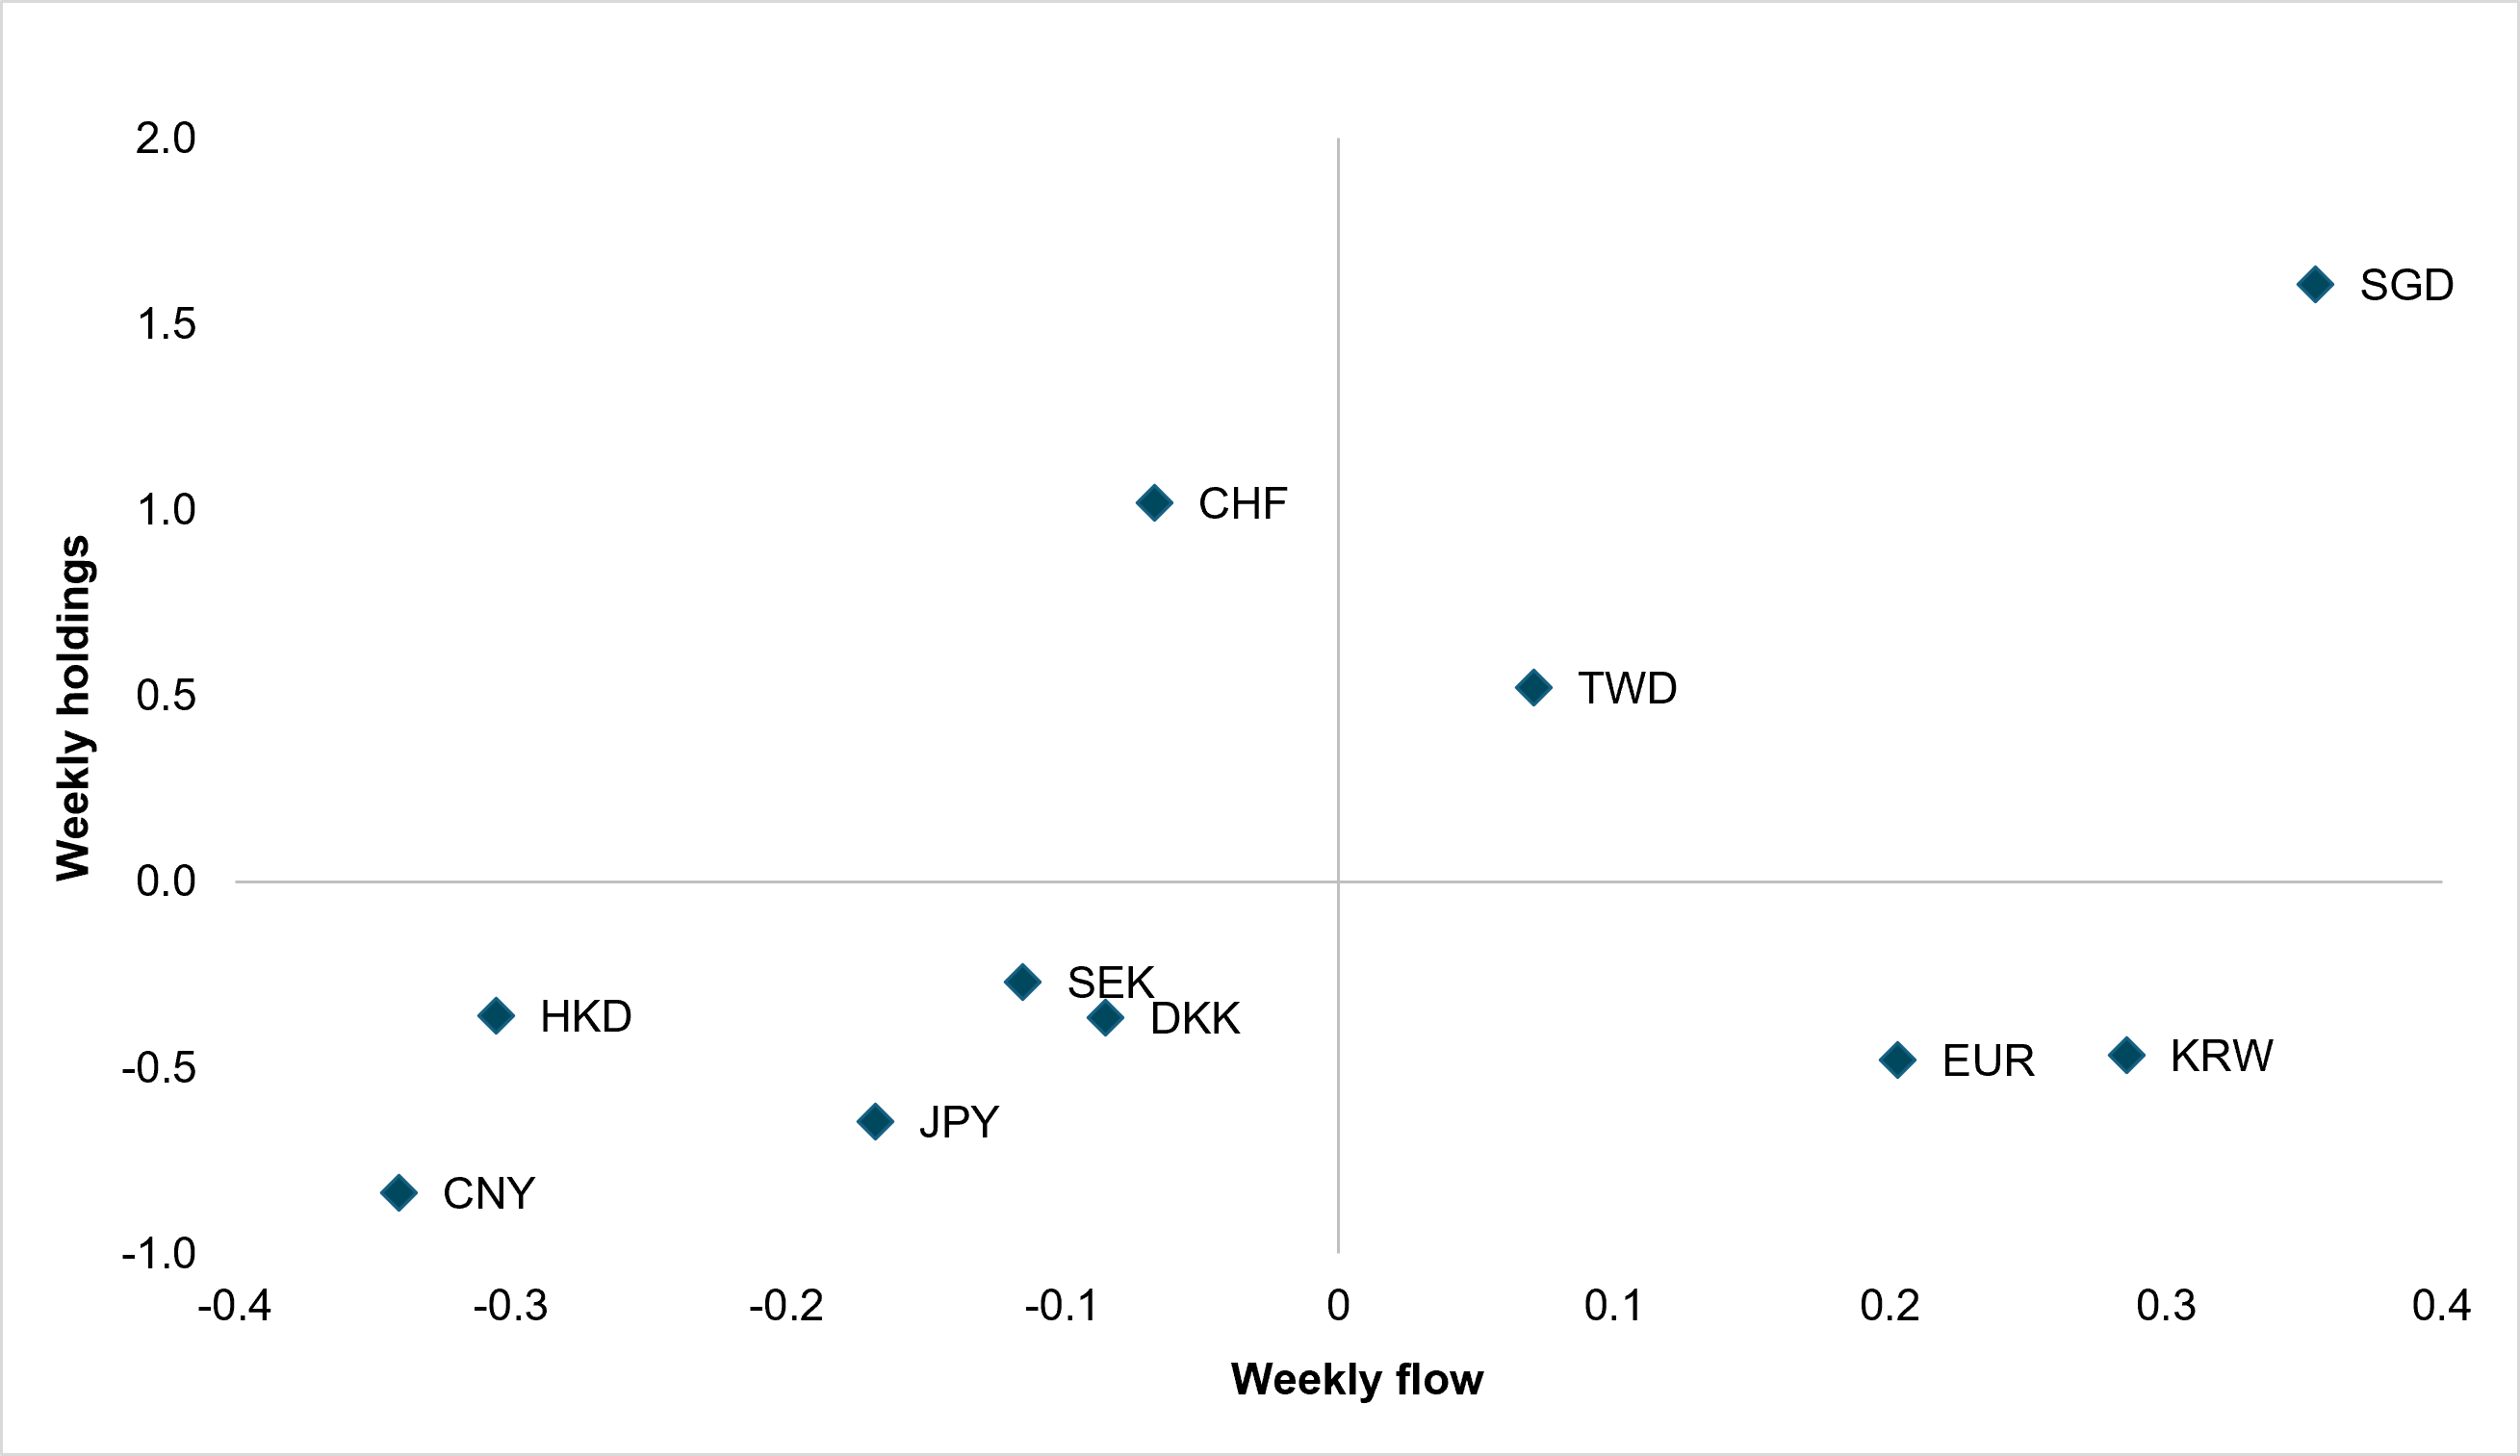
Funder interest is softening. Markets are talking more about safety, quality and credibility, but flows are not following. Alternative funders have failed to attract strong cross-border demand even after the Treasury buyback announcement. Over the past week, SGD was the best-bought “quality” currency, despite already being well overheld, but its flow score remained below 0.4. CHF and JPY were net sold, while most other solid funders remain underheld and subject to outflows. The Treasury announcement did little to trigger a broad rotation away from the dollar.
The monthly picture is firmer, but momentum has faded. SGD’s monthly flow average remains above its weekly reading, while CHF is still net bought over the month. JPY and CNY aside, most currencies retain better directional flow profiles over the longer horizon. This suggests the Treasury announcement mattered far less for safe-haven positioning than the July FOMC meeting. Investors were already positioned for dollar weakness; the buyback news provided a final extension, and profit-taking followed. The dollar, therefore, remains the most reliable defense against a correlated bond and equity selloff. CHF, SGD and EUR offer some protection, but none has matched USD consistency. Reserve status and superior U.S. real yields remain the key advantages, although further real-rate erosion would challenge that framework.
AI patience: Risk sentiment is stable, but Nvidia’s results will test how long investors will wait for AI returns. Funding demands remain formidable: SoftBank is reportedly considering a $10–20bn bond sale to refinance borrowing tied to its OpenAI investment. The scale underscores the AI buildout's funding burden and its potential spillover into credit and rate volatility.
Trade patience: U.S.-Canada confrontation still leaves room for negotiation. Washington is considering further penalties after Canada’s retaliation, although formal talks are currently suspended. We still see strong incentives to find a settlement: repeated U.S.-China détentes show that severe escalation and the search for an eventual deal can coexist.
Inflation patience: Central banks are showing very different tolerance for persistent inflation. ECB heavyweight Isabel Schnabel said further tightening will be “necessary” and warned against waiting for second-round effects to appear in wages. Meanwhile, Britain’s energy price cap will rise 4% from October as wholesale energy pressures persist. Expect the cost of living to sharpen the political debate and fiscal outcomes for months to come.
Ahead today: U.S. PCE is the immediate credibility test. Consensus points to modest monthly gains, around 0.1% headline and 0.2% core, with no meaningful worsening in the annual trend. Q2 GDP is expected to be confirmed at 1.5% q/q annualized. An upside surprise in inflation would increase the pressure on U.S. Fed Chair Kevin Warsh ahead of Friday’s Jackson Hole speech. With fiscal impulse elevated globally, any case for easier policy needs careful justification. Markets can be patient, but not indefinitely.
ECB Executive Board member Isabel Schnabel said further rate hikes will be necessary because inflation risks remain tilted to the upside with euro area growth proving more resilient than expected. She argued that inflation is likely to remain above 2% for an extended period as high energy costs persist, with gas prices and low storage levels adding to the risks. Schnabel warned that waiting for these pressures to feed into wages would leave the ECB behind the curve and could ultimately require more aggressive tightening. She also pointed to stronger fiscal support, higher defense spending, AI-related investment and improving sentiment indicators as reasons for greater confidence in the growth outlook. The amount of further tightening will depend on incoming data. Euro Stoxx 50 +0.11% to 6463, EURUSD -0.035% to 1.1671, BBG AGG Euro Government High Grade EUR -4.4bp to 3.47%.
The U.S. is considering further trade penalties against Canada after Ottawa announced dollar-for-dollar retaliation to new American tariffs, raising the risk of a broader bilateral trade conflict. Canada will double counter-tariffs on U.S. steel and aluminum to 50% and impose new 50% duties on products including dairy, furniture, clothing and electronics, affecting around USD 20bn of annual U.S. exports. Washington is weighing higher tariffs and other measures in response, having already threatened 50% auto tariffs on Canada from January. The dispute follows the collapse of recent trade talks and marks a sharp deterioration in relations. The escalation could also create domestic political pressure in U.S. manufacturing states that are heavily exposed to Canadian retaliation. TSX 60 Future -0.06% to 2165, USDCAD +0.152% to 1.386, 10y CGB -5.9bp to 3.623%.
Iran and Oman discussed a temporary joint shipping corridor in the Strait of Hormuz, with both sides aiming to improve safe navigation and potentially move toward a permanent administration arrangement for the key oil transit route. Oman’s foreign minister said talks with Iran were constructive and that practical measures to restore safe passage could be announced soon. The two countries also discussed a mine-clearing mission in the strait, which appears to contradict President Donald Trump’s claim that mines had already been removed. The talks follow heightened tensions around Hormuz, including recent attacks on vessels and U.S. warnings that it will sanction any entity doing business with Iran. Oman said discussions with regional partners will continue in support of peace, stability and freedom of navigation. Brent -2.405% to 86.45, WTI -2.599% to 80.22, Omani Crude -6.779% to 89.11, Dubai Crude -1.071% to 89.139.
Federal Reserve Bank of Richmond President Tom Barkin said rising U.S. public debt will eventually face a “reckoning,” though the timing is impossible to predict. He warned the government can keep borrowing only as long as investors continue to buy Treasurys, noting a risk of pushback if confidence weakens. Barkin also said July’s Fed rate decision was a “close call,” with officials opting to wait for more economic data before the September 15-16 policy meeting. He reiterated that inflation appears to be easing, supporting a steady-rate stance for now, but said further rate hikes could still be needed if price pressures become entrenched. Barkin added that tariff uncertainty, including the Canadian dispute, is complicating the outlook for prices and growth. S&P Mini -0.1% to 7685, DXY +0.052% to 98.966, 10y UST +2bp to 4.649%.
U.S. July Personal Income is forecast to hold at 0.2% m/m vs. 0.2% m/m prior.
U.S. July Personal Spending is forecast to ease to 0.1% m/m vs. 0.3% m/m. Real Personal Spending is forecast to ease to 0.0% m/m vs. 0.4% m/m.
U.S. July PCE Price Index is forecast at 0.1% m/m, 3.6% y/y vs. -0.1% m/m, 3.7% y/y in June. Core PCE Price Index is forecast at 0.2% m/m, 3.3% y/y vs. 0.1% m/m, 3.3% y/y in June.
U.S. July preliminary Durable Goods Orders is forecast to hold at 0.5% m/m. Durable Goods ex Transportation is forecast to ease to 0.6% m/m vs. 0.7% m/m.
U.S. July preliminary Cap Goods Orders Nondef Ex Air is forecast to ease to 0.7% m/m vs. 1.2% m/m. Cap Goods Ship Nondef Ex Air is forecast to ease to 1.0% m/m vs. 2.0% m/m.
U.S. Q2 GDP is forecast to hold at 1.5% q/q. Q2 Personal Consumption is forecast to hold at 3.2% q/q. Q2 GDP Price Index is forecast to hold at 6.2% q/q. Q2 Core PCE Price Index is forecast to hold at 3.4% q/q.
U.S. Treasury sells $72bn 17-week bills, $28bn of 2y FRN reopening and $70bn of 5y notes.
Mood: iFlow Mood narrowed to -0.095 as demand for core sovereign bonds eased, while global equity buying remained steady.
FX: Currency flows were moderate and mixed across G10 and EMEA, with buying in LatAm offset by selling in APAC. COP and PEN led inflows, while AUD and CNY saw the clearest outflows.
FI: U.S. Treasurys, Eurozone, Canadian and Indonesian government bonds attracted the strongest inflows, while selling focused on LatAm, Chinese and New Zealand government bonds.
Equities: Equities were broadly sold across G10, APAC and LatAm, while EMEA attracted better demand. Colombia and Poland led inflows, while Canada saw the strongest selling.
“Time is your friend; impulse is your enemy.” –John C. Bogle
“The investor’s chief problem, and even his worst enemy, is likely to be himself.” – Benjamin Graham
Sweden's Producer Price Index for July rose 0.1% m/m and 6.4% y/y, with the annual rate easing from 7.4% in June. Domestic producer prices fell 1.1% m/m but remained 6.6% higher y/y, while export prices rose 1.3% m/m and 6.1% y/y. Import prices increased more sharply, up 2.4% m/m and 8.6% y/y, supported mainly by higher crude oil and refined petroleum prices. Energy remained the dominant annual driver, with energy-related producer prices up 26.0% y/y, while PPI excluding energy rose 3.5%. Consumer goods prices fell 1.7% y/y, while capital goods increased 1.6%, indicating softer underlying pressure outside energy. OMX -0.14% to 3314, EURSEK +0.377% to 11.0764, 10y Swedish GB -0.9bp to 3.009%.
Japan’s Services Producer Price Index for July 2026 rose 3.6% y/y (3.4% in June), nearing the highs in June 2024 (3.65%). Excluding international transportation, Services PPI gained 3.1% y/y (3.1% in June) and 0.3% m/m. Among major drivers, transportation and postal activities accelerated to 6.4% y/y from 5.6%, led by ocean freight transportation and domestic air passenger transportation. Leasing and rental stayed firm at 11.6% y/y. Information and communications rose 2.8% y/y, while real estate services increased 2.2% y/y. Advertising services remained negative at -1.6% y/y, dragged by television and radio advertising. The report highlights continued price pressure in transport-related services and leasing, partly offset by weak advertising. Nikkei +0.62% to 66262, USDJPY -0.107% to 159.02, 10y JGB -0.1bp to 2.902%.
Australia’s CPI rose 3.5% y/y in July 2026, easing from 3.8% in June. Monthly inflation was 1.0% m/m. Housing was the biggest annual contributor, up 5.0%, driven by new dwelling costs rising 5.7% y/y as builders passed on higher materials and labor costs. Food and non-alcoholic beverages increased 3.2% y/y, led by meals out and takeaway at 4.5% y/y. Transport inflation picked up to 1.6% y/y from 0.1% in June, while automotive fuel rose 7.5% m/m after three straight monthly declines, reflecting higher global oil prices and the partial unwinding of fuel excise relief. Recreation and culture rose 2.6% y/y. Trimmed mean inflation was unchanged at 3.6% y/y. ASX -0.02% to 5868, AUDUSD +0.252% to 0.7181, 10y ACGB +1bp to 5.032%.
Australia’s Westpac–Melbourne Institute Leading Index for July improved slightly, with the six-month annualized growth rate rising to -0.2% from -0.4% in June. The index remains below trend for a seventh straight month, but the signal is now only marginally negative, suggesting the economy is soft rather than outright weak. The main drags continue to come from financial conditions and the labor market, while consumer sentiment and commodity prices also weigh modestly. Offsetting support comes from dwelling approvals and U.S. industrial production. Westpac says GDP growth is likely to remain positive overall in coming quarters, though per capita growth may stay close to flat. The report also notes that the main drag from the yield spread should ease as the RBA shifts from active tightening to a hawkish hold, potentially allowing momentum to improve slightly. ASX +0.03% to 5871, AUDUSD +0.21% to 0.7178, 10y ACGB +1bp to 5.032%.
Australia’s June quarter 2026 preliminary construction data showed mixed momentum. Total construction work done fell 2.1% q/q to $82.5bn (after rising 1.0% q/q in March quarter 2026), as a sharp decline in engineering work outweighed gains in building. Engineering work done dropped 6.0% q/q to $36.7bn and was 5.1% y/y lower. In contrast, building work done rose 1.3% q/q to $45.8bn (after 0.9% q/q previously), supported by residential construction up 1.7% q/q and non-residential up 0.5% q/q. On a trend basis, total construction increased 0.7% q/q, suggesting underlying activity remained positive despite the quarterly headline decline.
South Korea August 2026 Composite Business Sentiment Index (CBSI) for all industries rose to 99.6 (+1.1 points m/m), with the next-month outlook also improving to 99.6 (+3.1). Manufacturing CBSI increased to 103.8 (+0.6 m/m), while the outlook rose to 102.5 (+2.0), supported by better financial conditions and firmer expectations for production and new orders. Non-manufacturing CBSI climbed to 96.7 (+1.5 m/m), with outlook improving to 97.6 (+3.9), helped by improved sales, profitability and financial situation. The Economic Sentiment Index (ESI), combining business and consumer surveys, advanced to 99.4 (+1.5 m/m), while the cyclical component also improved to 96.9 (+0.4). KOSPI +0.97% to 6808, USDKRW +0.058% to 1384.85, 10y KTB -0.9bp to 4.318%.
South Korea’s retail sales rose 6.4% y/y in July, supported by summer vacation spending, stronger demand for delivery services, travel-related goods and popular imported fashion brands. Offline retailers increased 3.2%, with department stores and convenience stores extending their y/y gains for a 13th straight month. Department store sales jumped 17.9%, driven by imported fashion brands, vacation goods and air conditioners. Convenience store sales rose 1.1% even as foot traffic fell, thanks to higher spending per customer. Online sales climbed 8.5%, led by food delivery services, groceries and home appliances. Online platforms accounted for 60.8% of total retail sales.
Bank Indonesia Acting Chief Destry Damayanti is set to serve a full five-year term as governor from 2026 to 2031, once parliament approves her nomination. The move comes after lawmakers began her fit-and-proper test, and follows Perry Warjiyo’s abrupt resignation in late July, about two years before his second term ended. The decision removes uncertainty over whether Destry would only complete the remainder of Warjiyo’s term or start a fresh mandate. Market reaction was muted, with the rupiah and stocks little changed and the 10y government bond yield up 3 bp. The announcement is seen as reassuring for investors, as Destry is a longstanding BI deputy and veteran economist. If confirmed, she would become the first woman to lead Bank Indonesia since 1953. JCI -0.96% to 6439, USDIDR 0% to 17712, 10y IDGB +2.9bp to 7.041%.
Singapore's manufacturing output for July rose 6.8% y/y and 2.3% m/m on a seasonally adjusted basis, with growth excluding biomedical manufacturing stronger at 8.0% y/y and 0.8% m/m. Precision engineering led the annual expansion at 17.7%, supported by semiconductor equipment and precision components, while electronics rose 11.2% on sustained AI-related demand. Transport engineering increased 10.8%, helped by aerospace and land transport activity, while general manufacturing grew 4.9%. By contrast, biomedical manufacturing fell 5.3%, reflecting weaker medical technology exports and lower pharmaceutical output, while chemicals declined 10.6% amid plant maintenance, softer demand and feedstock disruptions. Overall manufacturing output was up 9.8% y/y in January-July. STI -0.08% to 5731, USDSGD +0.04% to 1.2699, 10y SGB -1.7bp to 2.3%.
The Bank of Thailand unanimously kept its policy rate unchanged at 1.00%, judging the current stance sufficiently accommodative to support a slow and uneven recovery. Policymakers said growth remains supported by technology and AI-related exports and investment. However, domestic demand is softer, with private consumption constrained by higher living costs and SMEs still facing weak credit conditions. Inflation is running below previous estimates, although headline inflation is expected to rise temporarily through early 2027 due to El Niño effects and gradual cost pass-through. Medium-term inflation expectations remain anchored. The central bank also highlighted risks from the Middle East conflict, trade barriers, SME loan quality and vulnerable households, while signaling that targeted financial measures remain preferable to broader easing for now. SET +0.6% to 1606, USDTHB -0.016% to 32.72, 10y TGN +0.3bp to 2.103%.