Market Movers: Patience
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Wee Khoon Chong
Time to Read: 5 minutes
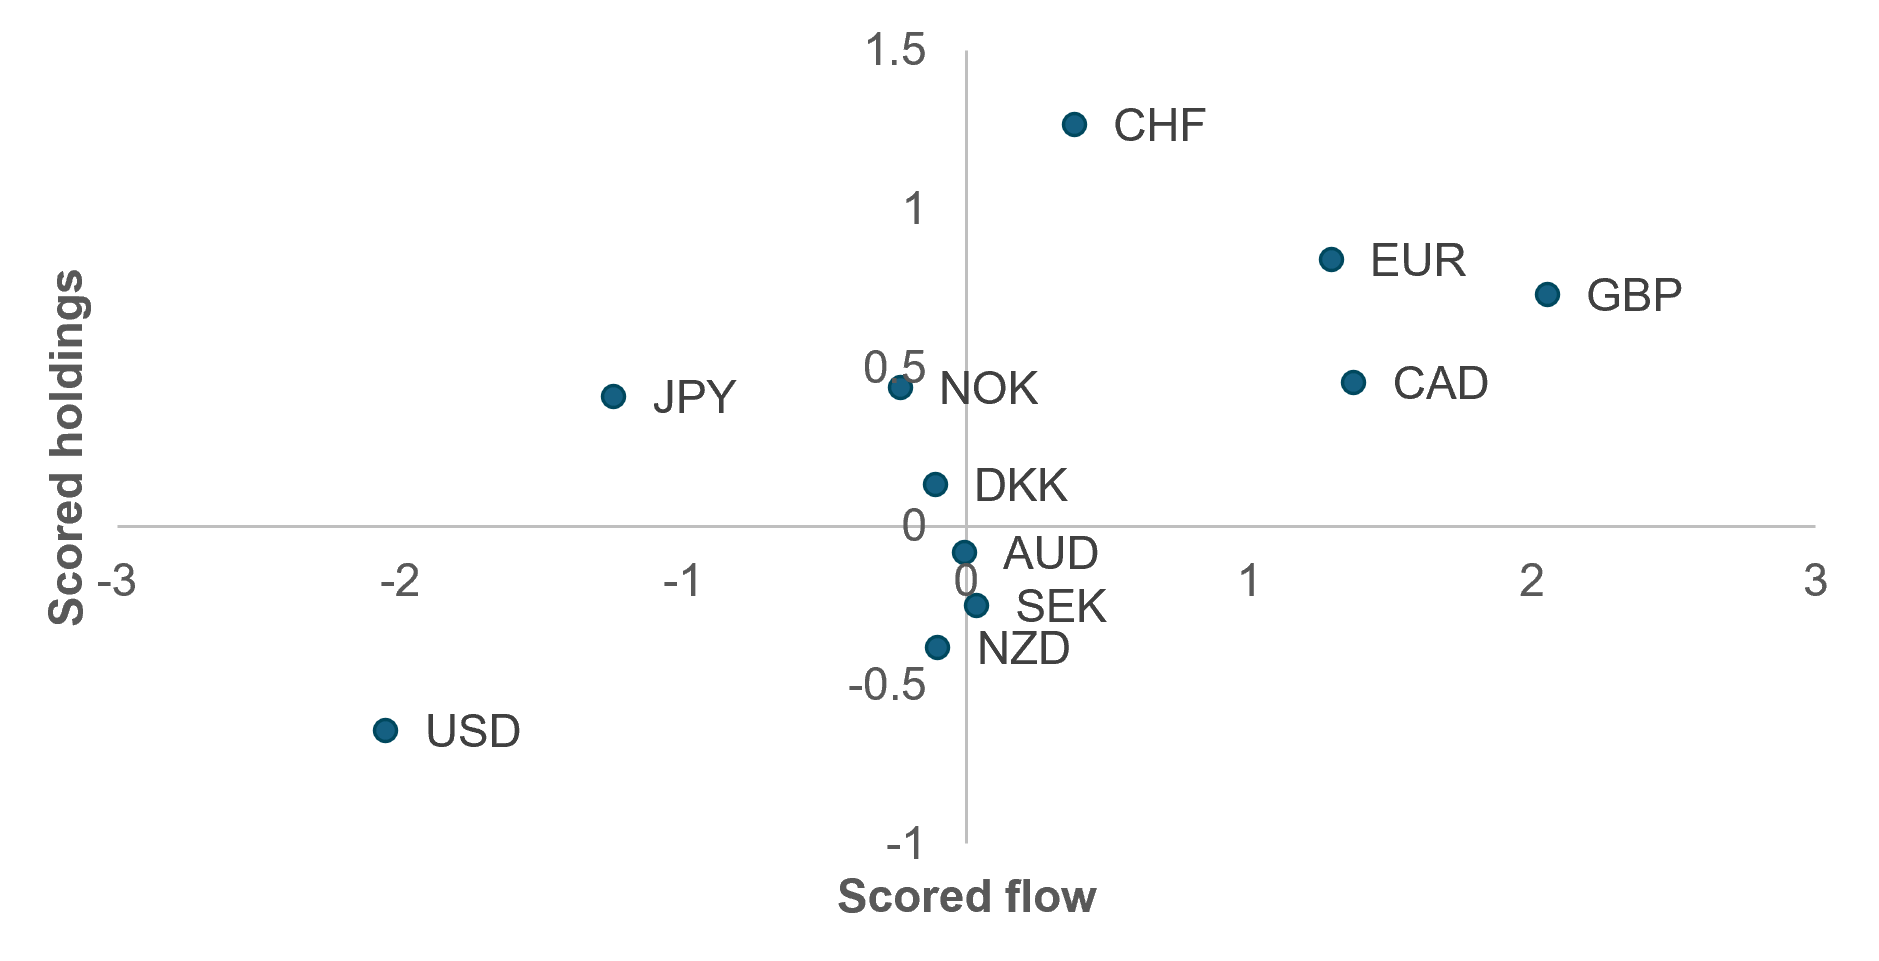
USD is the most underheld and most sold G10 currency
Source: BNY
Over the past week, USD has been the poorest-performing G10 currency as measured by iFlow scored holdings and scored flows. The dollar’s underperformance is partly attributable to the market’s perception that a September hike has become less likely. It is important to note that the iFlow snapshot does not include Friday’s July non-farm payrolls, which printed at -23k against a consensus of 80k. The employment miss was broad-based and accompanied by downward revisions, and the market further repriced Fed hike odds accordingly. Given that the USD weakness in the data precedes the payrolls shock, the softening in hike expectations had already begun to register in institutional positioning ahead of Friday’s release.
The rates market has absorbed the employment data, with the 2y Treasury yield inching up to 4.21% in the Asia session. Markets are now assigning a probability of just under 50% to a 25bp rate hike in September, down from 67% a week earlier. The reduced expectations of Fed tightening will likely continue to weigh on the dollar. Wednesday’s July CPI release carries a consensus forecast of 2.50% y/y for core inflation, against a prior reading of 2.60%; the m/m change in the core measure is expected at 0.20% versus a flat prior print. For USD, the asymmetry heading into the CPI announcement is pronounced: a strong showing, particularly in core services or shelter, would likely reverse the recent repricing and result in a sharp bid, given how aggressively hike odds have fallen. By contrast, a soft print or one that is in line with expectations would reinforce the current institutional positioning bias, keeping USD scored holdings low and encouraging continued outflows.
Rotation, not re-risking: The risk rebound remains uneven and increasingly selective. South Korean and Chinese tech remained under pressure, while Taiwanese equities continued to attract demand. Within EM equities, flows rotated out of energy and materials into consumer discretionary, financials and information technology.
China’s recovery remains fragile: Growth momentum is improving only gradually. Softer-than-expected July inflation has reinforced signs of weak domestic demand, while contracting PMIs strengthen the case for further policy support. Beijing’s latest easing of home-buying restrictions has lifted property sentiment, but a sustained recovery remains far from certain.
Long-end JGB pressure is building: Inflation risks and fiscal concerns have pushed long-end JGB yields toward the upper end of recent ranges. Markets are now pricing in roughly a 50% chance of a 25bp BoJ hike in September and a full hike by year-end.
Bottom line: Patience does not mean inactivity. Investors may wish to avoid low-conviction directional trades and focus on exploiting growing cross-market and sector dispersion. All eyes will be on the CPI release later in the week.
The BoJ’s July MPM Summary of Opinions stressed that financial conditions remain accommodative, with short-term real rates negative, bank lending still proactive and funding demand rising. Several members argued that the bank should keep the policy rate unchanged at this meeting to assess the lagged impact of the previous hike, but the overall tone favors further tightening. The report said underlying CPI inflation is approaching 2%, inflation expectations have recently risen and upside risks to prices deserve greater attention than before. The debate has shifted away from lifting inflation to 2% and onto preventing an overshoot. Members also warned that waiting too long could force faster, larger rate hikes later, risking a “double shock.” The bank intends to remain nimble, with the timing and pace of policy to be shaped by economic activity, prices, financial conditions, the Middle East, AI-related demand and foreign exchange developments. Nikkei +2.08% to 66970, USDJPY -0.586% to 158.69, 10y JGB +2.3bp to 2.828%.
Beijing has further relaxed home-buying curbs to support its weak property market, cutting the required period of income tax or social insurance payments for non-local buyers from two years to one. The new rules, which took effect on August 8, also extend access to purchases across the capital, including within the Fifth Ring Road, and raise caps on housing provident fund loans to support first-home demand. Additional top-ups are available for buyers in outer districts, green-certified homes and larger families. The move underscores authorities’ effort to stabilize home prices and cushion the broader economy; the property slump has weighed on household consumption and worsened the imbalance between strong industrial supply and weak domestic demand. The announcement adds to earlier easing as Beijing tries to contain a five-year housing downturn. CSI 300 +0.16% to 4702, USDCNY +0.027% to 6.7436, 10y CGB -0.4bp to 1.702%.
Indonesia’s President Prabowo Subianto has nominated Destry Damayanti as the sole candidate to become the next central bank governor. She is currently serving as interim governor after Perry Warjiyo’s sudden resignation late last month for personal reasons. Parliament has one month to approve or reject the nomination, though it has not rejected a sitting president’s nominee for governor since 2008. The move comes as investors watch Bank Indonesia’s leadership closely amid concerns over fiscal policy, central bank independence, market transparency and pressure to support the government’s growth ambitions. The rupiah strengthened on the news, hitting its highest level against the U.S. dollar since June 18. Bank Indonesia has already raised rates by 100bp this year and used measures to support capital inflows and the currency. JCI -0.69% to 6365, USDIDR +0.721% to 17762, 10y IDGB -3.9bp to 7.245%.
Central bank speakers: The Fed’s Beth Hammack appears on Yahoo Finance.
U.S. Treasury sells $92bn in 13-week bills and $79bn in 26-week bills.
Mood: iFlow Mood has narrowed, as steady demand for global equities offset softer buying of core sovereign bonds.
FX: USD, BRL and CNY saw the largest outflows, while MXN, GBP and SGD attracted the strongest inflows. JPY outflows persisted despite recent official intervention. Flows across the rest of the iFlow universe were light and mixed.
FI: Steady demand for major sovereign bonds, alongside buying of Indian and Polish government bonds.
Equities: Buying was concentrated in EMEA and EM APAC equities, led by South Africa, Poland and Taiwan. Within developed markets, flows were mixed, with selling focused on the U.K. and Europe and modest buying in the U.S.
“Patience is bitter, but its fruit is sweet.” – Jean-Jacques Rousseau
“Adopt the pace of nature: her secret is patience.” – Ralph Waldo Emerson
The Eurozone’s Sentix Economic Sentiment Index extended its recovery to a fourth straight month in August, rising 4.0 points to +0.9 as it returned to positive territory. The improvement was driven mainly by a sharp rebound in the current situation assessment, while expectations edged up only slightly to +10.3. Germany also showed further progress: expectations climbed to their highest level since February, and the current situation improved materially, though it remained deeply negative at -28.3. Globally, sentiment remained constructive, with the Sentix Global Aggregate up 1.4 points to +14.7, pointing to a broad-based recovery across most regions. Japan was the only major exception, failing to participate in the improvement. Euro Stoxx 50 +0.17% to 6535, EURUSD +0.026% to 1.1562, BBG AGG Euro Government High Grade EUR 0bp to 3.386%.
Dutch manufacturing output rose 4.6% y/y in June, easing from 6.8% in May. On a seasonally and working-day-adjusted basis, output fell 1.3% m/m. Growth was broad-based across nearly half the underlying sectors, led by machinery, which posted a 26.2% y/y jump and remained the strongest contributor. By contrast, repair and installation of machinery saw the steepest drop at -15.9%, while electrical and electronics, chemical products, food products, rubber and plastic products, transport equipment and metal products also weakened. Producer confidence improved in July, rising to 2.4 from 1.3 in June, the highest level in four years, driven mainly by less-negative views on order books. Confidence remained above its 20-year average of -1.4. AEX +0.06% to 1112, EURUSD +0.026% to 1.1562, 10y NGB +0.6bp to 3.227%.
The U.K.’s July KPMG/REC Report on Jobs showed a modest improvement in hiring conditions. Permanent placements stabilized after a 45-month decline, while temp billings rose for a fourth straight month at one of the fastest rates since early 2023. Temporary vacancies increased for the first time in two years, and the fall in permanent vacancies eased to a 22-month low. Pay growth strengthened for both starting salaries and temp wages, with temp pay at a 26-month high. Candidate supply continued to rise sharply, though at the slowest pace in five months, reflecting redundancies and weak job opportunities. By region, London and the Midlands saw renewed gains in permanent hiring, while temp billings were led by the North. Sector demand remained mixed, with nursing/medical/care firmer while retail, and hotel and catering were weaker. FTSE 100 -0.25% to 10873, GBPUSD +0.089% to 1.3503, 10y gilt +0.4bp to 4.925%.
China’s CPI rose 0.5% y/y in July, softening from 1.0% y/y in June, and fell 0.1% m/m. The y/y gain was again led by non-food prices (+0.9%) and services (+0.7%), while food prices fell 1.5% and continued to drag on inflation. Within food, pork prices dropped 13.3%, offsetting gains in eggs, while fresh fruit and vegetables also weighed on the basket. On a m/m basis, lower transport costs, especially gasoline, and weaker fresh fruit prices pushed CPI down, partly offset by higher prices for pork and seasonal summer travel-related services. Core inflation excluding food and energy rose 0.9% y/y. Overall, inflation remained mild, with the headline y/y rate easing mainly because gasoline price gains faded. CSI 300 +0.16% to 4702, USDCNY +0.027% to 6.7436, 10y CGB -0.4bp to 1.702%.
Chinese PPI fell 0.7% m/m in July, with the decline widening by 0.4 percentage points m/m. The drop was driven by imported price pressures in upstream industries, including oil extraction, refined petroleum products and organic chemical raw materials, alongside seasonal weakness in construction-related sectors and lower hydropower and wind power prices. Offsetting this, prices rose in areas linked to industrial upgrading and consumption upgrading, such as intelligent drones, carbon materials, shipbuilding, smart home devices and skincare products. On a y/y basis, PPI rose 3.5%, easing by 0.6 percentage points from the previous month. The slower annual increase reflected broad moderation in several resource and metals sectors, even as coal mining, electrical machinery and electronics remained strong.
Japan’s balance of payments for June turned to a current account deficit of ¥92.3bn, vs. a ¥1.374tn surplus a year earlier, as the primary income surplus narrowed sharply. Trade and services also swung to a ¥363.7bn deficit, with the trade balance at a ¥135.2bn deficit. Exports rose 16.3% y/y to ¥10.48tn, but imports climbed faster, up 24.3% y/y to ¥10.62tn, pushing trade back into the red. The services deficit widened to ¥228.5bn, reflecting a smaller travel surplus. Primary income remained in surplus at ¥380.1bn, though it was down markedly y/y. Financial account inflows showed a ¥965.8bn net increase in assets, supported by strong portfolio investment and direct investment, while other investments posted a large net outflow. Nikkei +2.08% to 66970, USDJPY -0.586% to 158.69, 10y JGB +2.3bp to 2.828%.
Japan’s Economy Watchers Survey for July showed a modest improvement in sentiment. The current conditions Diffusion Index (DI) rose 1.7 points m/m to 45.7, up for a third straight month, as household, corporate and employment-related measures all improved. The outlook DI edged up 0.1 points m/m to 45.8, with corporate and employment-related readings higher while household-related sentiment was unchanged. The report said that the economy is showing signs of recovery, though sentiment is still being weighed down by Middle East tensions; for the outlook, uncertainty from the Middle East and concerns over the impact of the Kumamoto earthquake persist.
Japanese bank lending, including trusts, rose 5.4% y/y in July, easing from 5.7% in June. Total lending at banks and shinkin banks was ¥679.2tn. By lender, total bank lending increased by 5.9% y/y, with major banks up 8.0% and regional banks up 4.2%. Shinkin bank lending rose 1.9%, while foreign banks posted a 28.3% increase. The data suggest lending growth remained solid but moderated from the previous month, with the pace still strongest at major banks and foreign banks. The release provides a snapshot of Japan’s bank credit conditions in July, indicating continued loan expansion across most lender categories despite some deceleration.
Japanese investors sold a net ¥567.4bn of Australian sovereign bonds in June – the second-largest on record and the biggest since February 2021. The move reversed May’s net purchases of ¥127.3bn. They also sold U.S. sovereign bonds in June after buying them in the previous two months, with net sales of ¥883bn vs. net purchases of ¥616bn in May. By contrast, net purchases of French sovereign debt rose to ¥348.7bn, the highest since February 2025, while buying of U.K., Italian and German sovereign bonds remained positive.