Market Movers: Not easy
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Bob Savage
Time to Read: 6 minutes
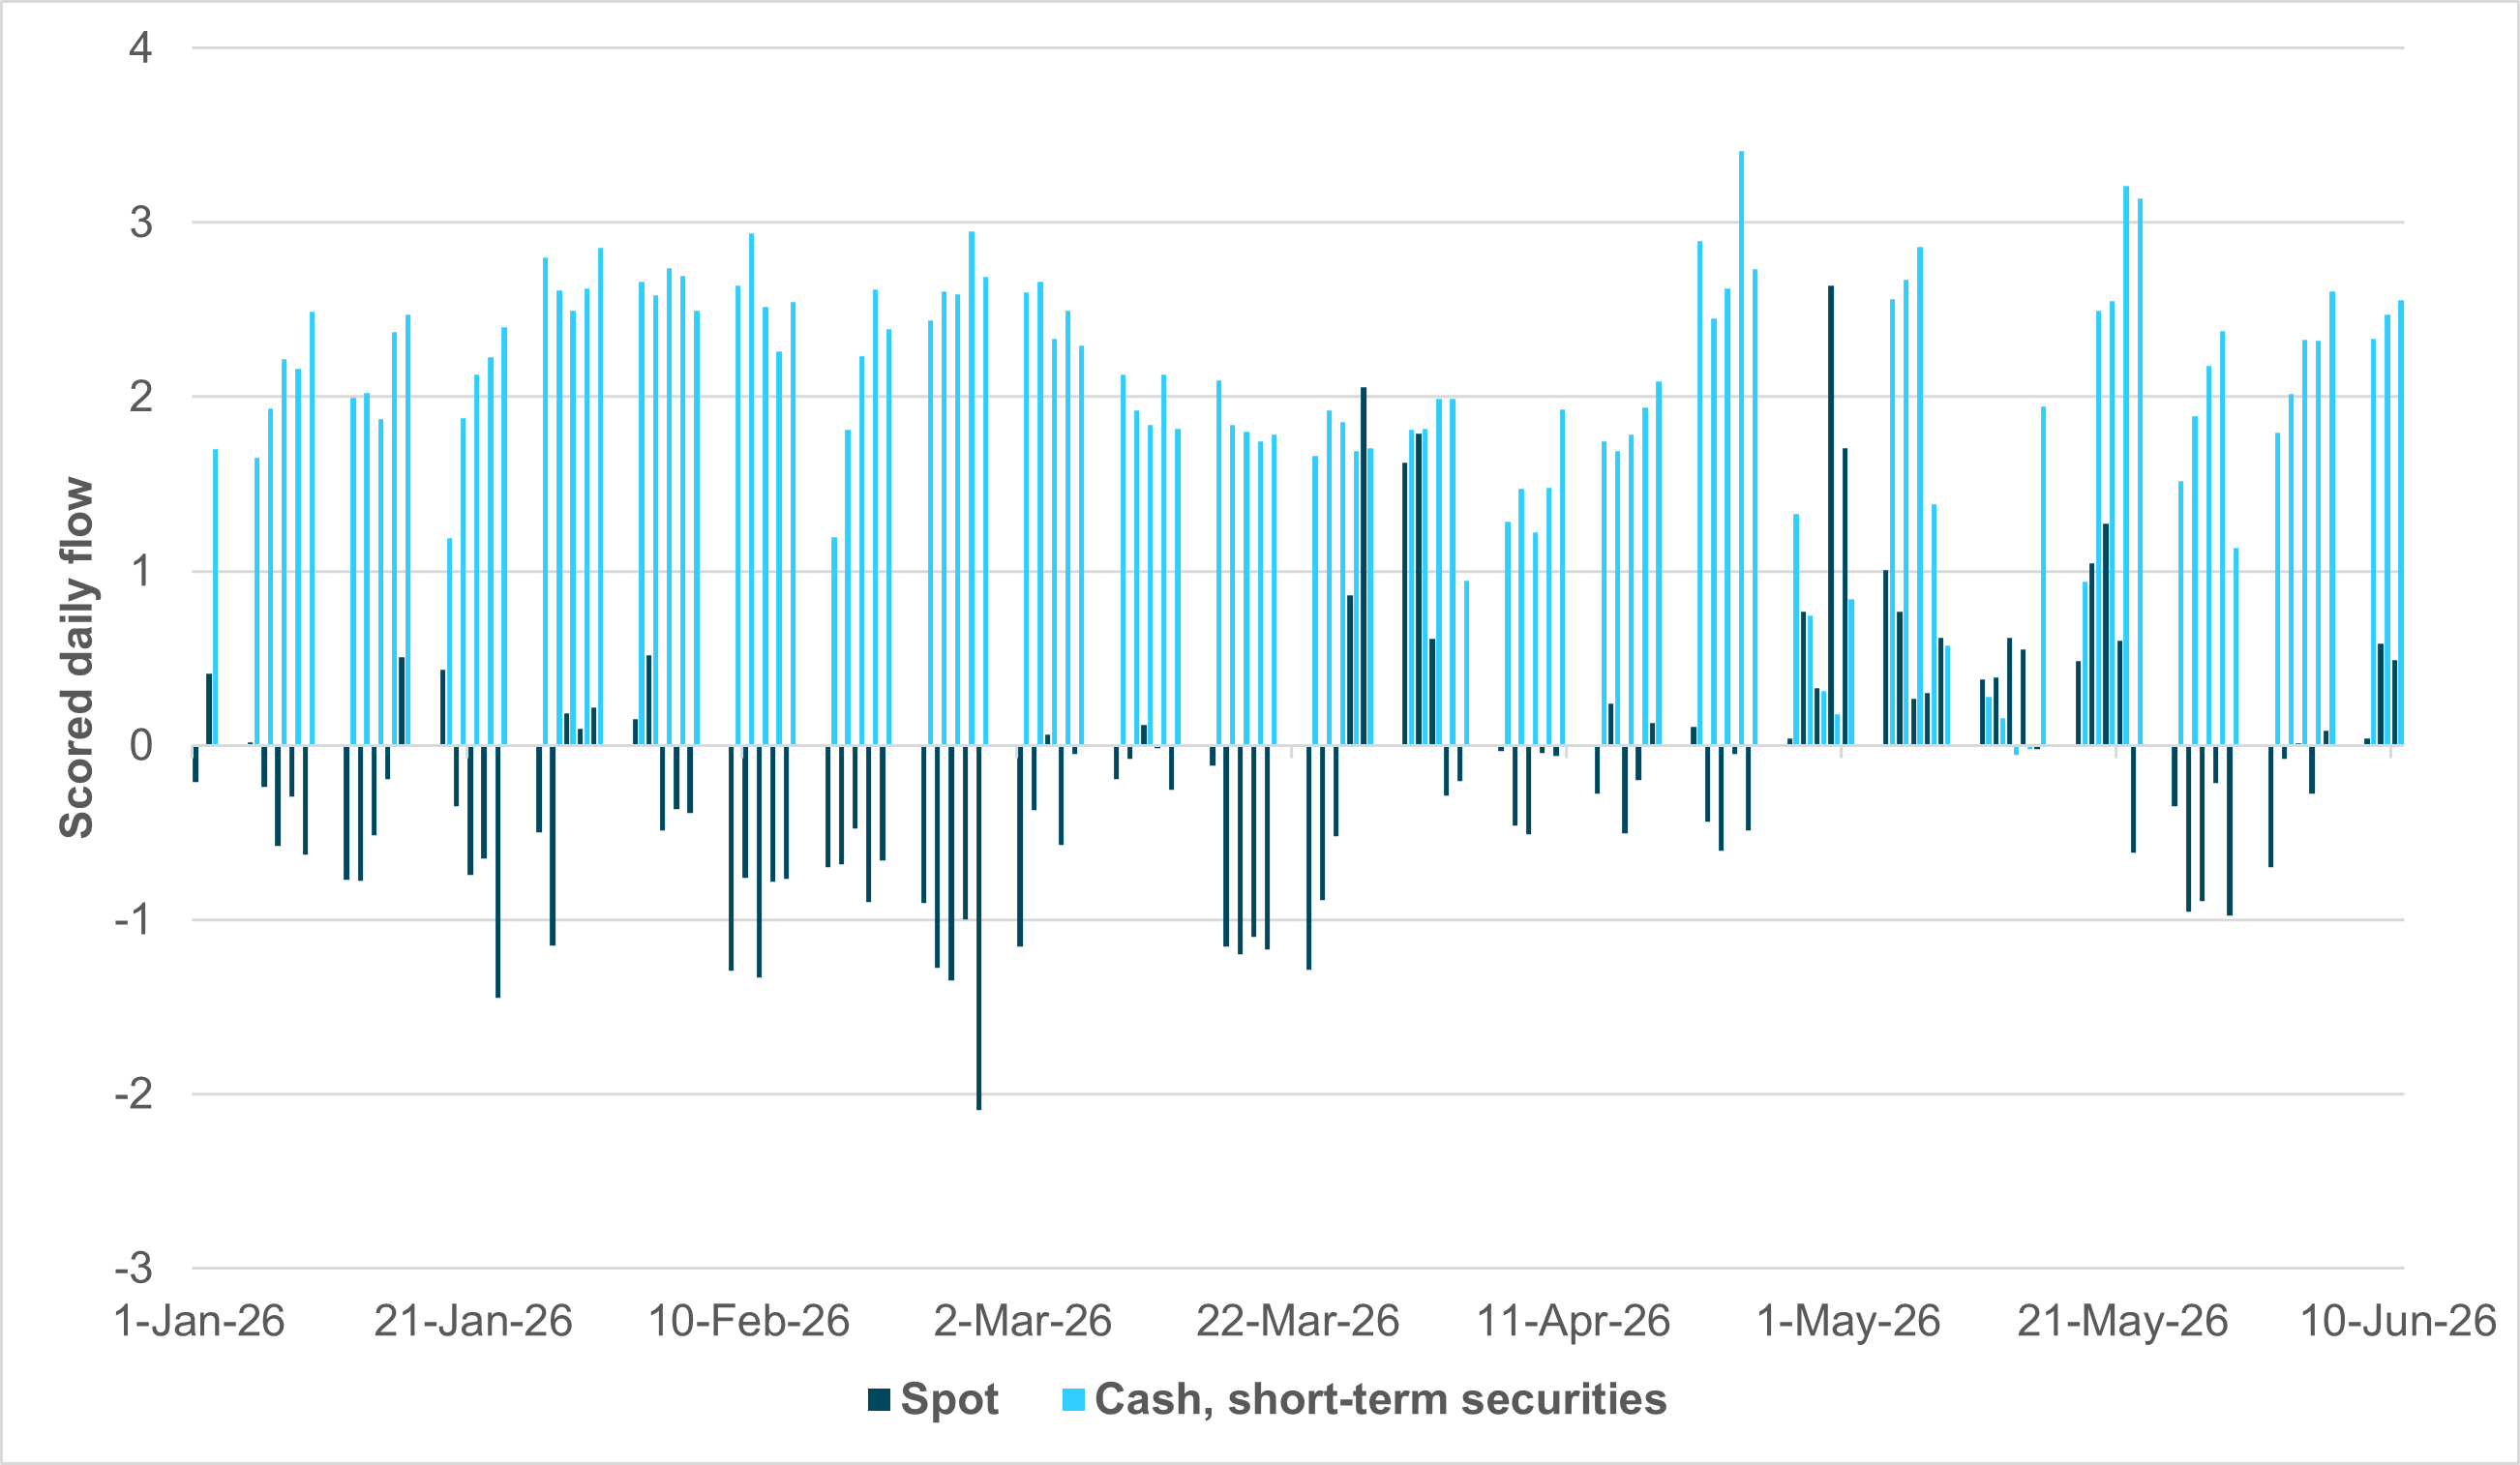
Cross-border USD cash and spot USD flows remain strong
Source: BNY
U.S. equity markets opened today with SpaceX making its trading debut after its IPO. Global inflation and policy expectations are in the background, but the Fed isn’t seen at the forefront of tightening yet. The dollar has held firm despite the ECB’s hike yesterday and signals more to come. Dollar demand, or liquidity preference, has been abnormally strong over the past few weeks, likely driven by the need to fund participation in the IPO offerings, even though allocations reportedly account for just 10% of the total. Cross-border spot flows have been moderate, with a surge earlier in May, while cash and short-term instruments (CAST) have seen consistent demand, averaging at elevated levels throughout the year. For CAST, rate expectations are the primary driver – but the steady pickup in April also tracks the shift in the global risk environment when the U.S. began leading equity performance on the back of the technology theme. Over the same period, cross-border hedges on U.S. assets fell sharply, suggesting aggregate exposures are near highs, driven either by confidence in current holdings or expectations of further gains.
Trading risk hasn’t been straightforward this week and won’t be today, even with clear momentum to put cash to work. Oil has fallen further overnight to March lows after a 14-point memorandum of understanding (MOU) for peace negotiations was released in Iran, with G7 officials confirming a deal could be signed by Sunday. Optimism over a U.S.–Iran conflict resolution has lifted global shares 2-3%, following yesterday’s U.S. rally after Trump called off further strikes. U.S. stock futures are extending gains, up 0.5-1%. Globally, 10y yields are 5–10bp lower, also following the U.S. move, despite lingering inflation concerns and the ECB hike. The relief moves leave the USD off 0.2%, with NOK and JPY weaker, while INR and KRW lead EM gains.
Bottom Line: Next week is about central bank rate decisions and more economic data on growth and inflation. The risk is that the rally proves short-lived, driven by peace-talk optimism rather than earnings and growth outlooks. The higher U.S. PPI and CPI this week, along with expectations of a Fed shift from easing to neutral bias, have been priced into bonds – though some of that unwinding with the current oil market relief. Whether this continues is best measured in the shape of the oil futures market and the cost of oil three to six months ahead. After the last 103 days, returning to normal won’t be easy, and neither central bank policy nor energy supplies will flip quickly.
The U.S. and Iran have reportedly agreed on the text of a memorandum of understanding that would extend the current ceasefire by 60 days and provide a framework for broader negotiations. The proposed deal calls for the immediate reopening of the Strait of Hormuz without transit fees and a return to normal shipping volumes within 30 days, while the U.S. would grant sanctions relief linked to Iranian compliance. Iran would commit to not pursuing nuclear weapons and begin discussions on resolving concerns over its enriched uranium stockpile, although detailed nuclear provisions would be covered in a separate agreement. Mediators say the text has received high-level backing and a signing ceremony could take place soon, though final approval is still pending and previous attempts to secure a deal have failed at late stages. Brent -4.172% to 86.61, WTI -4.31% to 83.93, Omani Crude -7.868% to 81.15, Dubai Crude -1.27% to 88.736.
ECB officials signaled that another interest rate increase could come as soon as July if the fallout from the war in the Middle East keeps intensifying. Governing Council member Joachim Nagel said the latest deposit rate hike was necessary because higher energy costs are feeding through to broader prices and core inflation, and he stressed that the ECB is keeping all options open and remains data dependent. He added that the inflation outlook has worsened and the shock is strong and persistent, making it impossible to simply look through it. Other policymakers also noted significant uncertainty, while markets and the IMF expect further tightening to contain inflation risks. Euro Stoxx 50 +1.97% to 6,176, EURUSD -0.009% to 1.1577, BBG AGG Euro Government High Grade EUR +2bp to 3.344%.
SEMI’s global semiconductor equipment market report showed that worldwide semiconductor manufacturing equipment sales in Q1 2026 rose to a record US$365.5bn, up 14% y/y and 1% q/q. The gain was driven by continued AI-related investment, including stronger demand for advanced logic, DRAM and advanced packaging, as chipmakers expanded capacity and upgraded technology. Regionally, China remained the largest market at US$109.9bn (+7% y/y, -16% q/q), though momentum eased vs. the previous quarter. South Korea posted US$89.3bn (+16% y/y, +26% q/q), while Taiwan recorded US$87.7bn (+24% y/y, +18% q/q), making it one of the fastest-growing areas. The report highlights that AI infrastructure demand is keeping capital spending elevated across both front-end manufacturing and back-end advanced packaging. KOSPI +4.63% to 8,124, USDKRW -0.853% to 1518.15, 10y KTB +5bp to 4.315%.
Bank Indonesia has tightened oversight of FX trading at global and local banks to defend the rupiah and curb speculative dollar demand. BI is sending officials into dealing rooms, checking documentation for large dollar purchases, and monitoring seven lenders with heavy FX activity to ensure transactions are for commercial purposes only. Banks are barred from holding long dollar positions or making speculative bets. The move comes after a surprise rate hike and stepped up intervention as the rupiah hit record lows and Indonesian assets underperformed. Officials have also urged foreign banks to bring more dollars onshore, though liquidity concerns and policy uncertainty are making some lenders cautious. JCI +2.07% to 6,008, USDIDR -0.684% to 17,870, 10y IDGB -2.8bp to 7.417%.
The preliminary University of Michigan Consumer Sentiment for June is forecast to rise to 46.0 vs. 44.8. Current Conditions are expected to rise to 46.0 vs. 45.8. Expectations are forecast to rise to 44.7 vs. 44.1. With 1-year Inflation Expectations projected to rise to 4.9% vs. 4.8%, 5-10 year Inflation Expectations are expected to hold steady at 3.9%.
Mood: iFlow Mood deteriorated to -0.325, as equity outflows intensified alongside renewed demand for core government bonds.
FX: Flows were mixed and moderate across the iFlow universe. BRL and CAD recorded the largest outflows, while USD and NZD attracted inflows. Elsewhere, EUR, GBP and AUD were sold, against modest buying of JPY.
FI: Broad demand emerged for G10 and LatAm government bonds, led by Europe, Colombia and Japan. The largest outflows were seen in government bonds from China, Indonesia, Hungary and South Africa.
Equities: Selling was widespread across LatAm and EMEA, particularly in Chile and South Africa. Flows were more mixed in G10 and APAC, with notable selling in Indonesia and the U.K., while China, Australia and Thailand attracted buying interest.
“Simple, not easy, there is a difference.” – Ron Jefferies
“Do not pray for an easy life, pray for the strength to endure a difficult one.” – Bruce Lee
Germany’s inflation for May 2026 came in at 2.6% y/y, down from 2.9% in April, while consumer prices fell 0.2% m/m, according to the Federal Statistical Office. The moderation reflected a weaker pace of price gains in energy, though costs remained elevated due to the Iran conflict and higher oil prices. Energy products were still 6.6% above a year earlier, with fuel up 18.0% and household energy down 0.8%. Food prices rose just 0.4%, while core inflation excluding food and energy was 2.5%. Services prices increased 3.1%, keeping underlying inflation firm. DAX +1.72% to 24,626, EURUSD -0.009% to 1.1577, 10y Bund -5.4bp to 2.978%.
French consumer price inflation for May 2026 came in at 0.1% m/m and 2.4% y/y, easing from 1.0% in April on a monthly basis but edging up from 2.2% previously on an annual basis. The monthly rise was driven mainly by higher energy prices, especially gas, and a further increase in food prices, while services and tobacco were broadly unchanged and manufactured goods rose only slightly. On an annual basis, the pickup reflected faster gains in energy and services, partly offset by softer food inflation. Core inflation also firmed to 1.5% y/y, while the HICP increased 0.1% m/m and 2.8% y/y. CAC40 +2.07% to 8,370, EURUSD -0.009% to 1.1577, 10y OAT -7bp to 3.732%.
Spain’s inflation for May 2026 came in at 3.2% y/y, unchanged from April, while the monthly CPI rose 0.1%. Core inflation edged up to 3.0% from 2.8%, reflecting firmer underlying price pressures. The largest annual upward contributions came from recreation, sport and culture, and transport, especially air passenger fares, while clothing and footwear and food and nonalcoholic beverages provided downward pressure. The harmonized index rose 3.6% y/y, up one-tenth from the prior month, with a monthly increase of 0.1%. Inflation was positive in all autonomous communities, led by Madrid at 3.8%, with the lowest in Extremadura at 2.5%. IBEX 35 +2.42% to 18,751, EURUSD -0.009% to 1.1577, 10y Bono -6.7bp to 3.405%.
The Bank of England Agents summary of business conditions for the June MPC meeting, covering the seven weeks to mid-May, reported only limited signs that the Middle East conflict has weakened U.K. output growth so far, although business confidence has deteriorated further and firms have scaled back hopes for stronger growth later this year. Manufacturers face some supply shortage risks and have been building stocks, while hiring may weaken later as higher costs and softer demand weigh on plans. Contacts also expect slower wage disinflation, more price pressure from energy intensive materials, and some passthrough of higher costs, but they remain cautious given weak demand and competition. FTSE 100 +1.34% to 10,442, GBPUSD -0.038% to 1.3412, 10y gilt -10.3bp to 4.802%.
The Bank of England survey of public attitudes to inflation, May 2026 showed households again expecting firmer inflation and higher borrowing costs. Median perceptions of current inflation rose to 5% from 4.6% in February, while one-year-ahead expectations increased to 4% and five-year expectations edged up to 3.9%. Views on interest rates also shifted sharply, with 53% expecting rates to rise over the next year vs. 30% previously. Satisfaction with the Bank of England’s handling of interest rates weakened, with the net balance slipping to minus 2% from plus 2%. Respondents still saw the inflation target as about right at 39%.
The U.K.’s real GDP for the three months to April 2026 grew by 0.7% compared with the three months to January 2026, after gains of 0.6% in the three months to March and 0.5% in the three months to February. Services output rose by 0.8%, matching the pace seen previously, while production output fell by 0.1% after a 0.2% increase. Construction expanded by 1.6%, extending a partial recovery after five straight three-month declines from October 2025 to February 2026. On a monthly basis, GDP slipped 0.1% in April after stronger rises in March and February, as weaker services offset modest growth in construction.
U.K. services output for the three months to April 2026 increased by 0.8% compared with the three months to January 2026, matching the pace seen in the three months to March 2026. The broad-based gain was supported by 12 of 14 sectors, led by information and communication, wholesale and retail trade, and professional, scientific and technical activities. By contrast, arts, entertainment and recreation declined, while administrative and support service activities were flat. On a monthly basis, services output fell 0.2% in April 2026, the first monthly decline since October 2025. Weakness was led by administrative and support service activities, arts, entertainment and recreation, and wholesale and retail trade, partly reflecting disruption linked to conflict in the Middle East.
U.K. production output for the three months to April 2026 fell by 0.1% compared with the three months to January 2026, marking the first decline in three-month growth since November 2025. Weakness in electricity and gas, water supply and sewerage, and mining and quarrying outweighed a 0.6% rise in manufacturing. Within manufacturing, gains in basic pharmaceutical products and computer, electronic and optical products were partly offset by declines in machinery and equipment and electrical equipment. On a monthly basis, production was flat in April 2026 after a small fall in March and a rise in February. Manufacturing and mining supported the month, while electricity and gas and water supply and sewerage dragged on activity.
U.K. goods trade in April 2026 showed imports rising by £0.8bn, or 1.5%, while exports also increased by £0.8bn, or 2.6%. The import gain was driven by a £1.1bn rise in purchases from the EU, partly offset by a £0.3bn fall in imports from non-EU countries. Exports increased evenly, with gains of £0.4bn to both EU and non-EU markets. In the three months to April 2026, the total goods and services trade deficit widened sharply by £7.7bn to £9.9bn, as the goods deficit expanded and the services surplus narrowed slightly.
Turkey’s balance of payments in April 2026 posted a current account deficit of US$5.695bn, narrower than a year earlier, while the trade deficit was US$6.819bn. Excluding gold and energy, the current account showed a US$319mn surplus. On a 12-month basis, the current account deficit eased for the first time since September 2025 to about US$37.0bn, helped by a US$62.8bn services surplus, partly offset by primary income and secondary income deficits. Services net inflows were US$3.670bn, led by transport and travel. On the financing side, portfolio inflows and reserve increases supported funding, while net foreign exchange and deposits weighed on the account. BI 100 +2.52% to 14,090, USDTRY +0.128% to 46.2599, 10y TGB -77bp to 33.73%.
Turkey’s June 2026 Market Participants Survey showed a slight rise in year-end inflation expectations and mixed moves across other macro forecasts. The average year end CPI expectation edged up to 29.14% from 28.94%, while 12-month and 24-month expectations were broadly stable at 23.81% and 18.29%, respectively. Participants now see USD TRY at 51.47 by end 2026 and 55.72 in 12 months, both higher than the previous round for the latter horizon. GDP growth expectations were trimmed to 3.2% for 2026, while 2027 remained at 4.1%. The expected policy rate for the June MPC meeting was 37.0%.
Romania’s CPI inflation accelerated to 10.9% y/y in May 2026, up from 10.7% in April, while consumer prices rose 0.6% m/m. Inflation since the start of the year reached 3.7%, and average inflation over the past 12 months stood at 9.4%. Services remained the main source of price pressure, rising 13.5% from a year earlier, followed by nonfood goods at 12.5% and food prices at 6.8%. Fuel prices continued to rise sharply, increasing 19.2% y/y, with petrol up 30.6% and diesel up 36.9%. Electricity prices remained 55.5% higher than a year earlier despite a monthly decline, while rents increased 43.6% annually. The harmonized inflation rate eased slightly to 9.7% y/y. Overall, the data indicate persistent and broad-based inflation pressures despite some moderation in regulated energy prices. BET +0.46% to 30,300, EURRON -0.052% to 5.2368, 10y RGB +5.9bp to 6.966%.
New Zealand’s manufacturing sector slipped back into contraction in May, with the BNZ-BusinessNZ Performance of Manufacturing Index falling to 49.9 from 50.4 in April, after 52.8 in March. BusinessNZ said the decline reflected weak customer demand, high fuel prices and Middle East tensions. Sub-indices showed stocks of finished goods (53.8) and deliveries (51.9) remained in expansion, but production (50), employment (49.6), and new orders (50.1) were broadly flat around 50.0. Smaller firms were hit hardest, while large firms continued to perform strongly. BNZ said the sector may remain subdued through winter, though broader economic momentum could improve later in the year if conditions stabilize. NZX 50 +1.45% to 13,394, NZDUSD -0.138% to 0.5828, 10y NZGB -8bp to 4.469%.
Indonesia’s government and lawmakers agreed on the 2027 fiscal framework, targeting economic growth of 5.8%–6.5% and a budget deficit of 1.8%–2.4% of GDP. Finance Minister Purbaya Yudhi Sadewa said fiscal discipline will be maintained, with deficits and debt kept within prudent limits to support sustainable growth. The growth goal is part of a roadmap to reach 8% annual growth by 2029, supported by stronger coordination among fiscal, monetary, and financial policies, as well as deregulation and improved investment conditions. The government also plans to boost revenue through better tax compliance, a broader tax base, and stronger administration, while keeping inflation and borrowing conditions under stated macro assumptions. JCI +2.07% to 6,008, USDIDR -0.684% to 17870, 10y IDGB -2.8bp to 7.417%.
Taiwan’s financial regulator reported that local banks’ deposits rose by TWD 1.055tn in April 2026, the first monthly increase to top TWD 1tn and the largest on record. The surge was driven by AI-related capital inflows, a strong Taiwan equity market, foreign institutional buying, and repatriated funds from ETF redemptions and profit-taking. Cumulative deposits for January–April increased by TWD 2.154tn, with April contributing nearly half of the year-to-date gain. Total deposits reached TWD 65.246tn at end-April, up TWD 5.33tn y/y, the biggest annual rise since May 2022. The authority said the inflows mainly reflected large payments from domestic and overseas firms and investment funds. Foreign capital also hit a record net inflow of US$26.4bn in April, helping lift bank deposit balances. TAIEX +2.36% to 44,169, USDTWD +0.026% to 31.632, 10y TGB -6.1bp to 1.7%.
Hong Kong’s industrial production for manufacturing industries in Q1 2026 rose 3.1% y/y, slowing from 5.8% in Q4 2025, according to provisional figures from the Census and Statistics Department. The corresponding producer price index jumped 17.7%, accelerating sharply from 9.5% previously. Output gains were led by metal, computer, electronic and optical products, machinery and equipment, while food, beverages and tobacco also rose. By contrast, textiles and wearing apparel, and paper products, printing and recorded media declined. On a seasonally adjusted basis, manufacturing output fell 2.6% q/q. Producer prices increased across all major manufacturing industries. Hang Seng +0.81% to 25,591, USDHKD -0.022% to 7.8363, 10y HKGB -1.2bp to 1.417%.
Peru’s BCRP kept the reference rate unchanged at 4.25% in June 2026. The decision reflected softer inflation and still-solid activity indicators, alongside elevated global risks. In May, headline inflation was -0.16% m/m, down from the prior month, mainly due to lower prices for some food items; core inflation was 0.09% m/m. On a y/y basis, headline inflation eased to 3.9% in May from 4.0% in April, while core inflation stayed at 4.4% y/y, remaining above the target range. Twelve-month inflation expectations rose to 2.9% in May from 2.8% in April but stayed within the target band. The BCRP said supply-related inflation pressures are expected to fade over the forecast horizon. BCRP maintain forward looking statement, “commitment to adopt the necessary actions to ensure the return of inflation to the target range over the forecast horizon.” MSCI NUAM Peru General +3.92% to 54,960, USDPEN -0.572% to 3.39, 10y PGB +3bp to 6.05%.