Market Movers: New Regimes
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Bob Savage
Time to Read: 8 minutes
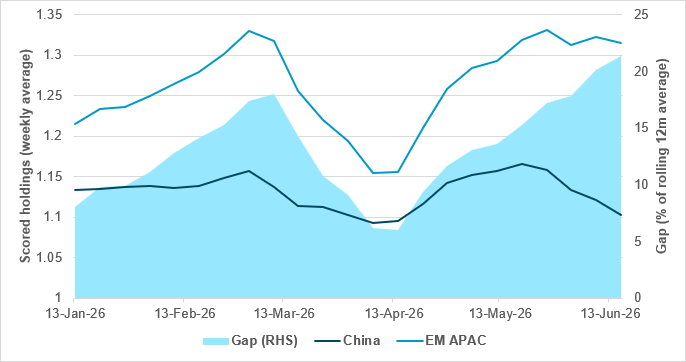
Holdings gap for Chinese equities vs. EM APAC peers at widest YTD
Source: BNY
The weakness in Chinese equities is now clearly reflected in our holdings figures for the market. Despite a good round of institutional purchases in recent weeks as value plays and rebalancing have generated some interest, these have not been enough to generate a more sustained gain in holdings. After today’s moves, we expect aggregate holdings of Chinese equities by institutional clients to fall back to April’s lows.
More importantly, the holdings figures for EM APAC – led by South Korea and Taiwan – continue to challenge new highs, and the gap against Chinese equities is now at its widest YTD. Even though there is significant concentration risk in these exchanges, the capitalization gains are now starting to offset China’s broader market size. If we strip out China’s share of holdings in EM APAC, the gap is likely to be even bigger. Our data also indicate that South Korean equities – currently the best-held in the region – have been driven by retail flows and in scored terms, while institutional flows in China have been stronger. Nevertheless, the difference in holdings levels remains wide, underscoring not only the power of retail flows, but also their absence in Chinese equities at present. Without a sufficient data and/or earnings lift, the gap between China and its peers looks set to widen.
Markets are embarking on Thursday’s session with the prospect of two new regimes in mind, both of which are essential for managing rate expectations.
Firstly, Fed Chair Warsh has set out his vision for his Federal Reserve. The short-term changes in policy pricing are just that – temporary in nature and easily adjustable in either direction. However, the long-term changes he envisions in balance sheet management and communications strategy would represent a regime shift in how the market reacts to the Fed and the subsequent transmission into the real economy.
Secondly, the memorandum of understanding signed by the U.S. and Iran, even if it proves durable, will be considered a regime shift in global supply chains. We fully expect more relief rallies as shipping through the Strait of Hormuz resumes, but the explicit and implicit costs will rise. Tolls, insurance and even the costs of reconstruction and diversification for suppliers will need to pass through the global economy and keep central banks vigilant. The market may be digesting the shift in the pricing of the Fed in favor of a full hike before year-end, but structural regime shifts in policy approach and global energy supply have the potential to change equilibrium rates. No economy or sector, no matter how resilient at present – especially technology and AI – will be immune to such changes.
ECB hikes find few imitators in Europe: The BoE, SNB and Norges Bank have all kept rates on hold overnight, following in the footsteps of the Riksbank yesterday. There is, however, a strong chance of a hike by the Czech National Bank. Scandinavian central banks remain open to rate hikes should domestic inflation continue to surprise to the upside, but attribution of changes is firmly domestic in nature. There is no clamor to follow the ECB; if anything, these economies are currently performing better and less prone to stagflation risk, especially given their strong fiscal resources. A July ECB hike remains on the table, but EUR’s continuing softness affirms the view of downside growth risks being exacerbated by monetary policy.
No let-up in hikes in APAC: The signing of the Iran war MoU has not prevented the Philippine and Indonesian central banks from continuing their current policy approach. We fully expect balances of payments to improve across ASEAN and ease pressure on currencies, but the shift in Fed pricing means the margins are very fine for exchange rate performance. Our data indicate that carry trades are no longer as excessively held as pre-conflict levels, making the marginal impact of higher implied dollar yields more manageable. Nonetheless, asset allocation preferences for the U.S., even independent of economic developments, will require high EM real rates to avoid currency stress.
China in a bear market: The weak round of Chinese data for May and further rotation out of Asia (ex-South Korea and Taiwan) into the U.S. has further eroded holdings appetite for Chinese equities. MSCI China is now in a bear market, and the government’s renewed efforts to tackle involution and youth unemployment are tacit recognition of the economic challenges. Beijing is cognizant of further downside risks to growth arising from a negative wealth effect from poor equity performance, and markets should be vigilant on the potential for renewed fiscal stimulus.
Gilt markets eye Makerfield results: The gilt markets will be eyeing developments in Greater Manchester more than London’s Threadneedle Street today, as the Makerfield by-election looks set to herald the return of Andy Burnham to parliament. It is expected that either Burnham or former health secretary Wes Streeting will trigger a Labour Party leadership election as early as next week. This will set the stage for increased uncertainty regarding the U.K.’s fiscal outlook due to competing economic visions, compounded by an environment where monetary policy space to cut rates remains very constrained.
Bottom line: Judging by the market’s performance over the past 24 hours, Fed Chair Kevin Warsh has come through his first test with flying colors. The prospect of further normalization in supply pressures through the signing of the U.S.-Iran MoU has made achieving near-term price stability easier, but shaping the Fed according to his vision is a marathon, not a sprint. Beyond current Fed settings, markets should expect challenging parts of the route along the way, especially given the ample supply of factors beyond any central bank’s control. Today’s policy decisions around the world point to sustained vigilance on inflation, whereas risk sentiment appears to indicate financial conditions are heading toward a different equilibrium.
U.S. has released the text of the MoU with Iran, which includes 60 days of no-charge transit through the Strait of Hormuz. The deal calls for an immediate and permanent halt to military operations, a 60-day window to negotiate a final agreement and a pledge by Iran not to develop nuclear weapons. It also includes U.S. commitments to end the naval blockade of Iran, facilitate safe and fee-free Hormuz transit for 60 days and support a reconstruction and economic development plan worth at least $300bn. The U.S. would also move to ease sanctions, including waivers for Iranian crude exports, related services and access to frozen funds, while the final implementation details would be worked out within the 60-day period. The announcement is significant for oil markets, sanctions policy and regional security. S&P Mini +0.83% to 7555, DXY +0.19% to 100.279, 10y UST -4.4bp to 4.443%.
The BoK has said rising overseas investment is putting upward pressure on the won-dollar exchange rate, with stronger demand for foreign currency to fund outbound investment outweighing some support from investment income earned abroad. In a BoK Issue Note, the bank said South Korea’s overseas securities investment more than doubled last year, while direct investment declined, signaling a shift toward financial assets. It also warned that the stabilizing effect of overseas investment income is reduced when earnings are reinvested abroad rather than repatriated. The BoK cited Japan as a similar case, where large investment income surpluses have not translated into a stronger currency because of high reinvestment abroad. KOSPI +2.25% to 9064, USDKRW -0.889% to 1530.2, 10y KTB -4.8bp to 4.062%.
The SNB has kept its policy rate unchanged at 0% and left the remuneration terms on sight deposits broadly steady, while signaling a greater willingness to intervene in foreign exchange markets if the franc appreciates too quickly. It said inflation has risen in recent months, mainly because of higher energy prices, but medium-term price pressures are little-changed and its policy remains consistent with price stability. It forecasts that inflation will stay within its target range, averaging 0.6% in 2026 and 2027 and 0.7% in 2028, assuming rates stay at zero. The bank also noted resilient Swiss growth but expects slower near-term momentum and around 1% GDP growth in 2026. SMI +0.1% to 13829, EURCHF -0.225% to 0.92088, 10y Swiss GB -0.1bp to 0.335%.
Norges Bank left Norway’s policy rate unchanged at 4.25% in June, after lifting it to that level in May. The committee said inflation remains too high and that price pressures are slightly stronger than previously expected, implying a further rate increase may be needed at one of the upcoming meetings. It also noted that business costs have risen sharply, helping to keep inflation elevated. Mainland growth has been somewhat weaker than projected, while unemployment has been stable in recent months but is drifting higher in LFS data. Capacity utilization is still around normal but easing. The policy rate path was revised slightly up compared with March, with the rate forecast just above 4.5% by end-2026. Norges Bank expects inflation to fall from 2027 onward, reaching 2.0% in 2029. OSE -0.14% to 1949, EURNOK -0.466% to 11.0518, 10y NGB +1.2bp to 4.299%.
The MSCI China Index fell toward a bear market as Chinese equities continued to weaken, with the gauge dropping as much as 2.1% on Thursday, down 20% from its October 2 peak. The move was led by losses for Alibaba Group Holding and Tencent Holdings, as investors grew more concerned about soft earnings prospects and sluggish domestic demand. The selloff has been concentrated in internet and e-commerce shares, while mainland support measures and industrial tech exposure have not offset the broader pressure. The decline also underscores how Chinese stocks have lagged the global AI-driven rally, leaving the index vulnerable to further downside and the second major Chinese benchmark this year to approach bear market territory. CSI 300 +0.21% to 4942, USDCNY -0.015% to 6.7617, 10y CGB -1.1bp to 1.723%.
The BoE is expected to keep rates unchanged at 3.75%.
The Czech National Bank is expected to hike rates to 3.75% from 3.50%.
U.S. initial jobless claims are forecast at 225k vs. 229k.
U.S. June Philadelphia Fed Business Outlook is forecast to rise to 10.0 vs. -0.4.
U.S. May Leading Index is forecast at 0.1% vs. 0.1%.
Canada June CFIB Business Barometer is due; the May reading was 46.3.
Canada May industrial product prices are forecast at 1.0% vs. 2.0% m/m.
Canada May raw materials price index is forecast at 1.1% vs. 2.6% m/m.
Central bank speakers: ECB Chief Economist Philip Lane participates in the “Session on monetary policymaking under uncertainty” at the Deutsche Bank Forum in London.
U.S. Treasury sells $70bn in 4-week bills, $75bn in 8-week bills and $24bn in a 5y TIPS reopening.
Mood: iFlow Mood has retraced modestly from its extreme negative levels but remains in risk-off territory at -0.283. Global equities continue to face outflow pressure, while demand for core government bonds has moderated.
FX: USD inflows dominated, primarily against CAD and EUR outflows. Elsewhere, flows across the iFlow universe were generally light and mixed.
FI: Demand remained firm across G10, EMEA and LatAm government bonds, led by the Eurozone, Japan and Colombia. Australia was a notable exception with continued selling, while APAC fixed income flows were biased toward outflows, led by South Korea. Demand for Indian government bonds continued, supported by recent government measures to attract foreign inflows.
Equities: Broad-based outflows persisted, particularly in Taiwan, Türkiye, South Africa, the U.K. and Europe. Selective buying was observed in Australian, Hong Kong and, to a lesser extent, U.S. equities.
“Stop talking so much.” – Kevin Warsh
“You can’t beat something with nothing.” – Jerome Powell
Euro area current account data for April showed a surplus of €16bn, up from €15bn in March. This was supported by goods and services surpluses of €17bn and €15bn, respectively, partly offset by deficits in secondary income and primary income. Over the 12 months to April, the current account surplus narrowed to €269bn, or 1.7% of GDP, from €351bn, or 2.3%, a year earlier. The decline reflected weaker goods and services balances, a switch in primary income to a small deficit, and a larger secondary income deficit. In the financial account, portfolio and direct investment flows were mixed, while reserve assets fell to €1.888tn. Euro Stoxx 50 +0.31% to 6320, EURUSD +0.027% to 1.1504, BBG AGG Euro Government High Grade €-0.9bp to 3.215%.
Italy’s current account for April and its latest external accounts data showed a stronger external surplus: the 12-month current account rose €32.9bn, or 1.4% of GDP, from €18.0bn a year earlier. The improvement was driven by a return to surplus in primary income and a larger goods surplus, while services deteriorated slightly and secondary income was little-changed. In April, the current account posted a deficit of €2.3bn, but financial flows remained supportive, with net external asset acquisitions of €11.2bn over 12 months. Residents increased foreign portfolio assets, while foreign liabilities also rose, mainly through purchases of Italian securities. FTSE MIB -0.05% to 52567, EURUSD +0.027% to 1.1504, 10y BTP +1.2bp to 3.634%.
Dutch unemployment came in at 3.9% in May, unchanged vs. April. The unemployment count was 399,000, while employment edged lower as the number of people in work fell by an average of 7,000/month over the past three months. Over the same period, the number of unemployed people fell by an average of 6,000 per month, as more people found work than became unemployed. At the end of May, the UWV recorded 199,400 unemployment benefit recipients, down 1.8% from April, with the largest declines in agriculture, construction and temporary agencies, linked to seasonal hiring. The CBS also noted that 3.2 million people were outside the labor force, and that this group had increased by 11,000/month over the past three months. AEX -0.19% to 1081, EURUSD -0.725% to 1.1513, 10y NGB 0bp to 3.048%.
U.K. labor market data for February-April painted a broadly stable picture, with the employment rate unchanged y/y at 75.0%. The unemployment rate rose by 0.3 percentage points y/y to 4.9%, but fell by 0.3 percentage points compared with November 2025-January 2026. Economic inactivity moved in the opposite direction, dropping by 0.3 percentage points y/y but edging up by 0.3 percentage points q/q to 21.0%. The release also noted that January-March 2025 estimates fully reflect improvements to Labour Force Survey data collection and sampling methods introduced from January 2024, though some volatility remains in recent and granular estimates. FTSE 100 -0.6% to 10445, GBPUSD -0.858% to 1.3297, 10y gilt +0.7bp to 4.758%.
U.K. average earnings for February-April showed continued nominal gains, with regular pay rising 3.4% y/y and total pay up 4.4% y/y. After adjusting for inflation, real regular earnings edged up 0.1% on a CPIH basis and 0.3% using CPI, while real total pay increased by 1.2% and 1.3%, respectively. Public sector regular earnings growth was 5.1%, well above the 2.9% recorded in the private sector, although the official note said public pay was still affected by the timing of pay awards. Among private industries, wholesaling, retailing, hotels and restaurants posted the strongest regular earnings growth at 3.5%, indicating broadly steady wage momentum.
U.K. payrolled employment for May came in at 30.3 million, down 0.4% y/y and equivalent to 119,000 fewer employees. Employment rose by 2,000 from April, although the May figure is provisional and may be revised next month. The April decline was also revised to a fall of 53,000 from an earlier estimate of 100,000, reflecting additional real-time information submissions. By sector, accommodation and food services recorded the largest y/y drop, down 80,000, while administrative and support services posted the biggest rise, up 34,000. Median monthly pay increased by 4.6% y/y, led by health and social work at 7.0%, with finance and insurance weakest at 1.8%.
Swiss foreign trade rallied strongly in May after April’s stagnation. Seasonally adjusted exports rose 13.4% m/m to CHF 25.4bn, the highest figure since March 2025 (April: -0.5%), while imports increased by 3.4% m/m to CHF 19.8bn (April: -2.9%). This produced a CHF 5.6bn surplus – the largest in 12 months. Export growth was driven mainly by chemicals and pharmaceuticals, which jumped 25.7% m/m, especially antivirals/vaccines and pharmaceutical intermediates. By region, Europe led the way, with exports up 18.5% m/m and imports up 5.9% m/m, supported in particular by Slovenia, Germany, France and Belgium. Exports to North America also increased, while Asia was broadly flat. Watches declined by 4.0% m/m, and jewelry and watch imports fell substantially. SMI +0.1% to 13829, EURCHF -0.225% to 0.92088, 10y Swiss GB -0.1bp to 0.335%.
Poland’s consumer tendency improved in June, as the current consumer confidence indicator rose to -9.9 points from -11.3 in May, while the leading indicator increased to -7.7 from -8.5. Statistics Poland said sentiment strengthened both on the current and expected situation, with better views on the country’s economic outlook, household finances and major purchases. The June reading still remained negative, indicating that pessimism outweighed optimism, and was slightly below the level a year earlier for both indicators. The survey also showed easing concern about the Ukraine situation: fewer respondents viewed it as a major threat to the Polish economy and to sovereignty, while most said it had only a moderate impact or no impact on their answers.
Turkish house sales fell sharply y/y in May. Total house sales declined by 31.2% to 93,333, with new sales down 27.9% to 30,196 and existing home sales down 32.7% to 63,137. Mortgaged sales slipped 2.8%, while other sales dropped 36.2%. In the January-May period, total house sales were down 6.6%. Sales to foreign buyers also weakened, falling 27.0% to 1,387, while commercial property sales decreased by 30.9% to 11,434, as transactions in both new and existing properties fell. BI 100 +0.89% to 14550, USDTRY -0.275% to 46.4452, 10y TGB +1bp to 33.26%.
In Japan, May condominium market data for the Greater Tokyo area showed launches up 12.3% y/y to 1,447 units (+24.4% m/m). This second straight monthly increase was led by Tokyo’s 23 wards and Chiba. The initial contract rate improved to 64.9% (+7.0 percentage points y/y, +2.6 percentage points m/m), indicating solid demand. The average apartment price climbed 13.5% y/y to ¥10.660bn, while the price per square meter rose 11.4% y/y to ¥1.563mn, reflecting persistent upward pressure. Unsold inventory recorded a fifth successive decrease to 6,270 units as of end-May, down from 6,313 at end-April. High-rise projects also performed well, with a contract rate of 80.7%. June launches are projected at around 1,500 units. Nikkei +1.65% to 71053, USDJPY -0.243% to 160.63, 10y JGB +1.8bp to 2.621%.
New Zealand GDP rose 0.8% q/q, 1.5% y/y in Q1, from 0.5% q/q, 1.5% y/y in Q4 2025. Growth was driven mainly by manufacturing, which rose 1.9%, led by transportation equipment, machinery and equipment manufacturing, and food, beverage and tobacco manufacturing. Business services increased by 1.1% and wholesale trade by 2.4%. Offsetting these gains, mining fell 11.6%, mainly due to lower oil and gas extraction, while construction declined by 1.0% as both residential and non-residential building activity weakened. On the expenditure side, GDP rose 1.0% q/q on stronger gross fixed capital formation (1.6% q/q) and household consumption (0.5% q/q), while imports increased by 4.2% and exports rose 3.1%, led by dairy products, other food, beverages and tobacco, and travel services. NZX 50 -0.22% to 13363, NZDUSD -0.499% to 0.5784, 10y NZGB +5.6bp to 4.436%.
Malaysia’s debt capital market (DCM) is expected to reach an outstanding volume of about $640bn by end-2026, supported by modest growth in non-sovereign borrowing, a deep domestic investor base, a stronger ringgit and continued innovation and digital integration. As of end-May, the outstanding DCM volume exceeded $610bn, up 6.5% y/y, with sukuk accounting for about 60% and government debt for about 58% of the market. Sovereign issuance fell about 25% in the first five months of the year, while non-sovereign issuance rose 17% y/y and made up 68% of total issuance (year-earlier period: 58%). Fitch said foreign investor demand has remained resilient despite global volatility, helped by stable yields and market depth. The first tokenized sukuk was issued in H1, and ESG DCM also expanded strongly, reflecting supportive tax incentives. KLCI +0.15% to 1713, USDMYR -0.914% to 4.107, 10y MGB +73.1bp to 3.607%.
The Philippines’ Monetary Board has raised the BSP’s target reverse repurchase (RRP) rate by 25bp to 4.75% and lifted the overnight deposit and lending facility rates to 4.25% and 5.25%, respectively. The central bank said inflationary pressures remain strong, with elevated global oil and fertilizer prices continuing to push up domestic fuel and food costs. It also noted that rising core inflation points to broader price pressures and second-round effects, including firmer inflation expectations. BSP projections now show a higher inflation path, with average headline inflation expected to breach the 4.0% tolerance ceiling in both 2026 and 2027, before easing to slightly above the 3.0% target in 2028. The board said the tightening move is aimed at anchoring expectations and containing spillovers. PSEi +0.64% to 6154, USDPHP -0.314% to 60.58, 10y PHGB +5.5bp to 6.879%.
Bank Indonesia has raised its policy rate by 25bp to 5.75%, extending its tightening cycle and taking cumulative hikes to 100bp since May. The central bank said the move was aimed at reinforcing rupiah stability amid persistent external pressure, with exchange rate defense remaining the main policy priority alongside inflation control. BI signaled continued FX intervention and indicated that higher SRBI rates may be used to attract capital inflows. It also introduced measures to support FX stability, including a higher foreign funding ratio for banks and tighter limits on FX cash purchases. BI left its 2026 macroeconomic forecasts unchanged, implying confidence that growth and inflation remain broadly in line with its baseline outlook. The statement suggests further tightening could still be needed if currency pressures re-emerge. JCI -0.99% to 6159, USDIDR +0.159% to 17710, 10y IDGB +12bp to 7.019%.
Taiwan’s central bank left policy rates unchanged at its June monetary policy meeting, keeping the discount rate at 2.00%, the secured loan rate at 2.375% and the short-term rate at 4.25%. The bank cited resilient domestic growth, still-mild inflation and heightened external uncertainty, including Middle East tensions, shifting major central bank stances and AI-related market volatility. It lifted its 2026 GDP growth forecast to 9.45% from 7.28% in March, while raising projected CPI and core CPI inflation to 1.91% and 1.90% from 1.8% and 1.64% in March, respectively. For January-May 2026, average CPI rose by 1.52% y/y and core CPI by 1.96% y/y. The bank also noted that liquidity is ample, with excess reserves averaging over NT$500bn in March-May, and said it will continue monitoring housing credit risks and exchange rate stability. TAIEX +1.28% to 46465, USDTWD -0.023% to 31.582, 10y TGB +1.5bp to 1.685%.
Brazil’s Copom has lowered the Selic rate to 14.25% in its third consecutive rate cut since March. The committee cited heightened global uncertainty, stronger volatility in asset and commodity prices, and domestic inflation that has moved further away from target, with headline and underlying inflation accelerating and exceeding the upper limit in the latest print. It also noted resilient economic activity in Q1, a still-strong labor market and de-anchored inflation expectations for 2026 and 2027. Copom said the prolonged period of restrictive policy has already helped slow the economy but emphasized that the total size of the easing cycle will depend on incoming data and the inflation outlook. The decision was unanimous and framed as consistent with price stability and full employment. IBOVESPA -0.7% to 168454, USDBRL -0.439% to 5.1115, 10y BGB +20.8bp to 14.492%.