Market Movers: Nervy Balance
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 6 minutes
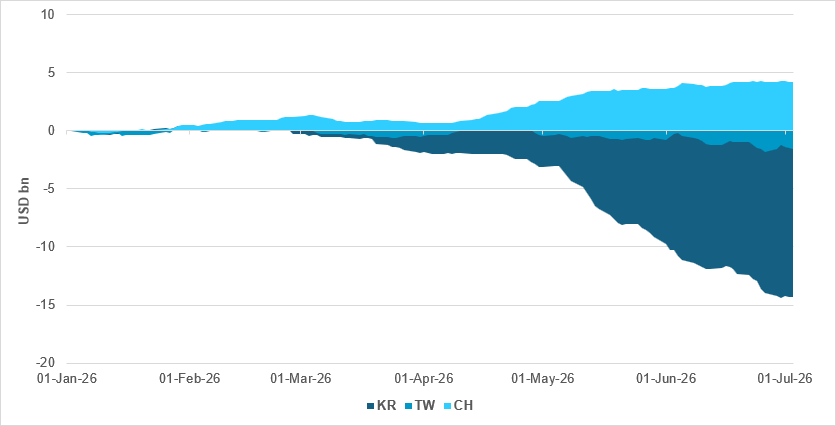
Institutional names exit South Korea, stay in China
Source: BNY
iFlow data suggest institutional investors are continuing to exit South Korean equities en masse, likely contributing to the KOSPI’s brief move into bear market territory overnight. Retail investors remain on the other side of the trade, but the market is increasingly questioning how sustainable that support is. Taiwanese equities have also benefited from the AI and semiconductor narrative, though liquidation there has been more measured in scale and pace, consistent with the relative resilience in index performance.
Single-stock ownership limits for active managers remain an important technical constraint. However, if valuations soften and institutional selling persists beyond what can be explained by this constraint, it could point to a broader behavioral shift rather than just position management. Meanwhile, our data show that interest in Chinese equities is holding up well, even as indices such as the HSCEI entered bear market territory a few weeks ago. Light accumulation between April and June points to value interest, with flows largely unaffected by weaker data and external volatility.
It is too early to call this a rotation away from the growth markets of Taiwan and South Korea into value segments elsewhere in Asia. Still, within region-specific mandates, some funds appear to be searching for new investment destinations, which could drive greater dispersion in return profiles this quarter.
Nervy markets prevailed overnight, driven by geopolitics and AI positioning. Reports of attacks on commercial vessels near the Strait of Hormuz put the energy risk premium back into focus, with bond yields up on renewed concern over inflation pass-through. In Asia, South Korea’s tech-led sell-off sharpened concerns around AI and semiconductor concentration. The KOSPI briefly flirted with bear market territory as Samsung Electronics and SK Hynix fell heavily, despite Samsung flagging a sharp quarterly profit rebound. That points to positioning, index concentration and stretched AI-linked expectations rather than weak current fundamentals. The key question is whether this remains a South Korea-specific unwind in a crowded memory/AI proxy, or whether spillovers will broaden out as earnings the season moves into full swing.
China and Europe offered more constructive signals, though not enough to offset the defensive impulse from energy and tech. China and Hong Kong announced measures to deepen Bond Connect and strengthen offshore RMB infrastructure, including broader product access, improved collateral and settlement arrangements, and a larger RMB liquidity facility. In Europe, German industrial production beat expectations in May, supported by autos and construction. Germany’s manufacturing headwinds remain significant, but recent sector surveys have improved, lowering near-term downside risk for the euro area. The BoE has also proposed easing some capital rules for banks, though appetite for re-leveraging will likely remain limited in the current environment.
The U.S. data calendar is light today, keeping the focus on Europe. In France, a verdict is due imminently on Marine Le Pen’s appeal against her five-year election ban. Any decision clearing her for a 2027 presidential run would have material implications for France and the EU, given National Rally’s current polling position.
President Trump will also attend the NATO summit in Ankara. Allies are braced for another U.S. push on burden-sharing, but the uncomfortable pressure from Washington is producing results. Germany’s defense investment plans, announced yesterday, show Europe moving from promises to fiscal commitments. For markets, that means more defense issuance, stronger domestic demand and a potential competitiveness dividend if higher investment feeds through to productivity gains.
A Qatari LNG carrier, the Al Rekayyat, was struck by a projectile near the Omani coast as it left the Strait of Hormuz, highlighting renewed security risks in the key shipping lane and testing a U.S.-Iranian understanding aimed at curbing attacks. The incident has increased concern among shipowners, pushed up European gas prices and nudged Brent higher, while also threatening QatarEnergy’s LNG export plans. Shipping data suggested the vessel may have been sailing with transponders off, and traffic through Hormuz remains fragmented as operators choose between an Iran-approved northern corridor and the U.S.-managed Oman route. The attack adds pressure to already-fragile talks on a lasting peace. Brent +1.167% to 72.83, WTI +1.095% to 69.3, Omani crude +0.815% to 64.33, Dubai crude +0.976% to 65.134.
ECB Governing Council member Fabio Panetta said in Rome that the euro area faces a fragile outlook, with upside risks to inflation still coexisting with downside risks to growth. He argued that recent peace talks between the U.S. and Iran could eventually ease energy prices but warned that monetary policy should not follow a preset path. Panetta said policymakers must keep a close watch on geopolitical developments, energy markets, supply chains, wages and inflation expectations. He framed the ECB’s latest rate increase as a recalibration after earlier oil-driven inflation pressures and suggested that recurring supply shocks may force future policy to adapt to meet the 2% medium-term inflation target. Euro Stoxx 50 -0.09% to 6392, EURUSD -0.053% to 1.1435, BBG AGG Euro Government High Grade EUR 0bp to 3.209%.
A Wall Street Journal report says NATO allies are scrambling to replace U.S. military capabilities after Washington told some members they can no longer rely on American bombers, warships, refuelers and other forces in a crisis. European leaders are discussing workarounds ahead of NATO’s annual summit in Ankara, with Secretary-General Mark Rutte saying Europeans are already backfilling some gaps, though more work is needed. The biggest challenge is replacing unique U.S. assets such as long-range strategic bombers, aircraft carriers and submarines, while midair refueling remains especially difficult. The pullback has intensified concerns about Europe’s exposure to Russia and raised debate over greater reliance on NATO’s nuclear deterrent. European defense spending has increased, but industrial bottlenecks continue to limit how quickly capabilities can be fielded.
Japan’s Growth Strategy Minister Minoru Kiuchi has rejected media reports that Prime Minister Sanae Takaichi’s government is trying to push interest rates lower, saying there is “absolutely no truth” to claims that fiscal expansion is aimed at pressuring the BoJ. He said the omission of “fiscal consolidation” from the draft basic policy guidelines was not intended to weaken fiscal discipline, but to present fiscal sustainability more concretely and verifiably. The remarks come as markets scrutinize whether the administration’s pro-growth agenda and large-scale investment plans could constrain further BoJ rate hikes. Kiuchi reiterated that the government expects close coordination with the BoJ and appropriate monetary policy conduct. His comments briefly lifted the yen, which traded near 161.86 to the dollar after the briefing. Nikkei -2.12% to 68257, USDJPY -0.118% to 161.9, 10y JGB +3.2bp to 2.859%.
The PBoC has announced new measures to deepen Hong Kong’s role as the main offshore yuan hub and to widen mainland-Hong Kong financial links. The RMB Business Facility will be expanded to ¥500bn, giving Hong Kong banks greater access to yuan liquidity, while the annual Southbound Bond Connect quota will rise to ¥800bn from ¥500bn. The central bank also said it will support more yuan-priced commodity products, advance Hong Kong’s gold clearing system trial and increase the allocation of national foreign reserves to the city. Governor Pan Gongsheng said international demand for yuan is broadening beyond trade settlement into investment, financing, pricing and reserves. He added that the PBoC will maintain a supportive monetary stance but gave no fresh signals on rate cuts or reserve ratio adjustments. CSI 300 -1.03% to 4792, USDCNY +0.012% to 6.7953, 10y CGB 0bp to 1.735%.
U.S. ADP weekly employment change is due; last week’s reading was 30.8k.
U.S. May trade balance is forecast to widen to -$78.5bn vs. -$55.9bn. Imports are forecast at 2.1% vs. 2.0% m/m. Exports are forecast at -3.5% vs. 2.6% m/m.
U.S. New York Fed 1-year inflation expectation is due; the May reading was 3.46%.
Canada May international merchandise trade is forecast at CA$2.5bn vs. CA$2.7bn.
Canada June Ivey Purchasing Managers Index is due; the May reading was 58.2.
U.S. Treasury sells $90bn in 6-week bills, $52bn in 52-week bills and $58bn in 3y notes.
Mood: iFlow Mood remained negative at -0.066, reflecting continued selling across both global equities and core government bonds.
FX: Flows were concentrated in G10 FX, with light and mixed activity elsewhere. USD inflows dominated, funded primarily by aggressive selling of GBP, CAD and EUR.
FI: Brazilian and Norwegian government bonds, alongside cross-border U.S. Treasury holdings, saw the largest outflows. Demand was strongest for Canadian government bonds and U.K. gilts.
Equities: Denmark, Hungary and India attracted the strongest inflows, while U.S., U.K., South Korean and Thai equities remained under selling pressure.
“Those who dominate technology will rule the world.” – Lee Byung-chul, founder of Samsung
“There are hardships but never failures.” – Chung Ju-yung, founder of Hyundai, whose electronics arm became the precursor to today’s SK Hynix
German industrial production rose 0.9% m/m in May, in real, seasonally adjusted, calendar-adjusted terms, after a revised 0.2% gain in April. Output was unchanged y/y. The three-month comparison showed marginal 0.1% growth. The m/m rise was driven mainly by a 3.6% jump in the auto industry and a 0.9% increase in construction, while industrial production excluding energy and construction rose 0.8%. Energy output increased by 0.8%, and production in energy-intensive industries edged up 0.2%. DAX -0.1% to 25791, EURUSD -0.053% to 1.1435, 10y Bund +2.6bp to 2.974%.
Hungarian consumer prices rose 1.7% y/y in June and were unchanged m/m. Food prices were up 0.2% on average, but services increased by 4.0% and alcoholic beverages and tobacco by 3.1%, helping to keep inflation positive. Higher prices were recorded for potatoes, catering items, theater tickets, goods transport and some personal services, while butter, pork, cheese, milk and several other food items fell. Energy prices were 2.3% lower, as gas fell sharply despite a rise in electricity. On a m/m basis, food prices eased 0.2%, services rose 0.3% and motor fuel prices were flat, indicating broadly stable inflationary pressures. Budapest SI -0.6% to 142724, EURHUF +0.077% to 353.99, 10y HGB +1bp to 5.01%.
Czechia’s flash estimate of consumer prices fell 0.3% m/m and rose 1.5% y/y in June. The release indicates that inflation remained positive but modest, with the annual rate set to be confirmed on July 10. The statement focused on the preliminary CPI reading and did not provide a detailed breakdown of the drivers behind the m/m decline or the y/y gain. The flash estimate suggests price growth remained contained in June, while the authorities noted that the figures are provisional and based on price collection completed by the 20th day of the reference month. Prague SE +0.24% to 2622, EURCZK +0.207% to 24.215, 10y CZGB -1.2bp to 4.573%.
Japan’s real earnings rose 1.4% y/y in May, below the 1.7% estimate and April’s revised 1.9% y/y figure. Nominal cash earnings increased by 3.2% y/y (vs. 3.6% in April), while contracted cash earnings rose 3.0% y/y and scheduled pay advanced by 3.0% y/y. Bonus payments slowed sharply from April’s 10.3% y/y surge to 5.2% y/y. However, hours worked fell 3.8% y/y, reversing April’s 0.2% gain, and employment increased by 0.8% y/y, slightly below April’s 0.9%. The data suggest wage gains remained firm in nominal terms, but weaker working hours limited the uplift to inflation-adjusted earnings. Nikkei -2.12% to 68257, USDJPY -0.118% to 161.9, 10y JGB +3.2bp to 2.859%.
Japan’s coincident diffusion index rose 0.4 points m/m in May to 118.5, marking a third straight monthly increase and supporting the official assessment that the underlying economic trend is improving. The leading index climbed 0.7 points to 116.8, while the lagging index fell 0.4 points to 111.5. The gain in the coincident index was helped by stronger durable consumer goods shipments and higher retail sales, alongside positive contributions from industrial production, intermediate goods shipments and wholesale sales. The employment-related index weakened slightly, and investment goods shipments also weighed on the overall reading. The government kept its basic judgment unchanged at “improvement.”
Japanese household spending fell 0.4% y/y in real terms in May, the sixth straight negative month, from -0.5% in April. The report suggests consumption remained broadly soft, but some categories held up better, including food (+2.4% y/y), housing (+0.7%), medical care (+3.3%), furniture and household utensils (+23.0%), clothing and footwear (+4.0%) and education (+21.7%). By contrast, spending weakened in fuel, light and water (-7.6%), transport and communication (-15.8%) and culture and recreation (-3.1%). The data indicate household demand remains uneven despite a rise in income (+0.7% y/y in May).
Taiwanese CPI rose 2.60% y/y and 0.52% m/m in June, while the January-June average increased by 1.70% y/y. The statistics agency said the m/m gain was driven by summer electricity tariffs, heavy rain that pushed up vegetable prices and higher holiday-related airfare and entertainment costs, partly offset by cheaper fruit, eggs and clothing. Core CPI, which excludes vegetables, fruit and energy, rose 2.45%. Producer prices fell 0.35% m/m but jumped 15.10% y/y. Import prices fell 1.33% m/m in USD terms, while export prices fell 0.35%, reflecting still-elevated commodity and manufactured goods prices y/y. TAIEX -2.31% to 45479, USDTWD +0.378% to 32.159, 10y TGB -0.1bp to 1.67%.
The Philippines’ consumer price index report for June showed headline inflation easing to 6.4% y/y from 6.8% y/y in May, while still averaging 4.8% YTD. The slowdown was mainly driven by a softer rise in transport prices (12.8% y/y vs. 16.2% y/y) and food and non-alcoholic beverages (5.2% y/y vs. 5.7% y/y), with housing, water, electricity, gas and other fuels also a major contributor to overall inflation. Food inflation eased to 5.4% y/y from 5.8% y/y, reflecting slower increases in rice, fish and seafood, corn, and oils and fats, partly offset by faster gains in vegetables and some bakery products. Core inflation edged up to 4.4% y/y from 4.1% y/y, indicating underlying price pressures remained firm. PSEi +0.37% to 6247, USDPHP -0.113% to 61.434, 10y PHGB +2.8bp to 7.036%.