Market Movers: Negotiate
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoff Yu
Time to Read: 6 minutes
EMEA carry currencies underwhelm ahead of MNB decision
Source: BNY
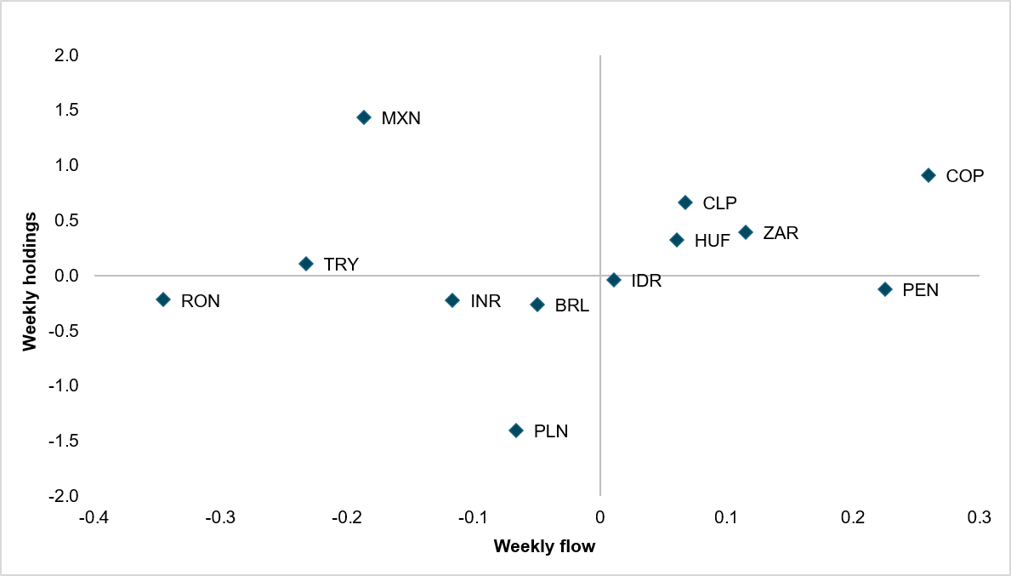
Hungary’s Magyar Nemzeti Bank (MNB) is expected to bring rates down by 25bp today. Compared to other high-yielding currencies, EMEA carry is still treading water: PLN is currently the worst-held and RON the most sold on a weekly basis. In general, the U.S. Treasury buyback announcement weakened the dollar and lowered U.S. real-rate pressure, but iFlow shows little evidence of broad carry accumulation. COP was last week’s best-bought currency, yet its flow score barely exceeded 0.3. Across the complex, low volumes and small flow magnitudes are preventing meaningful holdings improvement. The signal is not outright rejection of carry, but a lack of conviction. Investors appear willing to maintain exposure to EMEA, but not add aggressively, until the European Central Bank (ECB) trajectory and global real-rate backdrop become clearer.
HUF remains our favored carry name in the region. The currency enters today’s MNB decision well supported but lightly positioned. Fundamentals leave room for a cut while preserving a healthy rate buffer, and spot flows remain positive on a rolling three-month basis. However, buying is consistent rather than strong, scored volumes are only 0.26, and holdings have recovered to just 0.3–0.5 times the rolling 12-month average. EURHUF remains the dominant cross and likely hedging vehicle, while broader HUF longs may be funded through USD or CHF. The cleaner expression remains fixed income: Hungarian sovereign holdings are around 30% above their rolling average, compared with roughly 15% for equities. Further HUF upside requires stronger volumes, fiscal progress and clearer EU-funding momentum after further easing.
Pressure, with limits: Washington’s economic offensive against Iran still leaves substantial room for negotiation. Treasury Secretary Scott Bessent’s measures stopped short of the most destabilizing options, while Pakistan says its latest Tehran meetings made “significant progress” toward reviving talks. Futures are firmer and oil softer, suggesting markets are leaning toward de-escalation rather than an immediate shock.
China keeps talking: Beijing is pushing back without escalating. China has rejected unilateral sanctions and pledged to safeguard its economic interests, but retaliation remains absent. With Xi’s Washington summit approaching, neither side has much incentive to rupture relations; Bessent’s references to quiet diplomacy and ensuring global financial stability suggest negotiations are continuing behind the scenes.
Europe improves: Europe’s recovery is firming, but we doubt it justifies aggressive tightening. Germany’s Ifo headline, current conditions and expectations all surprised materially higher. Yet tighter rates and a stronger euro could still derail a fragile recovery. For the ECB, price stability remains non-negotiable, creating clear constraints. Hungary may set an example of what credible policy looks like, as the MNB is able to continue cutting rates, backed by a government with a clear mandate and plan for fiscal restraint.
Markets set terms: Policymakers must increasingly negotiate with markets questioning every policy signal. Nvidia earnings and Jackson Hole leave little margin for error, while today’s U.S. house price data, new home sales, revised building permits and consumer confidence will test the household side of the economy. Amid the geopolitical, corporate and policy noise, housing and consumption remain essential to U.S. resilience.
China warned it would defend its economic ties with Iran after new U.S. sanctions targeted entities in China and Hong Kong as part of Washington’s latest effort to isolate Tehran financially. Beijing said its cooperation with Iran is being conducted under international rules and should not be disrupted, while reiterating opposition to unilateral sanctions and calling for de-escalation and renewed negotiations. The U.S. measures stopped short of targeting major Chinese banks, suggesting Washington is trying to raise the cost of Iran-related trade without immediately provoking a broader confrontation with Beijing. China remains Iran’s largest oil buyer and a major trading partner, making its response critical to the effectiveness of the sanctions campaign. Beijing said it would take necessary measures to protect its interests. CSI 300 -0.24% to 4,552, USDCNY +0.003% to 6.7221, 10y CGB +0.5bp to 1.689%.
Bloomberg reports that the U.S. is preparing to impose a 7.5% tariff on Chinese goods over concerns about excess manufacturing capacity, ahead of a planned Trump–Xi summit in Washington on September 24. The move would lift Trump’s second-term duties on China to about 20%, in line with Beijing’s stated ceiling under the trade truce. Exact rates are still under discussion, and one option is to announce a higher duty while suspending part of it to arrive at the lower effective rate. The administration is also aiming to release the overcapacity probe findings before the meeting. Beijing and Washington are seeking to extend the one-year trade pact, which expires on November 10.
European stocks advanced as lower oil prices eased inflation and bond market pressure, while stronger German data added a domestic growth catalyst. The Stoxx Europe 600 rose 0.3% as Brent slipped toward $91 from Friday’s $95 high after new U.S. measures against Iran proved less severe than feared. Sentiment was also supported by upside surprises in Germany, where Q2 GDP growth was revised to 0.3% q/q from 0.2%, while the August Ifo business climate index jumped to 88.8 vs. 87.1 expected and 86.7 previously. The combination of softer energy prices, resilient earnings and better German macro data is helping support European equities, although geopolitical exposure, elevated rates and subdued late-August trading volumes remain constraints. Euro Stoxx 50 +0.35% to 6,470, EURUSD +0.018% to 1.1666, BBG AGG Euro Government High Grade EUR 0bp to 3.513%.
The Trump administration unveiled “Operation Economic Outcast,” a new sanctions plan aimed at isolating Iran’s economy through secondary sanctions on its “enablers.” Treasury Secretary Bessent said the U.S. will first send timelines to countries to shut down identified activities, rather than immediately imposing the measures. He said anyone facilitating money laundering or helping convert Iranian oil into funding for repression will be removed from the U.S. dollar system. Bessent also indicated China is not exempt, saying no one is above U.S. sanctions, and Chinese banks or entities could be targeted if they facilitate transactions for Iran. The scope also extends to Iran’s digital assets, technology, gold, aviation and shipping sectors, as Washington steps up pressure on Tehran’s financial and trade networks. Brent -1.509% to $90.78, WTI -1.718% to $83.55, Omani Crude -3.903% to $91.86, Dubai Crude -0.189% to $90.104.
Hungary’s central bank is forecast to ease 25bp to 5.5%.
U.S. ADP Weekly Employment Change, 9.5k prior.
U.S. August Philadelphia Fed Non-Manufacturing Activity, 7.4 prior.
U.S. June FHFA House Price Index is forecast to ease to 0.2% m/m vs. 0.3% m/m.
U.S. June S&P Cotality Case-Shiller 20-City Index is forecast at 0.1% m/m, 1.8% y/y vs. 0.2% m/m, 1.6% y/y in May.
U.S. August Richmond Fed Manufacturing Index is forecast to rise to 7.0 vs. 5.0.
U.S. August Richmond Fed Business Conditions, -5.0 prior.
U.S. July New Home Sales is forecast to ease to 620k vs. 628k.
U.S. August Conference Board Consumer Confidence is forecast to ease to 90.2 vs. 90.8. Present Situation is forecast to ease to 114.2 vs. 114.9. Expectations is forecast to ease to 74.4 vs. 74.7.
U.S. July final Building Permits is forecast to hold at 1443k.
Central bank speakers: Richmond Fed President Tom Barkin speaks on the economy.
U.S. Treasury sells $95bn in 6-week bills and $69bn of 2y notes.
Mood: iFlow Mood held steady at -0.099 as demand for core sovereign bonds continued to outpace global equity buying.
FX: Currency flows were mixed and moderate. USD, EUR and SGD led inflows, while selling focused on AUD and CNY. GBP attracted modest demand, while JPY outflows persisted.
FI: Sovereign bonds across APAC, LatAm and EMEA were broadly sold, led by China and Mexico. Within G10, New Zealand and Norwegian bonds saw the heaviest outflows, while Eurozone and Canadian government bonds and U.S. Treasurys attracted solid demand.
Equities: Flows were mixed. Colombia, Poland, Turkey and South Africa led inflows, while selling focused on Canada, the Eurozone and Singapore.
“Speak softly and carry a big stick; you will go far.” – Theodore Roosevelt
“I have never advocated war except as a means of peace.” – Ulysses S. Grant
Germany's Ifo business climate index for August rose to 88.8 from 86.7 in July, its highest level since August 2025 and above the 87.1 consensus estimate. The improvement reflected stronger assessments of both current conditions and expectations, while uncertainty also eased despite another rise in energy prices. The data add to evidence that the German economy is recovering, following confirmation that Q2 GDP growth was stronger than initially estimated. However, the near-term outlook remains mixed. The Bundesbank expects only slight growth in Q3, with some earlier export strength likely to unwind as stockpiling fades, while record-low river levels could create additional supply disruptions and weigh on industrial activity. DAX +0.41% to 26,213, EURUSD +0.018% to 1.1666, 10y Bund -0.1bp to 3.252%.
Germany’s Q2 2026 GDP rose 0.3% q/q, revised up from the preliminary 0.2% estimate, extending the economy’s recovery to a third consecutive quarter. Net exports were the main driver, contributing 0.2%, while private consumption and government spending each increased 0.1%. Capital investment remained a weak spot, unexpectedly falling 0.2%. Q1 growth was also revised higher to 0.4%, reinforcing evidence that activity has improved after several years of stagnation. The recovery is being supported by stronger exports and increased government spending on infrastructure and defense, although investment remains subdued. Higher energy costs, continued Middle East conflict, and exceptionally low Rhine water levels continue to pose downside risks to industrial activity and the broader growth outlook.
Japan’s June 2026 Composite Index revision shows a firmer economic picture. The Coincident Index was revised up to 118.5 from 118.2 in the flash reading, while the Leading Index was nudged higher to 116.5 from 116.4. The Lagging Index was revised down to 111.8 from 112.3. The three-month moving average of the Coincident Index rose to 118.2, and the seven-month average increased to 117.2, both signaling ongoing improvement. The official assessment was unchanged: the Coincident Index is “showing improvement.” Upward revisions reflected stronger industrial production, wholesale sales, and labor input, while the Leading Index was supported by machinery orders and housing starts. Nikkei +0.5% to 65,856, USDJPY -0.132% to 159.42, 10y JGB +1bp to 2.904%.
The Reserve Bank of Australia meeting minutes affirmed its hawkish stance. The monetary policy board judged that the economy was moving toward its objectives, with inflation easing from its March peak and underlying inflation slightly lower than in late 2025. Labor market tightness has eased somewhat, and the output gap is seen closing a little earlier than expected in May. Even so, inflation remains too high and the economy is still operating with excess demand. Financial conditions were viewed as somewhat restrictive after earlier rate increases. After weighing upside risks to inflation against the case for patience, members decided to leave the cash rate target unchanged, saying policy appears to be working to gradually rebalance the economy. They remained alert to upside risks and said they would tighten further if needed, while reaffirming their commitment to returning inflation to target in a timely way. ASX +0.17% to 5,860, AUDUSD -0.21% to 0.7145, 10y ACGB +0.5bp to 5.022%.
South Korea’s Composite Consumer Sentiment Index (CCSI) fell for the first time in four months in August on a stock market correction and rising inflation. August 2026 CCSI stood at 104.5 (-2.3 points m/m, from 106.8 in July), with all major components weakening. Views on current living standards slipped to 92 and future outlook to 97, while future household income eased to 100 and future household spending to 109. Sentiment on current domestic economic conditions dropped sharply to 79, and future domestic economic conditions fell to 89. Inflation expectations were unchanged at the short end: the one-year ahead expected inflation rate was 2.7%, while the three-year-ahead and five-year-ahead measures were both 2.6%. KOSPI +0.68% to 6,743, USDKRW -0.181% to 1386.15, 10y KTB -4.3bp to 4.327%.
Taiwan’s industrial production in July 2026 rose 25.61% y/y, with seasonally adjusted output up 4.15% m/m. Manufacturing increased 26.89% y/y (+4.30% m/m), lifting the January–July average 22.04% y/y. The gain was driven by strong demand for AI, high-performance computing, and cloud services, which supported electronics and related supply chains. Electronics components rose 22.72% y/y, while computers, electronic products and optical goods surged 95.62% y/y. Traditional industries also benefited from semiconductor-related demand and low base effects, with machinery up 19.75% y/y and basic metals 13.24% y/y. In contrast, chemical materials and fertilizers fell 5.88% y/y, and automobiles and parts declined 5.03% y/y amid weak demand and inventory adjustment. The ministry expects manufacturing output to remain supported by AI-related investment. TAIEX +0.91% to 45,169, USDTWD -0.135% to 31.897, 10y TGB +1.1bp to 1.865%.
Hong Kong’s July 2026 external merchandise trade data showed a strong rebound. Total exports rose 50.7% y/y to HK$672.5bn, easing from 53.4% in June, while imports increased 41.0% y/y to HK$677.4bn, after 45.4% in June. This left a visible trade deficit of HK$4.9bn. In the first seven months of 2026, exports and imports were up 40.9% and 40.6%, respectively. Export growth was broad-based, led by Asia, especially Taiwan, Vietnam, Thailand, the Mainland, Singapore and Malaysia; outside Asia, the U.S. and Mexico also posted strong gains. The government said AI-related electronics remained a key driver. Looking ahead, it expects demand for such products to support trade, but warned of risks from Middle East tensions, trade protectionism and rapid AI investment. Hang Seng -0.02% to 25,511, USDHKD -0.029% to 7.8383, 10y HKGB -1.2bp to 1.417%.