Market Movers: Intervention
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 5 minutes
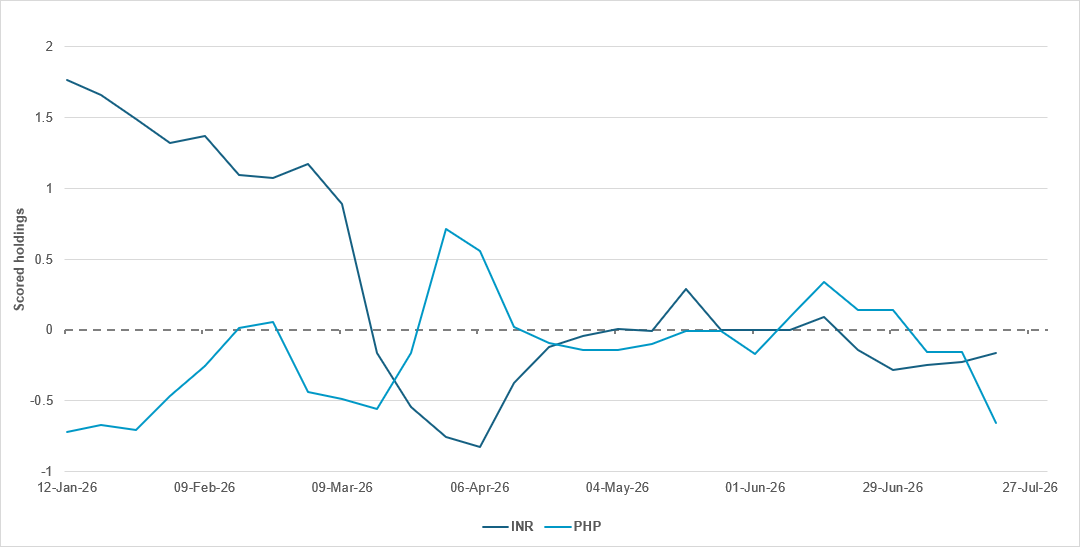
Fall in holdings indicates waning confidence in INR and PHP
Source: BNY, GPIF
The Philippine and Indian central banks have both intervened to support their currencies as surging oil prices put renewed pressure on Asian oil importers. In the Philippines, the central bank reportedly sold dollars after the peso fell to a record low of 61.75 to the dollar, with higher oil prices threatening to widen the current account deficit and add to inflation pressure. India also stepped in this week to support the rupee, reflecting a similar concern that rising energy costs could weaken external balances and intensify FX volatility. The moves show regional policymakers trying to contain imported pressure from the oil shock, especially as El Niño risks could add further stress to food prices and vulnerable currencies. Philippine reserves have already fallen more than 5% this year.
Our flow data confirm that pressure is building. Sales have already pushed PHP holdings close to their lowest level YTD. The currency does not have the carry anchor seen elsewhere, which may require much greater BSP vigilance on interest rates, despite the obvious dampening impact on growth. INR is currently underheld as well, having fallen significantly from a well-owned currency at the beginning of the year. INR holdings briefly turned positive after the ceasefire was confirmed but failed to consolidate. We still see INR benefiting from any return in carry but evidently the current level of oil prices will generate a balance-of-payments discount.
Oil pressure: Brent’s climb above $95 is a clean trigger for intervention. Higher crude is pushing governments and central banks back into defense mode, even without a fresh coordinated release of oil stocks. The pressure is hitting energy importers first via weaker current accounts, imported inflation and fragile FX. The Iran channel is not easing either: Tehran says there are currently no negotiations with the U.S., only a possible exchange of messages. That keeps the oil and shipping-risk premium alive.
Asian FX defense: Asia’s oil-importing currencies are already absorbing the shock. Japan remains at the verbal intervention stage, while the Philippines and India have moved into reported dollar selling to lean against FX weakness. This is not intervention from strength, but an attempt to slow the passthrough from higher oil into currencies, inflation and confidence.
Volatility channel: Not all intervention reduces volatility. FX support and diplomacy are trying to contain stress, but military escalation and tariffs can add to it. U.S.-Iranian tensions are keeping the energy premium in play, while Washington’s planned tariff measures raise the prospect of another policy shock. Markets are left in an uneasy equilibrium: intervention is everywhere, but the direction is not always stabilizing.
Earnings test: With U.S. data light, earnings become the stabilizing test. Alphabet, Tesla, IBM and Texas Instruments all report after Wednesday’s close, putting AI capex, margins and guidance directly in focus. Investors need evidence that heavy investment is translating into revenue or credible future returns. Macro intervention can dampen shocks, but it cannot defend equity valuations. Companies now need to defend the investment cycle themselves.
Bottom line: Intervention is back as a market theme. Oil is forcing FX defense in Asia, Japan is warning against yen weakness, and U.S. trade policy remains uncertain. The risk is that intervention slows the adjustment without removing the shock.
BoJ officials are reported to be open to raising rates faster than many economists expected, as yen weakness adds upside risks to inflation and could encourage firms to lift prices further. The central bank is still widely expected to keep policy unchanged at its July 31 meeting, after increasing the benchmark rate to a 31-year high of 1% at last month’s meeting. However, officials may act earlier than December if needed. Policymakers reportedly see underlying inflation nearing the 2% target and are shifting their focus toward keeping price growth anchored, while markets are now pricing in a meaningful chance of another hike by October. Nikkei -0.18% to 66116, USDJPY -0.221% to 163.03, 10y JGB +3.2bp to 2.762%.
U.S. Senate Majority Leader John Thune has said he will bring a short-term stopgap funding bill to the Senate floor before the August recess. Senate Republicans are still negotiating with Democrats and the White House on a continuing resolution to keep the government funded beyond the September 30 deadline. Thune said that Senate Appropriations Chair Susan Collins is talking with Democrats to seek a bipartisan deal that would extend funding until after the November election. He called a Senate stopgap the more likely vehicle because the version passed by the House of Representatives does not include White House spending requests. Thune also signaled that Republicans could resort to a party-line approach using reconciliation if no bipartisan agreement is reached, though he said that would be a last resort. S&P Mini -0.29% to 7524, DXY -0.066% to 101.107, 10y UST +0.1bp to 4.628%.
President Trump has said he plans to impose a 100% tariff on generic drugs starting in August 2028, rising to 200% in 2029 if implemented. He framed the move as part of a push to reshore pharmaceutical manufacturing to the U.S. and penalize companies that do not build plants and equipment domestically. A White House official said the administration intends to use Section 232 of the Trade Expansion Act, but no formal order has been issued yet. Generic drugs are currently exempt from the administration’s broader pharma tariffs, while branded drugs remain subject to the existing policy. The generic drug industry said it needs more details and urged the administration to address wider barriers to expanding U.S. production. S&P Mini -0.29% to 7524, DXY -0.066% to 101.107, 10y UST +0.1bp to 4.628%.
Bank Indonesia has kept its policy rate on hold at 5.75%, with a new phase of policy implementation, from interest rate to macroprudential support for the rupiah. The central bank removed any explicit tightening bias, except to continue to raise SRBI rates to attract capital inflows. Capital flow incentives were expanded, including higher hedging rewards, new local-currency transaction incentives, broader repo collateral and stronger liquidity facilities. BI said these measures are intended to deepen markets, lower transaction costs and attract more stable foreign inflows. The policy backdrop remains fragile, with a strong USD, elevated oil prices and persistent portfolio outflows still pressuring IDR. BI left its macro forecasts unchanged at GDP growth of 4.9-5.7%, CPI inflation of 1.5-3.5%, a current account deficit of 0.5-1.3% of GDP and loan growth of 8-12%, pointing to confidence in growth and inflation outlooks. JCI -0.31% to 6321, USDIDR +0.017% to 17880, 10y IDGB +0.8bp to 7.298%.
U.S. Treasury sells 17-week bills and $13bn in a 20y bond reopening.
Mood: iFlow mood was at -0.149, suggesting that risk-off sentiment has worsened over the past three sessions.
FX: G10 currencies attracted inflows, with USD, SEK and NZD all on the receiving end. However, GBP has seen sizable outflows over the past week, associated with political uncertainty around the new Burnham government.
FI: Global sovereign bonds generally saw inflows led by Chinese, Eurozone and Swedish bonds, with U.K. gilts and Treasurys also seeing inflows. Peripheral regions such as Malaysia, Peru and Hungary experienced outflows.
Equities: Global equity flows were mixed: EM Asia saw inflows, led by the Philippines and Thailand, while Hungary and Canada experienced the largest outflows.
“Striving to better, oft we mar what’s well.” – William Shakespeare, King Lear
“There is surely nothing quite so useless as doing with great efficiency what should not be done at all.” – Peter Drucker
U.K. consumer price inflation slowed further in June, with CPIH rising 2.8% y/y, down from 3.0% in May, while CPI eased to 2.6% from 2.8%. On the month, CPIH rose 0.2% and CPI increased by 0.1%. The main downward forces came from transport, and food and non-alcoholic beverages, with motor fuels, especially diesel and petrol, weighing on transport. Clothing and footwear also fell, reflecting summer discounting. Core inflation was unchanged at 2.8% for CPIH and 2.6% for CPI. Services inflation remained elevated at 3.6%, while goods inflation slowed further to 1.7%. FTSE 100 +0.89% to 10680, GBPUSD -0.306% to 1.3376, 10y gilt -0.4bp to 5.026%.
South African consumer price inflation rose to 5.0% y/y in June, from 4.5% in May, while prices increased by 0.7% m/m. The upturn was driven mainly by transport, which contributed 1.7 percentage points, followed by housing and utilities at 1.3 percentage points and insurance and financial services at 0.6 percentage points. Goods inflation edged up to 4.8% and services inflation to 5.2%. On a m/m basis, higher transport and housing costs offset smaller gains elsewhere, with fuel and passenger transport services a significant source of pressure. The survey response rate was 99.2%. JSE TOP 40 +0.24% to 101016, USDZAR -0.138% to 16.4608, 10y SAGB +4.1bp to 8.731%.
Dutch house prices rose 4.1% y/y in June, down from 4.4% in May, and 0.6% m/m. The pullback in annual growth signals a slower pace of house price inflation, though prices remain on an upward trend and were 17.3% above the previous July 2022 peak. Housing transactions also picked up, rising 7.9% y/y to 20,378 in June. Over the first six months of the year, transactions were up 5.5% y/y. The average transaction price for an owner-occupied home was €496,235, but the CBS notes that the price index is the better measure of underlying house price changes because it adjusts for differences in quality. AEX -0.21% to 1094, EURUSD -0.097% to 1.1409, 10y NGB +0.5bp to 3.268%.
Polish retail sales rose 6.2% y/y in June at constant prices, accelerating from 2.2% in June 2025, and were up 1.4% m/m. In seasonally adjusted terms, retail sales were up 4.7% y/y and 1.7% m/m. For January-June, sales were 3.5% higher than a year earlier. Broad-based gains were seen across all groups, led by furniture, radio, TV and household appliances, pharmaceuticals and cosmetics, and motor vehicles and parts. Online sales also strengthened, with their share of total retail sales rising to 9.1% from 8.7% a year earlier. WIG +0.32% to 145118, EURPLN +0.012% to 4.3296, 10y PGB +4.2bp to 5.685%.
The Wall Street Journal has reported that President Trump has formally approved a landmark U.S.-Saudi civilian nuclear agreement, opening the door to a Saudi nuclear program and potentially uranium enrichment on Saudi soil. The 30-year deal, expected to be submitted to Congress in the coming days and signed on Wednesday, would give American companies a central role in building Saudi nuclear infrastructure while excluding other foreign competitors. U.S. officials say any enrichment facility would depend on a joint U.S.-Saudi study and is intended to keep the program under U.S. influence and prevent military misuse. The accord is likely to face resistance in Congress from lawmakers worried about nuclear proliferation in the Middle East, though blocking it would be difficult. The deal was discussed during Energy Secretary Chris Wright’s April 2025 trip to the region. Tadawul +0.28% to 10728, USDSAR -0.016% to 3.7534,10y KSAB -8.2bp to 5.464%.
Japan’s trade statistics for June showed exports rising 19.3% y/y to ¥10.929tn, while imports jumped 25.4% y/y to ¥11.336tn, leaving a ¥406.9bn trade deficit, versus a ¥122.3bn surplus a year earlier. Export growth was led by transport equipment (14.4% y/y), electrical machinery (29.4% y/y) and machinery (10.9% y/y), with strong gains in shipments to the U.S. (13% y/y), China (17.6% y/y), Asia (22.7% y/y) and the EU (20.3% y/y). Imports were boosted by mineral fuels, electrical machinery and chemicals, with particularly strong increases from the U.S., China and Asia. The trade release also showed stronger trade indices: the export value and import value indices both improved, while imports outpaced exports overall. Nikkei -0.18% to 66116, USDJPY -0.221% to 163.03, 10y JGB +3.2bp to 2.762%.
Australia’s Westpac-Melbourne Institute Leading Index for June showed the six-month annualized growth rate falling to -0.36% from -0.25% in May, signaling a further loss of momentum in the economy. The update is the sixth straight below-trend reading and is broadly consistent with quarterly GDP growth stalling flat. Westpac said the slowdown reflects the earlier spike in fuel prices and the Reserve Bank of Australia’s rate hikes in February, March and May, which are weighing on activity through multiple channels. The main drags came from a narrower yield spread, weaker dwelling approvals, softer consumer expectations and a slight easing in monthly hours worked. ASX +0.78% to 5742, AUDUSD -0.328% to 0.6997, 10y ACGB +3.4bp to 4.975%.
The RBA’s “Listening to Australians: A New RBA Survey of the Community,” says inflation is the public’s top economic concern, with about two-thirds of respondents naming it among their top three issues. The survey also finds wide gaps in economic literacy, especially on how higher interest rates affect inflation, and limited awareness of some RBA responsibilities beyond setting the cash rate and targeting price stability. Public trust in the RBA is stable and broadly moderate to high, with a median score of six out of ten, but trust varies across groups and is higher among those with better economic understanding. The article highlights a clear link between higher trust and lower inflation expectations, and stresses the need for clearer, more targeted communication.
China’s public spending fell by 11.9% y/y in June, while broad fiscal revenue rose 1.8%, highlighting that fiscal tightening continued even as the economy slowed more sharply than expected in Q2. The Ministry of Finance said it would maintain a more active fiscal policy, accelerate spending and support effective investment, while officials also pledged to roll out existing measures and consider additional support to help meet the annual growth target of 4.5-5%. Local governments stepped up bond issuance for infrastructure, and new policy financing tools are expected to be deployed in Q3. CSI 300 -0.46% to 4717, USDCNY -0.088% to 6.7734, 10y CGB -1.2bp to 1.724%.
South Korea’s preliminary producer price index for June was flat m/m, after 1.0% in May, while y/y inflation held at 8.6%. By category, agricultural, forestry and marine products rose 0.7% m/m, manufacturing products fell 0.3%, electric power, gas, water and waste climbed 1.0% and services increased by 0.2%. Within manufacturing, coal products and petroleum products dropped 5.3% m/m and chemical products fell 1.8%, partly offsetting gains in computers, electronic and optical equipment. The domestic supply price index rose 0.7% m/m and 13.2% y/y, with raw materials up 2.1%. The total output price index increased by 0.4% m/m and 17.6% y/y, reflecting firmer prices across agricultural and manufactured goods. KOSPI +0.74% to 6798, USDKRW +0.156% to 1479.5, 10y KTB -1.2bp to 4.33%.
Taiwan’s manpower survey results for June showed that the labor market remained broadly stable, with total employment rising by 3,000 m/m to 11.637 million and by 20,000 y/y. The unemployment rate edged up to 3.34% from 3.27% in May, while the seasonally adjusted rate rose to 3.33%. The number of unemployed people increased to 402,000, up 9,000 from a month earlier but down 2,000 y/y. Labor force participation improved to 59.56%, up 0.06 percentage points m/m and 0.18 percentage points y/y. Employment gains came mainly from industry, while agriculture and services eased. TAIEX +1.34% to 44826, USDTWD -0.093% to 32.375, 10y TGB +1bp to 1.75%.