Market Movers: Growth Mandate
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 9 minutes
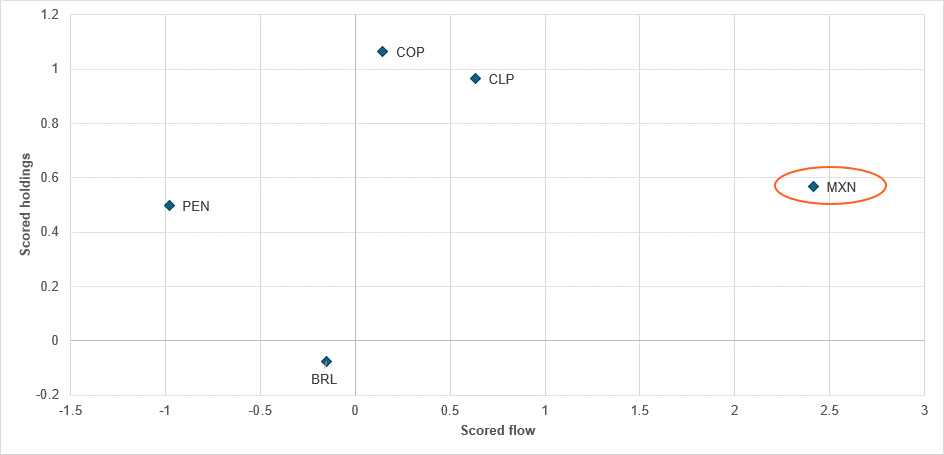
MXN flows are the outlier in Latin American FX
Source: BNY
Banxico is expected to hold at 6.50% today, but positioning says markets are leaning for more. Last week’s IMM flow drove a sharp jump in interest and left MXN strongly bid heading into the decision. We had already flagged a turn in carry demand, and MXN has become the clearest expression of this. Wednesday’s flow was exceptional even by IMM standards, roughly double the previous record from June 2024. That said, the recovery in buying had already been building since the second half of May.
Before the IMM date it was neutrally held, which helped drive the sharp mean-reversion move. Elsewhere in the region, flow signals have been much less supportive. COP and CLP were already comfortably overheld, so their one-week purchase flow has stayed soft. BRL remains slightly underheld, and flows have been neutral. That leaves BRL better-placed if carry demand strengthens again, especially given its much higher real rates. MXN’s real yield is lower, and without a high bar from Banxico it will be hard to extend the current flow momentum.
The current flow/holding setups for MXN limits risk reward in chasing currency strength. The easy mean-reversion move has already happened, positioning is stretched and Banxico needs to clear a high bar to keep this rally alive. Rotation into stronger carry elsewhere in LatAm, especially BRL, looks a better option. For Mexico, hedged fixed income exposure looks preferable to outright FX longs.
The relief is palpable across equity markets, as U.S. tech earnings indicate that investment momentum in semiconductors remains intact. If demand remains in place, funding will remain available, even if the cost is an increasingly narrow breadth of stock market performance. Relief is also coming from the fading impact of global supply shocks. Shipments through the Strait of Hormuz are continuing to normalize, while the EU has also ratified its new trade agreement with the U.S. ahead of President Trump’s deadline. In the context of tariffs and the costs imposed on the global economy, the pre-“Liberation Day” status quo is not returning. However, the past 12 months have seen significant mitigation, and markets have adjusted to a new equilibrium, part of which involves higher neutral rates.
More dual mandates: Independence-minded central banks will need to acknowledge that narrow inflation mandates are becoming politically untenable. Reports overnight suggest the economic team around likely incoming U.K. Prime Minister Andy Burnham is proposing giving “greater weight to growth” alongside price stability. While the Fed, RBA and (until recently) the RBNZ all retain employment mandates, recent experience suggests these have not prevented hawkish pivots. We believe the ECB’s strict adherence to price stability will become increasingly problematic as growth-starved euro area governments begin to question the cost of having ceded monetary policy autonomy.
Fiscal space: Japanese Prime Minister Sanae Takaichi has unveiled a long-term economic strategy, but markets will again question how its investment plans square with the fiscal realities. The program – costing the equivalent of $2.3tn and coming on top of short-term measures such as the two-year VAT cut on food – rests on assumptions about fiscal space that are difficult to reconcile with Japan’s growth outlook. Amid skepticism over the BoJ’s ability to provide a monetary offset, markets remain unconvinced by the outlook for real rates, pushing JPY to a near-four-decade low against the dollar. We expect markets to increasingly give such plans short thrift, while rewarding credible fiscal tightening, such as Indonesia’s proposal to cut its popular but costly free meals program by 15%.
Hormuz tolling: Shipping companies are reporting further improvements in Strait of Hormuz transits, helping oil prices extend their fall. However, rhetoric from the meeting between ministers from the U.S. and Gulf states overnight suggests that the governance of the strait will become a critical issue as talks progress. The UAE warned that “imposing a fait accompli born of aggression” would sow seeds for future conflict, a situation which “precisely applies” to the strait. U.S. Secretary of State Marco Rubio echoed these comments, highlighting that Hormuz tolling would set an “unacceptable precedent” and that President Trump has been “fundamentally clear” about the matter. Meanwhile, Iraq has warned that it could leave OPEC if quotas are not raised, underscoring the new post-conflict realities for the global oil market.
Bottom line: The AI/semiconductor rollercoaster continues, but investors remain confident that the path still points toward growth. Higher risk premiums are being realized through volatility rather than weaker performance, creating an opening for positions that offer better risk-adjusted returns. Without prejudice to consensus sentiment, we see a stronger performance case for assets with attractive real-return profiles but poor positioning, as flows remain crowded into technology. However, sustained diversification will require more compelling alternatives to the technology trade. FX carry and fiscally disciplined emerging markets are among the few areas beginning to provide them.
Asian technology stocks have rallied after stronger-than-expected updates from Micron and Qualcomm reinforced confidence in the outlook for AI-related demand. Micron said customers had committed $22bn for memory chips, while Qualcomm forecast $15bn in data center revenue by 2029, easing recent concerns that AI valuations had become overstretched. Japan’s Nikkei rose more than 4%, South Korea’s KOSPI gained 5.5% and the broader Asia Pacific equity index advanced 1.6%, with U.S. technology futures also moving higher. Sentiment was further supported by SK Hynix’s plan to raise up to $29.5bn through a Nasdaq secondary listing to capitalize on strong investor demand for AI stocks. Despite the rebound, analysts cautioned that elevated valuations are likely to keep volatility high across the sector. MSCI Asia -0.23% to 275, USD vs. APAC FX Index +0.343% to 105.3296, BBG AGG APAC Government High Grade USD -0.9bp to 4.908%.
German consumer sentiment for July came in at -29.2 points, edging up from a revised -29.7 in June, according to the Nuremberg Institute for Market Decisions and GfK. The survey showed households remaining cautious, with income expectations improving only slightly to -12.2 from -13.0, while willingness to buy was still deeply negative at -13.4. Economic expectations also improved to -8.7 from -11.2, but willingness to save was unchanged at 13.9. Reuters said the reading suggests sentiment is stabilizing at a low level rather than recovering toward conditions before the Iran conflict. The survey was conducted from June 4 to June 15. DAX +0.29% to 24812, EURUSD -0.036% to 1.1354, 10y Bund +0.7bp to 2.872%.
Spanish GDP rose 0.6% q/q in volume terms in Q1, down slightly q/q, while y/y growth accelerated to 2.7% from 2.6%. Domestic demand was the biggest growth driver, adding 3.5 percentage points y/y, while external demand subtracted 0.8 points. Household consumption increased by 0.6% q/q and government spending by 0.5%, while investment edged up 0.1%. Exports and imports both declined q/q. On the supply side, all major sectors except construction posted gains. Employment and hours worked also rose, and GDP at current prices increased by 6.0% y/y. IBEX 35 +0.17% to 19346, EURUSD -0.036% to 1.1354, 10y Bono +0.6bp to 3.344%.
Advisers to Andy Burnham – most likely the next U.K. prime minister – are considering a broad overhaul of the country’s economic policymaking framework, including breaking up the Treasury and reforming the Bank of England to place greater emphasis on economic growth. Former BoE Chief Economist Andy Haldane and former Transport Secretary Louise Haigh have argued that separating the Treasury’s growth and fiscal responsibilities would reduce excessive fiscal caution and improve long-term policymaking. Proposals include creating a standalone economics ministry and relocating parts of it outside London. Haigh has also suggested reviewing the BoE’s mandate to strengthen coordination with government economic policy and give greater weight to growth alongside price stability. While the ideas are gaining attention within Burnham’s team, some advisers have warned that changing the bank’s remit could undermine market confidence by raising concerns about inflation and central bank independence. FTSE 100 -0.05% to 10457, GBPUSD +0.092% to 1.318, 10y gilt +1.8bp to 4.702%.
Japanese Prime Minister Sanae Takaichi has unveiled a long-term economic growth and investment roadmap, outlining more than ¥370tn of public and private spending over the 14 years to March 2041. The plan allocates ¥101.6tn to AI and chips, with a major emphasis on semiconductors, cloud computing, batteries, vertical AI and next-generation wireless technologies. The government is aiming to build a “strong and prosperous investment framework” and strengthen economic security, supply chain resilience and long-term growth potential. Officials also released three fiscal scenarios; in the most optimistic case, debt-to-GDP declines, while in the other two it rises again in the 2030s. The plan has drawn skepticism because of its long horizon and limited clarity on the public-private funding split, raising questions over implementation and market impact. Nikkei +4.61% to 72366, USDJPY +0.031% to 161.83, 10y JGB -4.2bp to 2.634%.
BoJ board member Naoki Tamura has said the bank should continue lifting rates every few months and consider accelerating hikes if upside inflation risks intensify. Tamura said his baseline path is a 25bp increase at intervals of a few months, with the policy rate moving toward a neutral level of around 2%. Tamura argued that the BoJ’s mission is to safeguard price stability while maintaining close communication with the government. His comments reinforce expectations of further tightening after last week’s hike to 1%, the highest since 1995, and suggest he would not support another move as early as July unless inflation pressures worsen materially.
Indonesia is preparing to scale back President Prabowo Subianto’s flagship free meals program as fiscal and governance pressures mount. Officials are weighing a budget reduction of more than $2bn, with the National Nutrition Agency reportedly targeting at least a 15% cut from this year’s IDR 268tn allocation. The plan could also reduce the number of beneficiaries to 49 million from 62.5 million and pause the expansion of new kitchens. The Finance Ministry said it is awaiting a sharpened budget plan, while the rollback follows the dismissal and arrest of the agency’s former head on mismanagement and corruption charges. JCI +2.05% to 6004, USDIDR -0.073% to 17930, 10y IDGB -5.1bp to 7.167%.
Australian labor force data for May showed modest improvement, with seasonally adjusted employment rising by 40,300 to 14,738,800 and the employment-to-population ratio edging up to 63.8%. The unemployment rate fell 0.1 percentage points to 4.4% as the number of unemployed people dropped by 18,300 to 671,300, while participation was broadly steady at 66.7%. Underemployment increased slightly to 5.9%, and monthly hours worked fell by 22 million to 2.010 billion, suggesting softer labor input despite higher employment. In trend terms, employment also rose, but unemployment remained at 4.4%. ASX -0.01% to 5619, AUDUSD -0.087% to 0.6895, 10y ACGB -3.4bp to 4.728%.
Mood: iFlow Mood continued to narrow as selling in core government bonds intensified, partly offset by a slower pace of equity outflows.
FX: FX flows remained highly volatile, with multiple extreme moves across the iFlow universe. AUD, NZD, SEK, DKK, MXN, CZK, ILS, TRY and THB saw significant inflows, while JPY, NOK, PEN, HUF, PLN, ZAR and KRW recorded equally large outflows. USD flows were fairly subdued, with moderate inflows directed instead toward EUR and GBP.
FI: Eurozone and Indian government bonds remained the most favored fixed income markets, followed by the U.K., Mexico and Peru. Outflows were limited, with the Philippines the only notable market facing meaningful selling pressure.
Equities: Equity flows diverged across regions, with moderate outflows from the Americas offset by demand in EMEA and stronger buying across APAC. China, India and Malaysia attracted significant inflows, while South Korea and the Philippines experienced substantial selling.
Banco de México (Banxico) is forecast to keep rates unchanged at 6.50%.
U.S. May personal income is forecast to rise to 0.4% m/m vs. 0.0% m/m.
U.S. May personal spending is forecast to rise to 0.6% m/m vs. 0.5% m/m. Real personal spending is forecast to rise to 0.2% m/m vs. 0.1% m/m.
U.S. May PCE Price Index is forecast at 0.5% m/m, 4.1% y/y vs. 0.4% m/m, 3.8% y/y in April. May Core PCE Price Index is forecast at 0.3% m/m, 3.4% y/y vs. 0.2% m/m, 3.3% y/y in April.
U.S. Q1 third estimate of GDP is forecast to hold at 1.6% q/q vs. 1.6% q/q, with personal consumption holding at 1.4% q/q vs. 1.4% q/q, the GDP price index at 3.5% q/q vs. 3.5% q/q and the core PCE price index at 4.4% q/q vs. 4.4% q/q.
U.S. initial jobless claims are forecast to ease to 225k vs. 226k.
U.S. May preliminary durable goods orders are forecast to fall to -5.0% m/m vs. 8.0% m/m. Durable goods ex transportation are forecast to ease to 0.6% m/m vs. 1.1% m/m, with capital goods orders non-defense ex-air rising to 0.6% m/m vs. -1.0% m/m and capital goods shipments non-defense ex-air rising to rise to 0.5% m/m vs. 0.4% m/m.
U.S. May Chicago Fed National Activity Index is forecast at 0.12 vs. 0.14.
U.S. June Kansas City Fed Manufacturing Activity is forecast at 6.0 vs. 8.0.
Canada April payroll employment change is due out; the March reading was -31.8k.
Central bank speakers: New York Fed President John Williams gives keynote remarks at Crane’s Money Fund Symposium.
U.S. Treasury sells 4-week bills, 8-week bills and $44bn in 7y notes.
“Growth is never by mere chance; it is the result of forces working together.” – James Cash Penney (founder of J.C. Penney)
“Productivity isn’t everything, but in the long run it is almost everything.” – Paul Krugman