Market Movers: Fortification
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Geoffrey Yu
Time to Read: 5 minutes
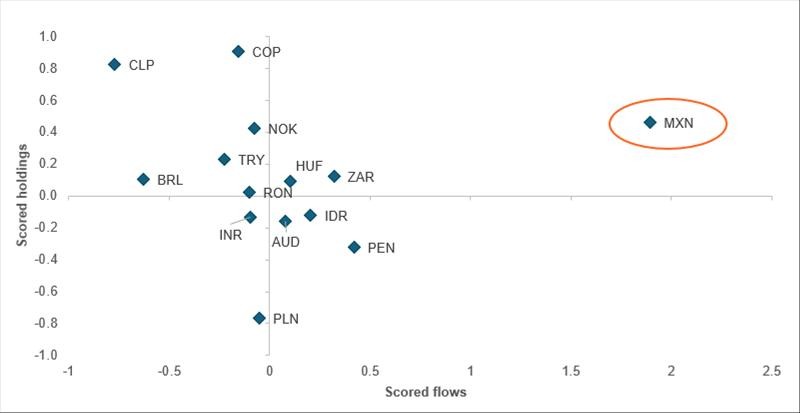
MXN is the most-bought carry currency ahead of today’s Banxico decision
Source: BNY
MXN is heading into the Banxico decision with flow momentum running well ahead of the underlying asset story. Forward and swap demand has surged twice in the last two months, leaving MXN the best-bought currency on a weekly basis and fifth-best over the past month. Spot demand has also been firm, but the broader picture is less convincing: volumes remain weak outside the surge sessions, equity flows are deteriorating, sovereign bond demand is only modestly positive and there is no clear energy or terms-of-trade premium. A softer Fed backdrop is helping carry, but Banxico easing, weaker real rate support and persistent U.S. trade uncertainty limit the case for further outperformance.
The most revealing element is the gap between recent buying and underlying holdings. MXN flows are exceptionally strong within carry names, yet positioning is only moderately positive once the transaction-driven spikes are smoothed. The more sustainable holdings level appears to be more like 0.2x the rolling 12-month average, well below holdings spikes driven by one-off surges. This suggests that the buying has not yet translated into durable conviction and could unwind, as it did after the June episode.
Mexican asset flows offer little confirmation. Equity interest is the weakest in Latin America, while sovereign bond holdings remain above average but are trailing behind stronger regional markets such as Colombia and Argentina. Our preferred stance is therefore cautious: to avoid chasing MXN, use further strength to reduce exposure or add protection, and favor Latin American carry markets with stronger asset flow sponsorship.
Industrial walls: Washington is preparing tariffs on polysilicon to reinforce semiconductor supply chains and reduce dependence on China-controlled production. The measure extends protection beyond finished chips to the materials underlying them. It may raise near-term input costs, but the strategic logic is clear: efficiency matters less when a rival controls a critical chokepoint.
Reinvestment moat: Seoul is fortifying from within. Industry Minister Kim Jung-kwan opposes distributing semiconductor windfalls and wants profits to be recycled into research, capacity and next-generation chips. South Korea’s concern is not its current position, but how quickly that advantage could erode as Chinese competitors scale up. However, this defensive policy stance has not restored confidence: Samsung fell 6% and SK Hynix nearly 10%, while Kioxia and Tokyo Electron also sold off sharply. Strong results are no longer enough when expectations, capital requirements and positioning are stretched.
Fiscal armor: Sovereign balance sheets are competitive assets too. Australia has retained its AAA rating and stable outlook, although S&P warned that fiscal outcomes and weak per capita growth remain downside risks. Reports suggest Germany faces a similar debate, as soft growth and deteriorating fiscal performance raise concerns over its own AAA status. Losing that advantage would increase financing costs and reduce policy space just as governments are trying to strengthen industrial and defense capacity.
Payrolls pre-positioning: The calendar is light. Attention remains on U.S. earnings and labor data. Jobless claims are due as markets adjust their positioning ahead of tomorrow’s payrolls report. Investors are also awaiting further details on the Iran-Oman framework for shipping through the Strait of Hormuz and how it might fit into a broader U.S.-Iranian agreement. Progress would ease a major supply risk, but the durability of any arrangement remains uncertain.
Bottom line: Fortification is the dominant policy instinct: tariffs, reinvestment and fiscal discipline. Governments and companies are willing to pay for resilience when competitive advantages can disappear quickly. But protection does not guarantee confidence, as Asia’s overnight tech selloff shows. Markets will reward credible defenses but punish fortresses built on weak economics, unrealistic expectations or policies that disincentivize innovation.
Oil prices have steadied at close to $80/barrel as traders digested Iran’s claim that it had reached an agreement with Oman on a proposed shipping route through the Strait of Hormuz. The possible route, which officials said could operate for two to four months, supported hopes that some energy flows may resume, even though it would not amount to a full reopening and U.S. backing remains unclear. Brent fell as markets priced in a lower probability of a prolonged disruption, but traders remain cautious given continued shipping risks, including reported explosions near Oman and Houthi threats against tankers. Larger U.S. crude inventories and improved stocks at Cushing also eased pressure, while fresh disruption at a Black Sea export terminal kept supply risks in view. Brent +0.579% to 79.91, WTI +0.32% to 75.46, Omani crude -0.609% to 78.35, Dubai crude +1.775% to 76.987.
The Trump administration is preparing a 15% tariff and minimum import prices on polysilicon-related products, escalating efforts to protect U.S. supply chains for solar panels and semiconductors against Chinese competition. The expected proclamation is set to cover polysilicon, wafers, cells and modules, combining tariffs with price floors in a hybrid system designed to prevent low-cost imports from undercutting domestic production. The move follows a national security investigation into polysilicon and reflects Washington’s concern that China is expanding its influence across the chip and clean-tech supply chain. It also creates tension with the U.S. solar industry, which needs affordable inputs just as federal support for renewable energy has been rolled back. The measure therefore represents both industrial policy and trade protection. S&P Mini +0.09% to 7757, DXY +0.082% to 99.757, 10y UST +1.3bp to 4.625%.
South Korea’s industry minister has warned that the country risks losing its semiconductor edge unless policy helps chipmakers reinvest faster, especially as China accelerates investment at what he described as extraordinary speed. Kim Jung-kwan framed the issue as a strategic race rather than a debate about distributing the sector’s windfall, arguing that chip profits should be recycled into capacity, technology and infrastructure instead of being shared more broadly. South Korea still controls around 65% of the global memory chip market, but the minister said speed matters because customers rarely switch suppliers once chips are adopted. The comments point to a policy preference for supporting power, water and investment bottlenecks, while resisting measures that could dilute shareholder returns or slow corporate reinvestment. KOSPI -4.58% to 6296, USDKRW +0.19% to 1426.45, 10y KTB -10bp to 4.155%.
S&P has affirmed Australia’s AAA rating with stable outlook, citing strong institutions, a wealthy and diversified economy, credible monetary policy and still-modest public debt. The agency expects the general government deficit to remain around 1.6% of GDP over the next two years, while net debt stabilizes near 28% of GDP by fiscal 2029. The rating is supported by resilient policy frameworks, but the report also flags slower growth, with real GDP expected to ease to 1.5% in fiscal 2027 as higher rates weigh on demand. Inflation remains above target, productivity is weak and per capita GDP has declined in ten of the past 15 quarters. Downside risks include weaker fiscal outcomes and softer per capita growth. ASX +0.18% to 5875, AUDUSD -0.255% to 0.704, 10y ACGB +1.6bp to 4.922%.
The Czech National Bank is expected to keep rates unchanged at 3.75%.
Banxico is expected to keep its overnight rate at 6.50%.
Initial jobless claims are forecast to rise to 205k up from last month’s 197k.
Wholesale inventories are expected to remain steady at 0.3%.
S&P Global Canada Composite PMI will be in focus after last month printed at 47.9.
Mood: iFlow mood has improved for much of the week on the back of equity inflows. Nevertheless, it remains in risk-off territory.
FX: FX flows in the G10 space were slightly skewed toward outflows, with JPY, USD and NZD all facing selling pressure. MXN, SGD and EUR all saw inflows.
FI: Fixed income flows were fairly mixed, with Danish and Eurozone sovereign bonds seeing inflows while more peripheral countries such as Norway, the Philippines and Peru posted some of the largest outflows on a scored basis.
Equities: Global investor sentiment toward equities continued to improve: there were sizable inflows into Poland, Denmark and India, while outflows continued in Canada, Hungary and Mexico.
“The power of producing wealth is therefore infinitely more important than wealth itself.” – Friedrich List
“The philosophy of protectionism is a philosophy of war.” – Ludwig von Mises
Germany’s manufacturing orders rose 3.1% m/m in real, seasonally adjusted, calendar-adjusted terms in June, with orders up 6.5% y/y, though the strength was heavily flattered by large orders. Excluding major orders, new orders fell 0.5% m/m, while the less volatile three-month comparison showed a 1.3% rise overall but no change excluding large orders. The m/m gain was driven by machinery (+12.7%), electronic and optical products (+22.7%) and autos (+3.8%), while other transport equipment fell 41.7% from May’s high level. Domestic orders rose 7.8%, but foreign orders increased by just 0.2%, as Eurozone demand fell 14.0% and non-Eurozone orders rose 10.2%. Real manufacturing turnover fell 1.3% m/m. DAX -0.07% to 26108, EURUSD -0.087% to 1.1543, 10y Bund +0.9bp to 3.12%.
U.K. construction PMI for July came in at 44.7 points, up from 38.4 in June, indicating that activity still contracted but at the slowest pace in four months. Output fell across all three main subsectors, with commercial work proving the most resilient, civil engineering the weakest and housebuilding decreasing at the mildest pace since October 2025. New orders fell only modestly, employment declines eased and supplier delivery times improved. Input cost inflation also slowed to a five-month low, while business expectations for the year ahead strengthened to the highest level since February as firms saw signs of better tender opportunities and more stable demand. FTSE 100 +0.21% to 10911, GBPUSD -0.045% to 1.3462, 10y gilt +1.6bp to 4.906%.
Swiss labor market data for July showed a further deterioration, with the unemployment count rising to 139,276, up 1,525 m/m and 10,122 y/y, while the unemployment rate increased by 0.1 percentage points to 3.0%. Seasonally adjusted unemployment also edged up to 148,002, although the rate remained at 3.1%. Youth unemployment climbed to 12,294 and the rate rose to 2.8%, while unemployment among older workers increased to 38,745. The number of jobseekers reached 227,200, and vacancies fell to 45,156, though they remained higher than a year ago. SMI +0.41% to 14611, EURCHF +0.108% to 0.93346, 10y Swiss GB -0.5bp to 0.372%.
Sweden’s flash CPI inflation for July slowed to 0.2% y/y from 0.7% in June, with prices falling 0.3% m/m as lower energy prices pulled headline inflation down. The CPIF measure also eased significantly, slowing to 0.7% y/y from 1.3%, with the same 0.3% m/m decline. The release points to a clear energy-driven disinflationary impulse in July, lowering both CPI and fixed-interest-rate inflation before the full data are published on August 13. However, underlying price pressure was firmer outside energy: CPIF-XE rose to 0.6% y/y from 0.4% in June and increased by 0.4% m/m, suggesting the headline easing was not broad-based across the inflation basket. OMX +0.1% to 3330, EURSEK -0.223% to 10.9359, 10y Swedish GB +3bp to 2.993%.
Hungarian industrial production rose 10.1% y/y in June in unadjusted terms, while working-day-adjusted output increased by 4.1%, reflecting two extra working days compared with June 2025. On a seasonally and working-day-adjusted basis, industrial production fell 1.4% from May 2026. Output increased in most manufacturing subsectors, with transport equipment, computer, electronic and optical products, and electrical equipment among the main contributors to growth. By contrast, food products, beverages, and tobacco declined y/y. Over the first six months of 2026, industrial production was 2.4% higher than in the same period of 2025. Budapest SI -0.18% to 147817, EURHUF +0.36% to 363.03, 10y HGB -7bp to 5.4%.
Czech industrial production rose 1.2% m/m and 4.0% y/y in June, showing continued broad-based growth across most activities. The increase was supported by higher output in other transport equipment, especially rail vehicles and aircraft parts, as well as fabricated metal products and computer, electronic and optical products. The y/y comparison was also boosted by lower electricity production a year earlier, while pharmaceuticals and wood processing weighed on overall performance. New industrial orders strengthened further, rising 13.1% y/y and 6.0% m/m, with foreign orders up 19.5% and domestic orders up 2.2%. Employment in industry fell 1.1% y/y. Prague SE +1.19% to 2802, EURCZK +0.025% to 24.188, 10y CZGB +0.9bp to 4.804%.
Australia’s trade balance for June came in at a surplus, as exports rose sharply and imports edged lower. The Australian Bureau of Statistics reported a surplus of AU$1.9bn, versus forecasts of an AU$1.1bn deficit, after May’s surprise shortfall. Exports climbed almost 10% m/m, led by stronger shipments of metal ores and minerals, and coal, while imports slipped 0.2%. Export values reached almost AU$50bn, the highest figure since early 2023, helped by gold exports that exceeded AU$7bn. The result was better than expected, but the broader trade outlook remains weaker as commodity prices soften and fuel imports rise. ASX +0.18% to 5875, AUDUSD -0.255% to 0.704, 10y ACGB +1.6bp to 4.922%.
Taiwan’s CPI rose 2.54% y/y and 0.31% m/m in June, with the m/m increase driven by weather-related rises in vegetables and fruit, higher egg prices and stronger summer travel costs, partly offset by lower fuel and clothing prices. Core CPI, excluding fruit, vegetables and energy, rose 2.38% y/y, while CPI excluding fruit and vegetables rose 2.60%. The y/y increase was broad-based, with transport and communication lifted by fuel and airfares, recreation by travel fees and computer-related goods, and food by dining out, vegetables, eggs, seafood and meat. PPI inflation remained much stronger at 16.94% y/y and 0.60% m/m, while import and export prices in USD terms rose 16.64% and 19.71% y/y, respectively. TAIEX -0.48% to 44397, USDTWD -0.171% to 32.248, 10y TGB +6.1bp to 1.96%.