Market Movers: Eye of the Storm
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Bob Savage
Time to Read: 6 minutes
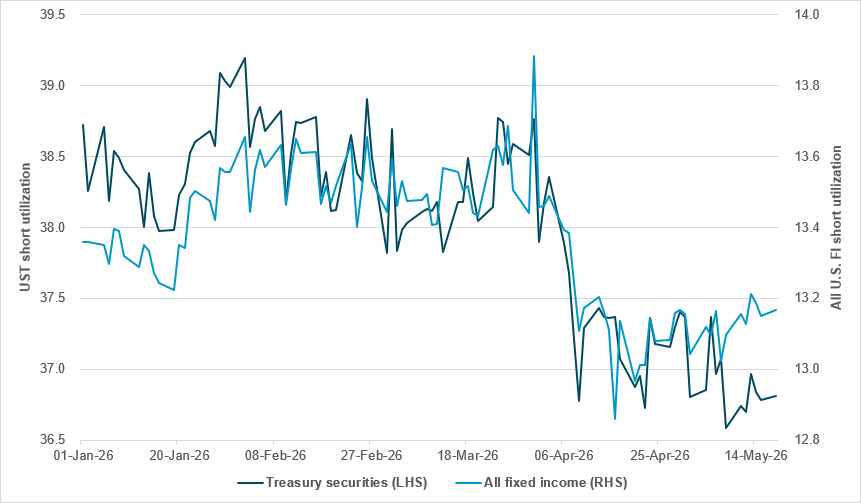
Limited interest in adding to U.S. Treasury shorts despite steepening
Source: BNY
30y Treasury yields rose to their highest level since 2007 on Tuesday, and long-dated bond yields across many nations are starting to break multi-decade records on fears that an extended energy supply crunch will lead to prolonged inflation. Risk sentiment is starting to react, mostly in the form of equity markets and a recovery in the dollar, but we continue to see very limited interest in adding to “long-inflation” positions, especially in fixed income.
Europe is far more at risk of stagflation and faces a stronger local policy response, but fixed income sales are limited for now. In the U.S., Fed cuts are difficult to envisage right now, but based on our short utilization data there is no sign that markets are willing to price in hikes either. Judging by figures from the BNY lending program, neither U.S. Treasury nor total U.S. bond short utilization is picking up aggressively. Fears of low real rates causing a steep curve have already produced higher levels of short utilization since the beginning of the year, and there have been clear spikes during the more intense phases of the conflict. However, the ceasefire initiated a sharp decrease in these positions, and despite the recent moves in long-dated yields globally and with economic data confirming higher inflation risks, short utilization is not responding.
We are in the eye-of-the-storm moment for markets. Risk sentiment remains negative, but ranges across asset classes are modest and curtailed ahead of the U.S. session, which will bring the FOMC minutes and Nvidia earnings, plus key earnings reports from Target, TJX and other retailers. APAC equities are lower along with EMEA, but U.S. futures are higher. Bonds in the U.K. led a rally aided by modest CPI. However, the raw nerve of rates breaking valuations from stocks to EM bonds and FX remains in place. What is different is that oil prices are lower despite ongoing escalation threats from President Trump, who has warned Iran of more military action if it doesn’t agree to peace terms within “two or three days.”
Bottom line: The U.S. session is holding out for more information, and yet the key concerns about oil and inflation will likely persist into the long holiday weekend ahead. The bond market rout relief today will also be in focus, as the FOMC minutes and Nvidia earnings will drive ongoing policy and growth hopes. The ability to look through the fog of war is being tested today, with the relative calm not expected to last. Worries about the politics of the war are also clouding up the market’s views for H2 risk. Midterm elections and risks of policy shifts represent another tail risk for investors, as they hope for AI productivity and returns from data centers along with a quick resolution to the energy supply shock from the Iran war.
The U.S. Treasury has sanctioned over 50 Tehran-linked entities, including oil and gas tankers and the Amin Exchange, an Iranian foreign currency exchange, as part of its “Economic Fury” campaign to pressure Iran into negotiations and reopen the Strait of Hormuz. The sanctions target a network of companies based in Iran, China, Hong Kong and the UAE, along with 19 vessels in Iran’s shadow oil fleet. Treasury Secretary Scott Bessent urged U.S. allies to enforce sanctions aggressively, emphasizing the need to dismantle Tehran’s shadow banking and shipping operations to curb its manipulation of the international financial system. S&P Mini +0.16% to 7390, DXY +0.076% to 99.402, 10y UST -1.9bp to 4.647%.
NATO is considering a mission to ensure safe passage for commercial vessels through the blocked Strait of Hormuz if it remains closed by early July. While several NATO members support the idea, unanimous approval is lacking. This potential mission marks a strategic shift amid the U.S.-Israeli conflict with Iran, which led to the strait’s closure, disrupting about 20% of global oil and LNG supplies. Economic impacts are severe, with rising energy prices and lower growth forecasts. NATO leaders will discuss the issue at their July 7-8 Ankara meeting, though no formal U.S. request for NATO involvement has been made. MSCI World -0.59% to 1092, DXY +0.076% to 99.402, BBG Global Aggregate 0bp to 3.952%.
Chinese President Xi Jinping and Russian President Vladimir Putin have met in Beijing, marking 25 years of Sino-Russian friendship. They emphasized strong, positive momentum in bilateral cooperation despite external challenges. Xi highlighted the unyielding political trust and strategic coordination between the two nations. The leaders discussed urgent calls for a ceasefire in the U.S.-Israel-Iran conflict and stressed the importance of negotiations. Putin’s visit, accompanied by a large delegation, aims to deepen coordination, particularly on energy security in the context of the ongoing Ukraine war. Around 40 agreements covering the economy, tourism and education are expected to be signed, reinforcing the countries’ strategic partnership. CSI 300 -0.04% to 4851, USDCNY +0.096% to 6.8071, 10y CGB +0.1bp to 1.746%.
Bank Indonesia has raised its key interest rate by 50bp to 5.25% to stabilize the rupiah amid heightened global volatility from the Middle East conflict. Governor Perry Warjiyo emphasized intensified foreign exchange interventions via offshore and domestic NDFs, spot markets and improved monetary policy instruments to maintain liquidity and support rupiah stability. The move aims to keep inflation within the 1.5-3.5% target range for 2026-2027 despite global energy price pressures. GDP growth is forecast at 4.9-5.7% for 2023, supported by government spending, while the current account deficit is expected at 0.5-1.3% of GDP in 20.26. JCI -0.63% to 6331, USDIDR -0.565% to 17605, 10y IDGB +3.4bp to 6.812%.
FOMC minutes for the May meeting, where three members dissented on the statement and one for a 25bp rate cut. The focus will be on rate hike risks ahead.
Earnings reports from TJX, TGT, LOW and (after the close) NVIDIA – with the focus on semiconductor orders and outlooks, data center revenues and new products.
Central bank speakers: Fed Governor Michael Barr speaks on consumer financial health metrics.
U.S. Treasury sells $69bn in 17-week bills and $16bn in 20y bonds.
Mood: Equity outflows continued alongside steady demand for core government bonds, pushing iFlow Mood deeper into negative territory at -0.225, near the weakest level since August 2025.
FX: Flows shifted toward G10 inflows, while EMEA and APAC currencies remained biased to selling and LatAm flows remained mixed. DKK, SGD and JPY saw the largest outflows, against inflows into EUR, NZD and AUD.
FI: Flows were mixed across regions, except for broad-based selling in EMEA led by Turkish government bonds. Japanese government bonds also saw sizable outflows, while Eurozone and Colombian government bonds, U.K. gilts and U.S. Treasurys attracted demand.
Equities: Japanese and U.S. equities led G10 outflows. In EM, aggressive selling in South Korea persisted, while Chinese, Singapore and Thai equities attracted strong buying. Within DM sectors, energy, consumer staples and financials saw the strongest inflows, while information technology remained under selling pressure.
“The cyclone derives its power from a calm center. So does a person.” – Norman Vincent Peale
“The stillness in art characterizes prayer, and the eye of the storm.” – Saul Bellow
Euro area annual inflation accelerated to 3.0% in April from 2.6% in March, while EU inflation rose to 3.2%, reflecting broad-based price pressures across the region. The increase was driven mainly by services and energy, with energy inflation surging to 10.8% after turning positive in March, contributing nearly one percentage point to headline inflation. Services inflation remained elevated at 3.0%, while food inflation was stable at 2.4%. Core inflation measures excluding energy and food remained more contained around 2.1-2.2%. Among member states, Romania, Bulgaria and Croatia recorded the highest inflation rates, while Sweden and Denmark remained the lowest. Inflation increased in most EU countries compared with March, highlighting renewed upward price momentum across the bloc. Euro Stoxx 50 +0.4% to 5875, EURUSD -0.121% to 1.1591, BBG AGG Euro Government High Grade EUR +2.5bp to 3.429%.
German producer prices rose by 1.7% y/y in April, accelerating to the strongest annual increase since May 2023, while prices climbed 1.2% m/m. The rise was driven mainly by higher intermediate goods and energy prices, particularly mineral oil products, as ongoing conflict in Iran and the broader Middle East pushed fuel costs sharply higher. Petroleum products, fuels and raw materials recorded substantial increases, while electricity and natural gas prices remained lower than a year earlier. Capital and durable consumer goods also became more expensive, whereas consumer goods prices declined, led by falling food prices such as butter and pork. Excluding energy, producer prices still increased by 1.6% annually, indicating broader pipeline inflation pressures beyond the energy sector. DAX -0.12% to 24370, EURUSD -0.241% to 1.1594, 10y Bund -1.9bp to 3.174%.
U.K. CPI inflation slowed to 2.8% in the 12 months to April from 3.3% in March, while CPIH eased to 3.0% from 3.4%, indicating a broad moderation in price pressures. Monthly inflation also softened, with CPI rising 0.7% compared with a 1.2% increase in the same month last year. The largest downward contribution came from housing and household services, while higher motor fuel prices provided some offset within transport. Core inflation measures also decelerated substantially, with core CPI falling to 2.5% and core CPIH to 2.8%. Services inflation slowed sharply, while goods inflation edged higher, suggesting that domestic price pressures are easing even as some goods-related costs remain firm. FTSE 100 -0.39% to 10291, GBPUSD -0.142% to 1.3388, 10y gilt -6bp to 5.069%.
U.K. producer price pressures accelerated further in April, with input prices rising by 7.7% y/y and factory gate output prices by 4.0%, both up sharply from March. On a m/m basis, input prices rose 2.4% while output prices increased by 1.4%. The renewed acceleration was driven primarily by energy-related costs, with crude oil providing the largest upward contribution to input price inflation and refined petroleum products leading output price increases. Import prices also strengthened significantly, rising 8.0% y/y compared with 4.1% in March, highlighting increasing external cost pressures. Overall, the data point to intensifying pipeline inflation pressures, largely linked to higher global energy prices and fuel-related costs.
U.K. private rental inflation edged higher in April, with average rents rising 3.5% y/y to £1,381, up slightly from March. Rental growth remained strongest in Wales and the North East of England, while London continued to record the weakest increase. In contrast, U.K. house price growth stalled, with average prices unchanged from a year earlier at £268,000 in March 2026, slowing sharply from 1.7% growth in February. The deceleration reflected weaker monthly price dynamics following a strong rise in the same period last year ahead of stamp duty changes in England and Northern Ireland. By region, house prices edged lower in England but continued to rise in Wales and Scotland, highlighting ongoing divergence across the U.K. housing market.
Poland’s consumer sentiment improved in May 2026, with both current and forward-looking confidence indicators strengthening from the previous month. The current consumer confidence indicator rose to -11.3, supported mainly by more optimistic assessments of the country’s economic situation and households’ future financial conditions. Consumers also reported improved views on current household finances and the future economy, although perceptions regarding the current ability to make major purchases weakened slightly. The leading consumer confidence indicator, which measures expected consumption trends over the coming months, improved to -8.5, driven by stronger expectations for household finances, the economy, unemployment and savings capacity. Compared with a year earlier, both indicators also showed modest improvement, suggesting a gradual strengthening in household sentiment. WIG +0.32% to 132146, EURPLN +0.062% to 4.2542, 10y PGB -4.9bp to 5.992%.
Hungary’s average gross monthly earnings reached HUF 779,800 in March, up 9.2% y/y, while net earnings increased by 11.3% and real earnings grew 9.3% amid relatively low inflation. The stronger growth in net wages reflected increased family tax allowances and broader income tax exemptions for mothers. Regular gross earnings, excluding bonuses, rose 9.0% y/y, with particularly strong gains in the public sector due to scheduled wage increases and special defense-related payments. Median gross and net earnings also rose solidly, by 10.7% and 13.2%, respectively. By sector, financial services and information technology recorded the highest wage levels, while accommodation and food services remained the lowest paid sectors. Budapest SI -0.05% to 131704, EURHUF -0.136% to 361.39, 10y HGB -8bp to 5.59%.
Türkiye’s overseas producer price index rose 35.1% y/y in April, accelerating further from previous months, while prices increased by 4.2% m/m. The y/y increase was driven primarily by energy prices, which surged more than 125% from a year earlier, alongside strong gains in mining and manufacturing. Durable and non-durable consumer goods, intermediate goods and capital goods all recorded substantial y/y increases, indicating broad-based external price pressures. On a m/m basis, manufacturing prices rose 4.3%, while energy prices jumped nearly 15%, led by coke and refined petroleum products and chemical goods. Overall, the data point to intensifying export price pressures, largely linked to higher global energy and industrial input costs. BI 100 -0.24% to 13995, USDTRY -0.05% to 45.5976, 10y TGB +5bp to 35.7%.
Türkiye’s house price index rose 26.6% y/y and 1.8% m/m in April, although in real terms house prices were down 4.3% after adjusting for inflation. Price growth remained strongest in eastern regions such as Erzurum and surrounding provinces, while coastal regions including Aydin, Denizli and Mugla recorded the weakest y/y increases. Among major cities, Ankara continued to outperform with y/y growth of 29.9%, compared with 26.2% in Istanbul and 26.7% in Izmir. Meanwhile, the new tenant rent index increased by 31.7% y/y and 1.7% m/m, though real rent growth turned slightly negative. Rental inflation remained strongest in Ankara and Istanbul, highlighting continued pressure in urban housing markets despite broader disinflation in real property values.
South Africa’s CPI inflation accelerated to 4.0% y/y in April from 3.1% in March, while consumer prices rose 1.1% m/m. The increase was driven mainly by housing and utilities, transport, and insurance and financial services. Transport prices rallied sharply, largely reflecting a strong rise in fuel costs, which increased by 18.2% m/m and 11.4% y/y. Goods inflation accelerated substantially to 3.4% from 1.8%, while services inflation also strengthened to 4.6%. Food inflation remained moderate overall, although meat prices rose strongly, partly offset by declining fruit and vegetable prices. Administered prices continued to rise rapidly, particularly electricity and fuel-related components, contributing to broader inflationary pressures. JSE TOP 40 +0.5% to 106421, USDZAR -0.361% to 16.6446, 10y SAGB -4.3bp to 9.051%.
Data from the Japan Securities Dealers Association (JSDA) showed that foreign investors offloaded a net ¥81.3bn of super-long (>10y) JGBs in April, in the first net selling since December 2024. That said, demand from life/non-life insurers picked up strongly at ¥327.2bn, and trust banks net bought ¥792bn in April. The government appears fully aware of demand softness, as Prime Minister Sanae Takaichi highlighted that the government was expecting to put together an extra budget without “issuing a large amount of government bonds,” as the country may run a surplus by June or thereafter. A new package is expected to offset the impact from the Iran conflict. Nikkei -1.23% to 59804, USDJPY +0.038% to 159.03, 10y JGB -1.1bp to 2.781%.
New Zealand’s Q2 Household Expectations Survey shows rising household annual CPI inflation expectations across all horizons: one-year-ahead mean inflation rose to 5.6% (from 5.2%), with the two-years-ahead measure at 4.9% (from 3.4%) and five-years-ahead at 4.0% (from 3.3%). The one-year-ahead house price inflation expectation decreased to 1.5% (from 1.8%). Expected earnings growth increased to 7.6% (from 4.8%). The average chance of not making a rent payment rose to 21.0% (from 14.8%), while the chance of not making a mortgage payment fell to 14.1% (from 17.2%). The probability of finding a new job improved to 38.7% (from 36.8%). NZX 50 -1.64% to 12761, NZDUSD -0.154% to 0.5836, 10y NZGB +6.2bp to 4.802%.
South Korea’s auto exports fell 5.5% y/y to $6.17bn in April, impacted by a 38.7% plunge in shipments to the Middle East because of the U.S.-Iran conflict. There were rises in exports bound for North America (+2.4%), Latin America (+23.7%) and Oceania (+20.1%), but declines to the EU (-13.1%) and Asia (-31.7%). Eco-friendly vehicle exports surged 13.5% to $2.52bn, driven by electric (+139.7%) and hybrid (+135.8%) cars. Domestic vehicle sales rose 0.7% to 152,000 units, while production fell 6.1% to 362,000 units due to supply chain disruptions, expected to ease from June. KOSPI -0.86% to 7209, USDKRW +0.299% to 1506.7, 10y KTB -4.2bp to 4.205%.
Samsung Electronics’ union in South Korea has announced it will proceed with an 18-day strike starting May 21, 2026, after management rejected a government-mediated proposal on performance-based bonuses. The strike involves nearly 48,000 workers. The South Korean government is concerned about the potential negative impact on the export-driven economy, as semiconductor exports represent about 35% of the country’s total exports. Global companies dependent on South Korea’s semiconductor supply chain have also expressed worries over possible disruptions. The BoK forecasts that the Samsung Electronics’ labor strike could trim South Korea’s 2026 GDP by 0.5 percentage points in a worst-case scenario.
Taiwan’s export orders, measured in USD, reached $87.5bn in April, down 4.0% m/m but surging 48.1% y/y. Cumulative orders in January to April jumped 49.5% from a year earlier. The strong y/y showing was driven primarily by sustained demand linked to AI, high-performance computing and cloud services, which boosted orders for information and communication products and electronics. Orders from the U.S. and ASEAN recorded particularly strong increases, while Chinese and European demand also expanded. Traditional industries such as machinery, plastics and metals also benefited from semiconductor capacity expansion and higher commodity prices. Authorities noted that geopolitical risks and trade barriers remain headwinds, but continued investment in AI infrastructure is expected to support export order growth in the coming months. TAIEX -0.39% to 40021, USDTWD +0.016% to 31.645, 10y TGB +1.1bp to 1.635%.
Taiwan’s current account surplus, measured in USD, widened sharply to $62.5bn in Q1, increasing by $32.8bn from a year earlier. This was supported primarily by a stronger goods trade surplus driven by sustained demand for emerging technology applications. The goods surplus rose to $58.0bn as exports expanded significantly, while the services deficit widened modestly due to higher travel spending abroad. Primary income surplus also increased, reflecting stronger income receipts from residents’ overseas direct investments. On the financial account, net assets increased by $64.9bn, led by portfolio investment outflows as residents increased their holdings of foreign bonds and equities, while foreign investors reduced their holdings of Taiwanese equities. Direct investment outflows and higher overseas deposits also contributed to the overall capital outflow position.
Malaysia’s Q1 manufacturing industry capacity utilization rose to 82.8% (Q4 2025: 83.3%; Q1 2025: 81.8%). All sub-sectors exceeded 80%, led by electrical and electronics products at 83.1% (+2.6 points), but some sectors declined due to supply factors. Capacity utilization in export-oriented industries increased to 82.0% (+1.4 points y/y), with substantial rises for computer, electronics and optical products, and wearing apparel. Domestic-oriented industries edged up to 84.5%, led by pharmaceuticals (87.0%). External trade was robust in April, with total trade rising 28.6% y/y to MYR 336.7bn, driven by exports (+36.9% to MYR 182.7bn) and imports (+20.0% to MYR 154.0bn). This resulted in a trade surplus of MYR 28.8bn (March: MYR 24.5bn; April 2025: MYR 5.3bn). Export growth was led by re-exports (+113.5% y/y to MYR 71.6bn) and domestic exports (+11.2% to MYR 111.1bn). Imports increased mainly due to consumption goods (+5.6%), while intermediate and capital goods decreased. M/m, exports and imports rose 22.8% and 23.9%, respectively. KLCI -0.39% to 1721, USDMYR +0.131% to 3.9713, 10y MGB +1bp to 3.605%.