Market Movers: Expiration
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoff Yu
Time to Read: 5 minutes
JPY can’t catch a bid as data deteriorates
Source: BNY
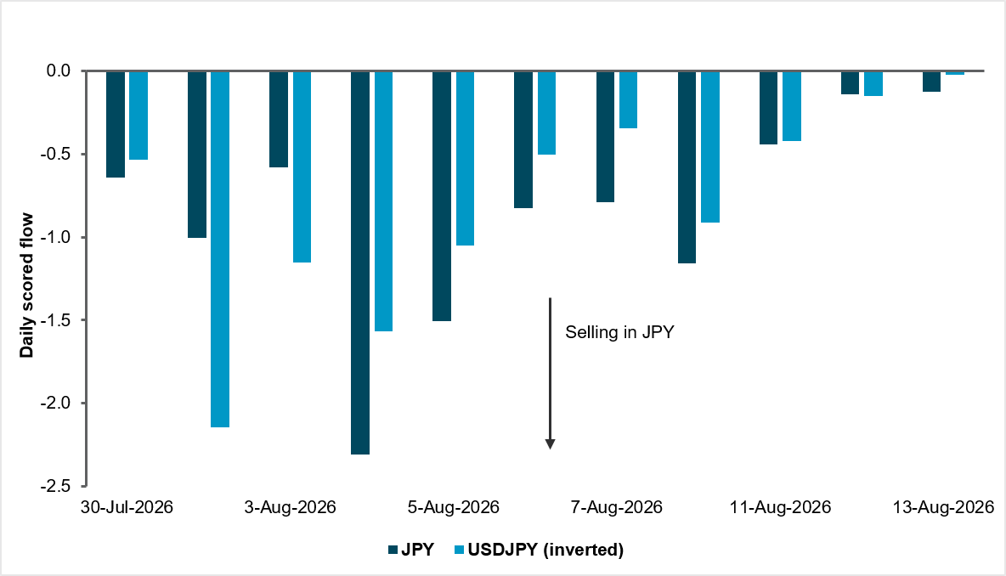
Japan’s Q2 preliminary GDP data has again cast doubt on the Bank of Japan’s (BOJ) ability to hike rates, even though markets see such a move as necessary for the Japanese authorities to have any chance of success in the JPY’s defense. As of mid-last week, USDJPY had already recovered by around 2.8%; it continues to trade above 159.00 as of Monday morning. The overnight weakness in the JGB market also hints at significant concerns over policy credibility. Based on our flow figures, the market remains skeptical of success and has used the opportunity to sell JPY, both on an aggregate basis and against the USD.
Based on flows since July 30 – the first day of the intervention – JPY’s daily average sales magnitude is 0.86, which is above the 0.79 daily average for USDJPY on a standalone basis. This indicates that JPY is even finding additional funding interest as the risk environment is supporting the carry trade on the margins. However, the past week has seen selling gradually ease, especially as our data highlight the JPY is now underheld again for the first time since end-2024, albeit current holdings levels are extremely noisy.
Deal expiration: The U.S.–Iran memorandum of understanding (MOU) reaches the end of its 60-day window today without a final agreement. Tehran had already dismissed the deadline as largely meaningless, limiting its practical significance. Markets remain resilient and oil is lower, but the expiration removes another formal anchor for de-escalation. With the summer holiday period nearing its end, there is a growing sense that geopolitical risk could return quickly.
Intervention expiration: Japan is another reminder that temporary fixes have a shelf life. The 10-year JGB yield is approaching 3%, while the yen has largely surrendered the gains generated by coordinated intervention. Weak data overnight have only added to skepticism, reinforcing concerns around the underlying policy mix. Markets are again testing whether Tokyo has a credible fiscal and monetary strategy behind the intervention signal. Without follow-through, the current government’s policy credibility risks acquiring its own expiration date.
Growth clock: China’s latest data disappointed almost across the board. Retail sales and industrial production undershot expectations, investment contracted more sharply and housing weakness persisted, while unemployment increased. Beijing has pledged greater policy “intensity” in response, but markets remain skeptical. Time is running short for stronger support to translate into activity if this year’s growth objective is to remain credible.
Ahead today: The calendar is light, with Canadian inflation the main North American release. Markets will otherwise look for sentiment to stabilize ahead of the FOMC minutes and a run of household- and consumer-focused U.S. earnings.
Bottom line: Risk appetite remains robust, but several policy and geopolitical buffers are approaching their expiration dates. As summer winds down, markets may soon face a harder test of whether resilience can survive once temporary supports fade.
The U.S.–Iran 60-day deadline for reaching a broader agreement expired without a final deal, leaving the June memorandum effectively overtaken by renewed conflict and unresolved disputes over the Strait of Hormuz and Iran’s nuclear program. The framework, signed by Presidents Trump and Pezeshkian, was intended to halt hostilities, reopen key shipping routes and create a path toward a permanent settlement. However, both sides accused the other of violations, and fighting resumed. Trump has since declared the agreement over and shifted toward increasing economic pressure, while Tehran has not committed to restarting negotiations. Although direct U.S.–Iran strikes are currently paused, regional violence involving Iran-backed groups continues, leaving the risk of renewed escalation and prolonged disruption to Gulf trade firmly in place. Brent -0.136% to 88.4, WTI -0.632% to 81.88, Omani Crude +1.642% to 87.32, Dubai Crude +1.027% to 85.308.
Japan's 10y bond yield touched 2.93% on Monday, its highest level since 1996, as investors priced in stronger inflation pressure from a weaker yen and higher oil prices, and bet that the BOJ may raise rates in September. The move brought yields close to the psychologically important 3% level, which market participants see as a key test of fiscal credibility because it is embedded in the government’s budget assumptions. Sentiment was also shaped by slower-than-expected growth, with Q2 real GDP rising 1.1% annualized, well below forecasts. The yen remains under pressure despite recent intervention, while the Nikkei was broadly flat. Nikkei +0.74% to 69,220, USDJPY +0.265% to 158.9, 10y JGB +3.5bp to 2.927%.
Pressure on a U.S.-brokered ceasefire is intensifying as Lebanon saw its deadliest day of fighting in months when Israeli strikes killed 11 people, including a senior Hezbollah commander. The developments are also complicating already-stalled U.S.–Iran talks. The Israel Defense Forces said it killed Abu Hassan Alaa in southern Lebanon, while Prime Minister Benjamin Netanyahu said the strikes were retaliation for a Hezbollah attack that wounded Israeli soldiers. The escalation comes as Washington prepares fresh economic measures against Iran, and Trump signals that he wants to hit Iran’s economy hard even if the conflict drags on. Rising tensions around the Strait of Hormuz also keep oil markets on edge, with Brent still vulnerable to further disruption. MSCI EM 0.34% to 1,701, MSCI EM Currency Index +0.156% to 1902.8, BBG AGG EM Local Currency Government Bond Index 0bp to 3.87%.
India’s bond market sold off after the Reserve Bank of India (RBI) unexpectedly brought forward the closure of its special dollar deposit window for overseas residents, reducing the amount of rupee liquidity investors had expected to enter the system. The facility, which has already attracted more than $50bn, will now close at the end of August rather than a month later. 5y yields rose as much as 9bp to 6.44%, while the 10y yield climbed 4bp to 6.80%. The earlier closure could also slow further reserve accumulation and limit rupee appreciation after reserves rose above $700bn. The move suggests the RBI is becoming more sensitive to the future liability and forward-premium costs associated with sustaining the scheme. SENSEX -0.45% to 77,660, USDINR -0.177% to 95.6037, 10y INGB +4.2bp to 6.8%.
U.S. August Empire Manufacturing is forecast to ease to 10.5 vs. 15.6.
U.S. August NAHB Housing Market Index is forecast to ease to 33.0 vs. 34.0.
Canada July CPI is forecast at 0.4% m/m, 2.9% y/y vs. -0.4% m/m, 2.8% y/y in June. CPI ex Food and Energy is forecast to hold at 1.8% y/y vs. 1.8% y/y. CPI Core Median is forecast to hold at 1.9% y/y vs. 1.9% y/y. CPI Core Trim is forecast to hold at 1.8% y/y vs. 1.8% y/y.
U.S. Treasury sells $92bn in 13-week bills and $79bn in 26-week bills.
Mood: iFlow Mood widened slightly as incremental demand for core sovereign bonds outpaced global equities.
FX: Flows were mixed and generally light. JPY, USD and CNY outflows persisted, while MXN inflows flattened and BRL outflows eased.
FI: U.K. gilts attracted strong inflows; cross-border demand for long-dated U.S. Treasurys was also notable. Polish, Chinese, Indonesian and Peruvian government bonds were sold.
Equities: Demand was broad for EMEA and APAC equities, led by Poland and Taiwan. G10 flows were mixed, with U.S. buying against selling in Australia and Japan, while LatAm equities saw outflows.
“Coming events cast their shadows before.” – Thomas Campbell
“So foul a sky clears not without a storm.” – William Shakespeare, King John
U.K. housing market signals weakened in August, with Rightmove saying the average newly listed asking price fell 2.0% m/m (£7,360) to £364,999, the biggest August decline since 2018 and larger than the 10-year average seasonal drop. Prices were also down 1.0% y/y, the sharpest annual fall since December 2023. Rightmove cut its 2026 forecast from a 2% rise to a range of 0% to -2%, citing a 12-year high in homes for sale, softer seller pricing and uncertainty around mortgage rates and the Autumn Budget. The market is increasingly regional: asking prices rose 1.9% y/y in the North West of England but fell 3.1% in London. Separate Hamptons data for July showed rental growth accelerating, with average newly-let rents up 1.9% y/y to £1,401, the fastest pace in 19 months. FTSE 100 +0.27% to 10,780, GBPUSD +0.244% to 1.3571, 10y gilt -2.6bp to 5.011%.
Sweden’s money market inflation expectations in August edged higher at shorter horizons, with one-year CPI expectations rising to 2.0% from 1.8% and two-year expectations to 2.2% from 2.1%, while five-year expectations remained anchored at 2.0%. CPIF expectations showed a similar pattern, increasing to 2.0% at one year and 2.1% at two years, while the five-year measure eased to 2.0% from 2.1%. Policy rate expectations were unchanged at 1.8% over three months but rose to 2.0% at 12 months and 2.2% at 24 months. GDP expectations were steady at 2.3% for year one, while longer-term growth expectations softened slightly. Respondents also expect gradual SEK appreciation against both the euro and dollar. OMX +0.04% to 3,276, EURSEK -0.118% to 11.0089, 10y SGB +0.8bp to 3.031%.
Czech Republic producer prices for July showed mixed inflationary pressures across the economy. Industrial producer prices rose 0.3% m/m and 1.6% y/y, driven by higher costs in coke and refined petroleum products, basic metals, paper products and electricity, while food and chemicals were weaker. Construction work prices increased 0.2% on the month and 4.5% from a year earlier, with materials and products used in construction up 6.9% y/y. Service producer prices in the business sphere fell 1.8% m/m but still rose 2.8% y/y, while agricultural producer prices dropped 1.3% on the month and 13.0% y/y. Prague SE -0.32% to 2,781, EURCZK -0.013% to 24.219, 10y CZGB +1.7bp to 4.877%.
China’s economy maintained steady momentum in the first seven months of 2026, with growth led by high-tech and equipment manufacturing. Industrial value added rose 5.3% y/y, while July industrial output increased 4.5% y/y (0.11% m/m). Services expanded 4.7% y/y, and July services production rose 4.3% y/y. Consumption remained positive but modest, with total retail sales of goods and services up 2.6% y/y; July retail sales of consumer goods increased 0.6% y/y (0.06% m/m). Fixed asset investment weakened, falling 6.7% y/y, dragged by infrastructure, manufacturing, and particularly real estate. High-tech industries still expanded 5.0% y/y, and intellectual property product investment rose 9.1% y/y. NBS commented that the foundation for “steady and upward economic growth” still needs consolidation and will “step up counter-cyclical adjustments” and boost domestic demand and improve supply “with greater intensity.” CSI 300 +1.61% to 4,741, USDCNY +0.054% to 6.7389, 10y CGB -0.4bp to 1.68%.
Japan’s preliminary Q2 real GDP grew 0.3% q/q annualized (Q1: 0.5%), while nominal GDP rose 1.2% q/q annualized (Q1: 0.7%). Real growth was driven by net exports, which contributed 0.5ppt, offsetting a -0.2ppt drag from domestic demand. On the demand side, private consumption was flat at 0.0% q/q, after 0.5% in Q1. Private residential investment fell 0.5% q/q, and private non-residential investment dropped 1.2% q/q. Government consumption increased 1.6% q/q, while public fixed investment slipped 0.1% q/q. Exports rose 0.5% q/q, but imports fell 1.5% q/q, supporting growth. The GDP deflator rose 0.9% y/y, down from 3.2% in Q1. Fiscal-year 2025 real GDP was 0.9%, nominal GDP 4.3%. Nikkei +0.74% to 69,220, USDJPY +0.265% to 158.9, 10y JGB +3.5bp to 2.927%.
Japan’s June 2026 Indices of Tertiary Industry Activity slipped 0.2% m/m after a 0.8% m/m gain in May. Broad-ranging personal services fell 1.9% m/m, while broad-ranging business services increased 1.4% m/m. The monthly decline was driven mainly by retail trade, down 5.1% m/m, living and amusement-related services, down 3.3%, and electricity, gas, heat supply and water, down 4.6%. Smaller drags came from real estate, wholesale trade, and medical, health care and welfare. Offsetting the weakness, finance and insurance jumped 4.7% m/m, transport and postal activities rose 4.4%, and information and communications edged up 0.1%.
New Zealand’s BusinessNZ Performance of Services Index for July remained just in expansionary territory at 50.6, easing from 50.9 in June. This marked a second straight month above the 50.0 breakeven level, after May’s 48.1. BusinessNZ said the sector is recovering only modestly, with firms still cautious on hiring and broader sentiment subdued. Three of five sub-indexes were above 50, led by new orders at 52.6 and activity/sales at 50.5, while employment remained the weak spot at 48.5, unchanged in broad terms and below 50 for a 32nd straight month. BNZ and BusinessNZ said firms are still cautious on hiring, and the recovery is likely to remain modest until consumer confidence improves. They also said the combined PSI/PMI points to annual GDP growth of about 2%. NZX 50 -0.96% to 13,722, NZDUSD +0.493% to 0.5922, 10y NZGB +3.6bp to 4.716%.
New Zealand’s petrol and diesel prices fell for a third straight month in July 2026. Petrol dropped 5.7% m/m and diesel fell 12.1% m/m, both lower than in March but still above February levels. On an annual basis, petrol rose 15.1% y/y and diesel increased 34.9% y/y. Airfares also moved higher in July: domestic fares rose 20.7% m/m and international fares increased 10.9% m/m. Annual food inflation eased to 1.9% y/y from 2.5% y/y in June, the smallest rise since December 2024, led by restaurant meals and ready-to-eat food, while fruit and vegetable prices fell. Monthly food prices edged up 0.1% m/m, with fruit and vegetables up and meat, poultry and fish down.
Singapore’s external trade data for July 2026 showed a strong but mixed performance. Non-oil domestic exports (NODX) rose 24.2% y/y, rebounding from 20.8% in June, led by a 112.0% surge in electronics on robust AI-related demand, especially disk media products, ICs and PCs, while non-electronics fell 2.3%. NODX to the U.S., China and Taiwan expanded, but shipments to the EU contracted. Non-oil re-exports (NORX) increased 51.3% y/y, down from 60.3% in June, with both electronics and non-electronics contributing. Total merchandise trade climbed 38.6% y/y, after 49.3% in June, as exports rose 40.6% and imports 36.3%. Overall, trade momentum remained strong, but growth moderated from the previous month. STI +0.03% to 5,745, USDSGD +0.212% to 1.2758, 10y SGB -0.2bp to 2.27%.
Thailand’s NESDC said Q2 2026 GDP grew 1.9% y/y, easing from 2.8% in Q1, and contracted 0.2% q/q sa (Q1 2026: 0.6% q/q). Growth slowed as private consumption, government spending and exports moderated, while public investment fell. Private investment was a standout, rising 13.4% y/y, the fastest pace in 54 quarters. Exports of goods rose 17.6% y/y, led by electronics, machinery and agricultural products, but imports surged 42.3%, widening the trade deficit. On the production side, manufacturing, agriculture, tourism-related services, transport, trade and construction all lost momentum. The current account swung to a deficit for the first time in eight quarters, while unemployment ticked up. NESDC kept 2026 GDP growth at 2.0–2.5%, citing stronger investment, consumption and exports, but warned on trade frictions, Middle East risks, and weather-related agricultural vulnerabilities. 2026 CPI inflation is revised lower to 1.5–2.0% compared with 2.0–3.0% projected in May, and a substantial downward revision of the trade balance and current account balance to a negative level. Trade balance is at -$3.7bn (vs. $11.2bn in May), with the current account at $-7.4bn, -1.2% of GDP ($6.2bn +1.0% of GDP). SET +1.23% to 1,629, USDTHB +0.556% to 32.97, 10y TGN +0.2bp to 2.037%.
Malaysia’s CPI rose 1.8% y/y in July 2026, easing from 1.9% in June. The increase was driven mainly by Transport, which slowed to 1.4% from 2.8% previously. Other notable upward pressures came from Information & Communication, which accelerated to 3.4% from 2.4%, while Food & Beverages and Housing, Water, Electricity, Gas & Other Fuels both rose 1.8% (from 1.4%). On a monthly basis, headline inflation was flat m/m in July, after 0.0% in June. Food & Beverages edged up 0.3% m/m, while Transport fell 1.1% m/m and Personal Care, Social Protection & Miscellaneous Goods & Services declined 0.5% m/m. The January–July 2026 average inflation rate was 1.8%, up from 1.4% a year earlier. KLCI +0.07% to 1,729, USDMYR +0.413% to 4.0695, 10y MGB -0.7bp to 3.736%.