Market Movers: Events
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 9 minutes
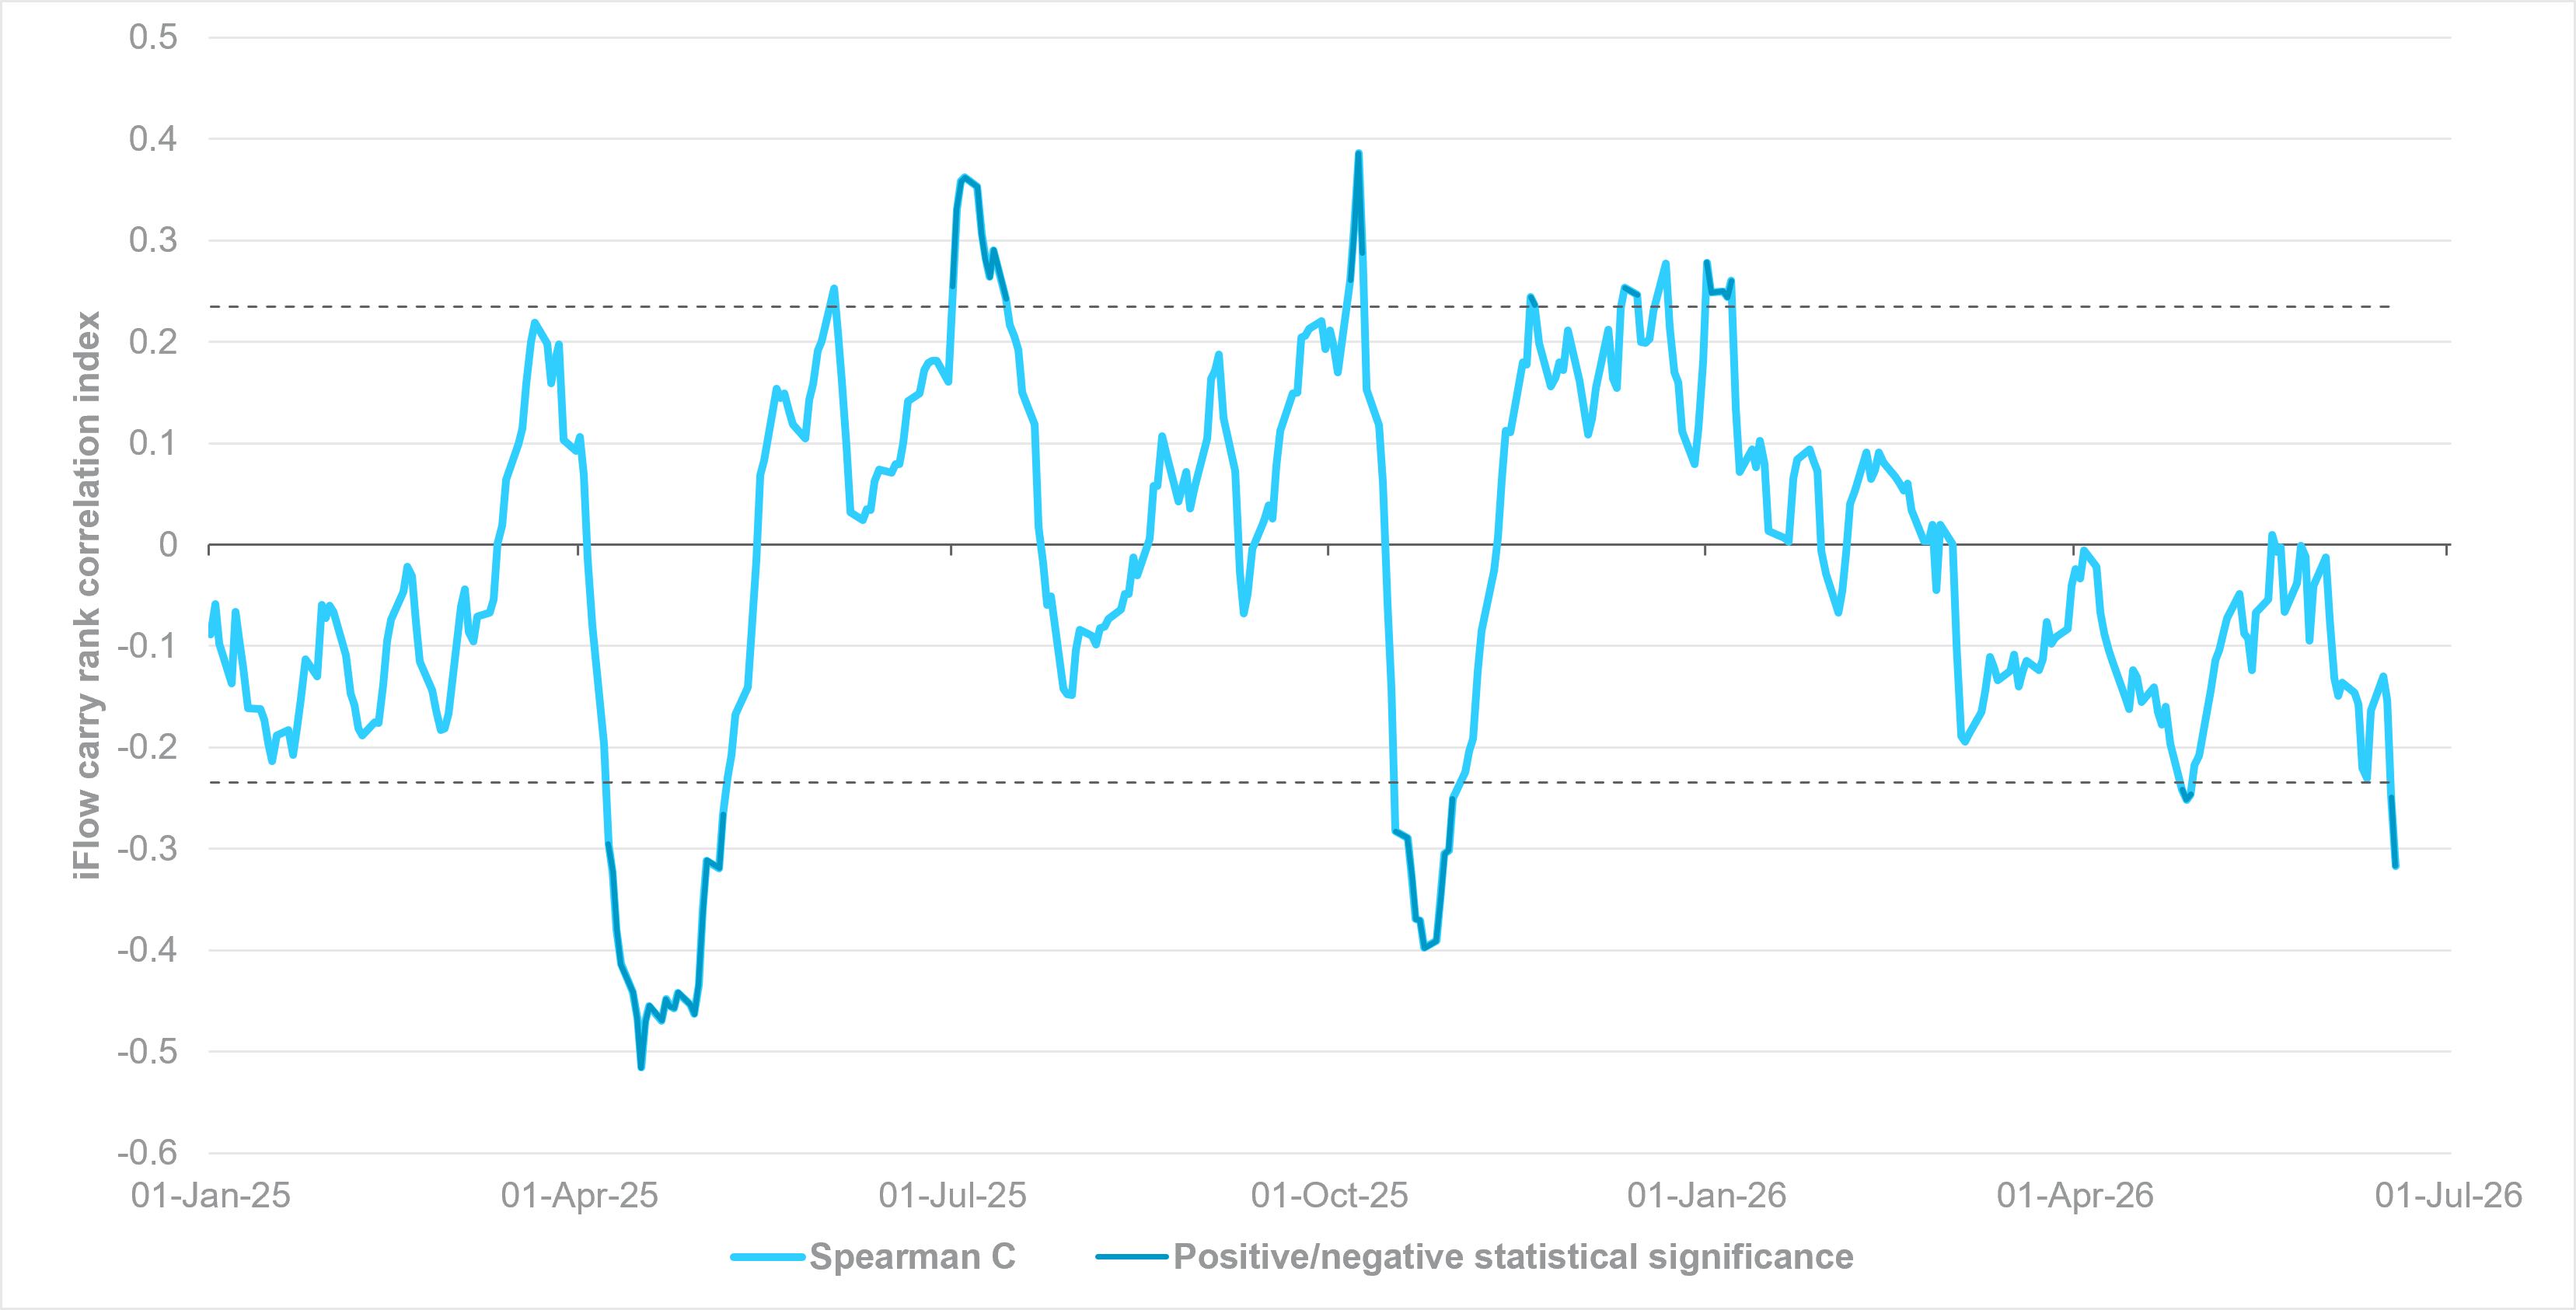
iFlow Carry moves into negative significance, hinting at recovery in yield appetite
Source: BNY
Our iFlow Carry index has moved into negative statistical significance for the first time in 2026. The index is the daily Spearman rank correlation between 32 currency flow indicators and their corresponding local bond yields. This index gauges the strength of flows’ alignment with their corresponding bond yields. Current flows indicate that currency flow performance is increasingly negatively aligned with those currencies’ bond yields, i.e. carry trades are unwinding. While this may continue in the near term, we see the alignment as a contrarian signal, indicating that carry trades stand to recover strongly as liquidation runs its course. Recovery in iFlow Carry is also consistent with the improved risk environment given the ceasefire in the Gulf and a limited hawkish pivot from the Fed for now.
To identify the most attractive currencies in line for mean reversion, we look for those with the biggest potential moves in rankings if carry interest turns strongly positive. BRL longs offer a strong risk-reward profile according to this criterion. The currency is only moderately overheld but has been, by far, the most-sold carry currency over the past month. All other high-yielding currencies also remain net long, but flow scores are more subdued. CHF is a similar story case for funders: over the past month it has been well-bought, while its holdings score is now comfortably positive. This is a very rare state of affairs for a currency with zero rates, and – unlike JPY – it is not considered excessively undervalued.
Markets have started the week in robust manner. Despite the difficult start, U.S.-Iran talks appear to be making progress, and the reaction in oil markets clearly points to expectations that the ceasefire will be durable. This should mean that the hard-earned improvement in inflation expectations can start to become embedded in the next round of monetary policy decisions. Already, we are seeing a shift toward improved risk appetite outside of equity markets, and we are particularly attentive to potential gains in FX carry trades as real yields recover. The bigger question is how to reconcile U.S. exceptionalism with improved risk-reward elsewhere, and that is where idiosyncratic factors will matter greatly.
The U.K. will have its seventh prime minister in ten years, as Sir Keir Starmer has bowed to the inevitable and resigned from office. The expectation is that new Member of Parliament Andy Burnham will be chosen as Labour leader – and therefore prime minister – unopposed, avoiding a potentially divisive leadership election. Higher fiscal impulse has been factored into gilt yields, but the key trigger for an improvement in GBP will be a return in cross-border interest, which has been lacking since H2 2025. We doubt that cross-border flows will pick up until a new chancellor is appointed.
The Colombian election result, if confirmed, could mirror what we saw in Hungary in April. A fundamental “regime shift” in fiscal policy will lead to re-rating in a country’s assets, generating significant outperformance irrespective of the starting point for holdings. Colombia is already in a strong position, with the central bank having hiked rates early on to affirm fiscal credibility. The prospect of even stronger relations with the U.S. and ongoing improvements in terms of trade from the current external environment looks set to generate significant inflows into the country, complementing favorable market positioning for a recovery in carry trades.
The dollar should also be considered a carry name, despite its traditional status as a funder in a strong carry environment. There are some outliers, for example in Latin America and EMEA, where real rates are sufficient to drive exchange rates with the dollar on the other side. However, we note that there are central banks in Europe and APAC which are clearly anchoring rates, based on domestic inflation expectations and policy necessity. SEK, CHF, TWD and CNY all fit the bill in this respect, and dollar rate differentials are strong enough to offset valuation adjustments required by balance of payments strength among exporters. However, these currencies are also often under the U.S. Treasury’s scrutiny, and a fine line is required to balance clear external interest versus legal mandates targeting excessive imbalances.
Bottom line: Events matter, and the changes over the last 72 hours affecting the world and individual countries have reassured markets that a risk-positive base case remains intact on a macro basis. However, after the “change” events, the hard task of execution lies ahead. From ensuring the ceasefire holds for the world, to new finance ministers meeting market requirements for high real yields and fiscal credibility, the trade-offs can be painful and lead to execution error, with a whiplash in inflation and inflation expectations often the end-result. On this basis alone, we expect no major changes in current policy stances, but the hope is for data to gradually reflect new realities and for asset allocation to start exploring opportunities that have opened up after several months of turbulence.
Sir Keir Starmer has resigned as Prime Minister of the United Kingdom, acknowledging that he has lost the confidence of the Parliamentary Labour Party. He has asked the party’s National Executive Committee to open nominations for a new leader on July 9 and ensure that a new prime minister will be in place by September, when parliament returns from its summer recess. His departure means the U.K. will have its seventh prime minister since the Brexit vote. As Starmer’s exit has largely been the market’s base case since the May local elections, the current impact on U.K. assets is likely to be muted. Investors do expect a shift toward higher fiscal impulse, but if the growth strategy is credible and better-executed, we don’t expect much chance of a repeat of the events of 2022. FTSE 100 -0.07% to 10357, GBPUSD -0.288% to 1.3194, 10y gilt -0.7bp to 4.835%.
The U.S. and Iran have concluded the first round of their high-level talks in Switzerland, with mediators Qatar and Pakistan saying both sides have agreed to a roadmap toward a final deal within 60 days. Technical discussions will continue this week in Bürgenstock. The talks have focused on a ceasefire mechanism for Lebanon, safe passage through the Strait of Hormuz and implementation details of last week’s memorandum of understanding. Iran said it had secured waivers for oil and petrochemical exports, release of some frozen assets and a reconstruction plan, while the U.S. said discussions also addressed deconfliction mechanisms for the strait. Despite tense rhetoric and President Trump’s threats of renewed strikes, mediators described progress, while shipping through the strait showed signs of disruption. Brent -1.118% to 79.67, WTI -0.119% to 75.76, Omani crude -2.847% to 72.01, Dubai crude -0.012% to 81.286.
Bank of Italy Governor Fabio Panetta has argued that recent crises have demonstrated the importance of coordinated fiscal and monetary policy in supporting the euro area. Reflecting on the sovereign debt crisis, he noted that the burden of stabilization fell almost entirely on monetary policy, with the ECB’s “whatever it takes” commitment proving decisive. In contrast, during the pandemic and subsequent energy shock, common fiscal initiatives such as Next Generation EU complemented monetary policy and strengthened the euro area’s resilience. Looking ahead, Panetta stressed that Europe must complete the institutional architecture of monetary union by deepening capital markets, creating a common European safe asset and advancing a digital euro to safeguard monetary sovereignty in an increasingly fragmented geopolitical environment. While he did not comment on the near-term policy outlook, his remarks underscored the need for stronger fiscal integration and structural reforms to reduce the burden on monetary policy during future shocks. Euro Stoxx 50 +0.07% to 6297, EURUSD -0.21% to 1.1447, BBG AGG Euro Government High Grade EUR 0bp to 3.265%.
Bank of Spain Governor José Luis Escrivá has argued that Europe needs a simpler and more predictable banking regulatory framework, warning that excessive layers of rules and supervisory guidance are creating unnecessary complexity and reducing efficiency. On monetary policy and financial stability, he focused primarily on the housing market, saying any decision to impose macroprudential limits on mortgage lending would require extreme caution given the potential impact on younger and lower-income households. Escrivá stressed that such measures are highly intrusive and should only be used if financial stability risks clearly justified intervention. He said the Bank of Spain would soon publish a white paper assessing the housing market and the potential consequences of mortgage restrictions, emphasizing that any future measures would need to be carefully calibrated and data-driven. His comments suggest no immediate inclination to activate tighter macroprudential restrictions despite international pressure to do so.
China’s Commerce Ministry has placed MP Materials and USA Rare Earth on an export control list, barring Chinese firms from supplying them with dual-use goods and restricting transfers of dual-use items of Chinese origin from other countries. The move also covered eight other U.S. companies, including drone, robotics and aerospace firms. Beijing said the decision targets entities linked to commercial and military uses, intensifying the pressure on U.S. efforts to build alternative rare earth supply chains. MP Materials, backed in part by the Pentagon, and USA Rare Earth have expanded capacity over the past year after China tightened controls on key rare earths and magnets last April. The announcement comes shortly after G7 members agreed to reduce dependence on any single non-bloc supplier of rare earths, underscoring growing strategic tensions around critical minerals and advanced manufacturing. CSI 300 +2.39% to 5060, USDCNY +0.145% to 6.778, 10y CGB -0.4bp to 1.73%.
China has left its benchmark lending rates unchanged, with the one-year and five-year loan prime rates held steady at 3% and 3.5%, respectively, for the 13th straight month. The result was in line with market expectations. The decision suggests policymakers are in no hurry to ease monetary policy despite signs of economic divergence and softer credit growth. Recent data point to a two-speed economy, in which factory activity has been supported by resilient exports while domestic demand remains weak amid a prolonged property downturn. The central bank has also described slower loan growth as part of a broader economic restructuring, while new bank lending in May came in below expectations after the prior month’s contraction.
Polish retail sales rose 3.0% y/y in constant prices in May but were down 1.7% m/m, while January-May sales were up 2.9% y/y. In the enterprise sector, average employment in May was 0.1% lower than in April and 0.9% below a year earlier, while average monthly gross earnings dropped 3.8% m/m but increased by 5.8% y/y in nominal terms. Industrial producer prices were 2.4% higher than in May 2025 and broadly unchanged from April. June business survey indicators pointed to stabilization or deterioration in most sectors, with financial and insurance activities most positive and manufacturing most negative. WIG -0.13% to 138668, EURPLN +0.087% to 4.2643, 10y PGB -1.1bp to 5.438%.
Colombia’s presidential runoff has produced a razor-thin, still-unofficial outcome, with hard-right candidate Abelardo de la Espriella claiming victory. Preliminary results showed him ahead with 49.66% of votes, just above leftist rival Iván Cepeda’s 48.70%. Outgoing President Gustavo Petro said neither candidate can yet be declared president, stressing that the final count and judicial review will determine the result. De la Espriella, a pro-Trump conservative who campaigned on law and order and tougher action against cartels and guerrillas, said he would govern for all Colombians and described his administration as democratic and committed to institutional order. Cepeda has not conceded and said his camp would recognize the official result only after the count has been completed and checks finished. The vote underscores Colombia’s deep political polarization and ongoing concerns over security and foreign interference. COLCAP +4.02% to 2503, USDCOP +0.587% to 3460.89, 10y CGB -11.5bp to 11.768%.c
Mood: iFlow Mood improved sharply but remained in negative territory at -0.204. Global equities continued to face outflow pressure, while demand for core government bonds collapsed toward neutral levels.
FX: Flows were highly volatile on FOMC day, with significant dispersion across the iFlow universe. Within the G10, large outflows from CAD, JPY and NOK were offset by strong inflows into AUD, NZD and SEK, followed by USD. EMEA flows were similarly volatile, with strong buying of CZK, ILS and TRY against large-scale selling of HUF, PLN and ZAR. Elsewhere, MXN and THB attracted strong inflows, while KRW and PEN saw heavy outflows.
FI: Demand remained firm for Eurozone government bonds, followed by Hungary, Peru, China and India. In particular, there was little meaningful selling across the iFlow universe, including a sharp moderation in Indonesian government bond outflows.
Equities: Flows were mixed. Substantial outflows were recorded in the Philippines, Sweden, Türkiye and South Africa, while inflows were concentrated in Hong Kong, Mexican and U.S. equities.
Canada May CPI is forecast at 0.8% m/m, 3.0% y/y vs. 0.4% m/m, 2.8% y/y in April.
CPI ex food and energy is forecast to hold at 1.5% y/y vs. 1.5% y/y.
CPI core median is forecast to hold at 2.1% y/y vs. 2.1% y/y and CPI core trim is forecast to hold at 2.0% y/y vs. 2.0% y/y.
Central bank speakers:
The Fed’s Christopher Waller delivers the opening remarks at the Fifth Conference on the International Roles of the U.S. Dollar.
ECB President Christine Lagarde gives an introductory statement to the European Parliament’s Committee on Economic and Monetary Affairs in Brussels.
ECB President Christine Lagarde participates in a panel on the international role of the euro.
U.S. Treasury sells $89bn in 13-week bills and $77bn in 26-week bills.
“Colombia was always a Caribbean country open to the world.” – Gabriel García Márquez
“Events, dear boy, events.” – Harold Macmillan