Market Movers: Euphoria
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 5 minutes
Intervention effectiveness can benefit from softer JPY positioning
Source: BNY
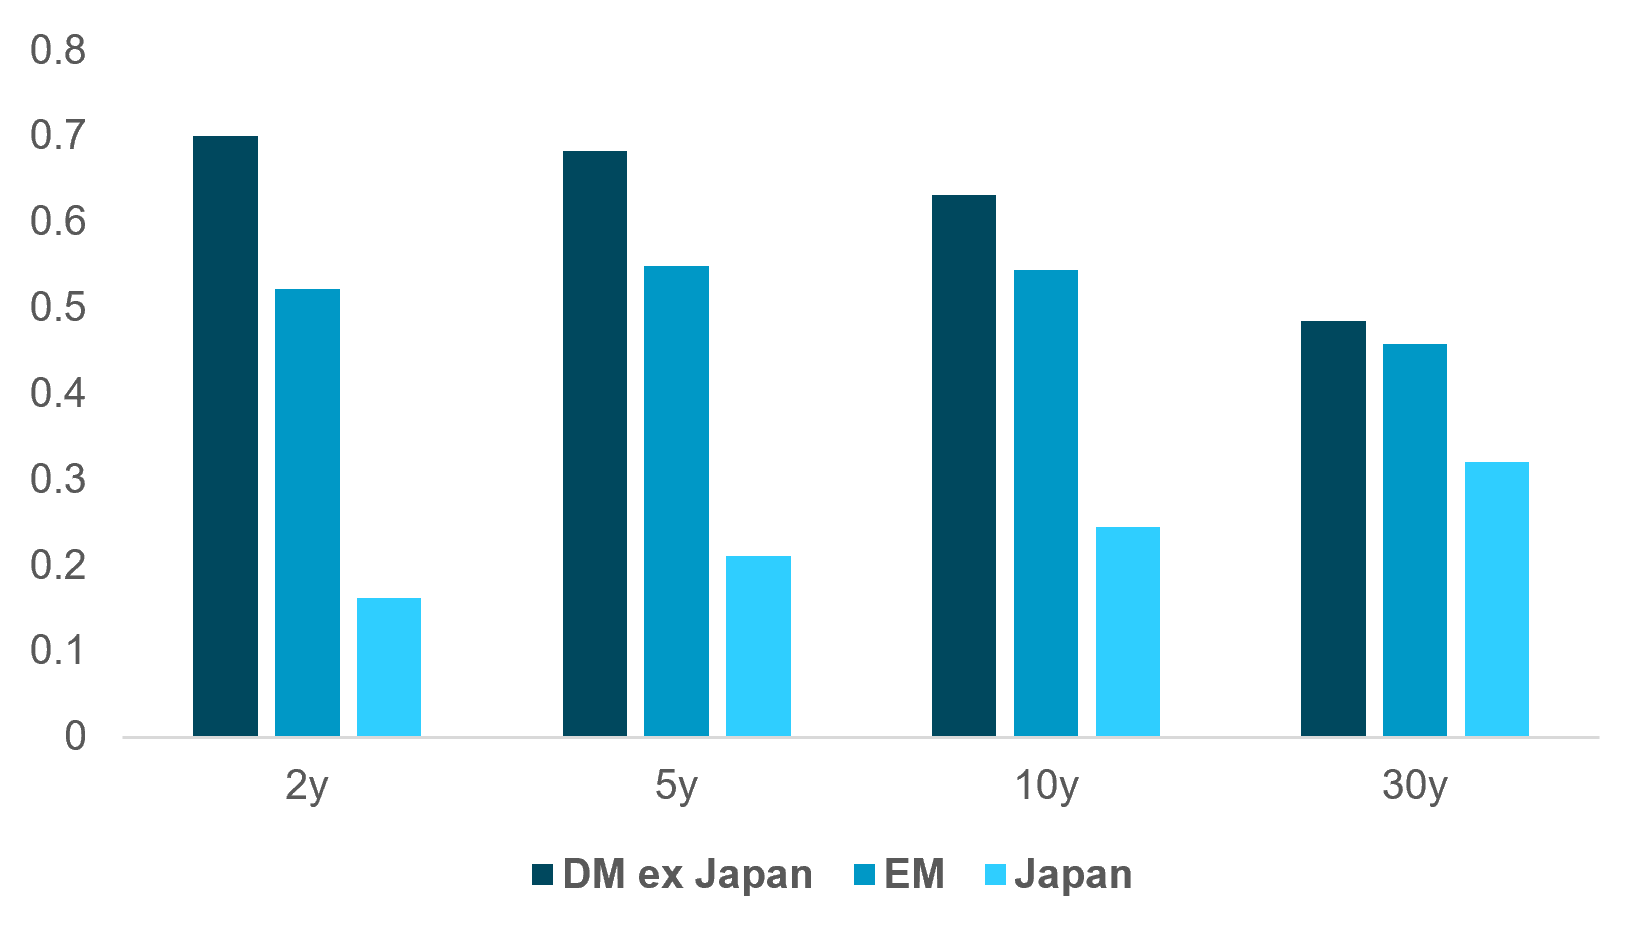
JPY entered the BOJ decision and reported intervention with weak flow momentum and lighter positioning. Forward and swap demand had deteriorated, USDJPY remained better bid, spot purchases were inconsistent and cash flows had turned sharply negative. Volumes were also soft, limiting conviction across the market. Holdings told the same story. Investors were still net long JPY and net short USDJPY, but those positions had been cut by roughly half since the June IMM period, while aggregate JPY holdings briefly moved into underheld territory. The market wasn’t aggressively short the currency, but confidence had weakened enough to prevent investors from rebuilding exposure.
That creates a more asymmetric setup for the yen. Fiscal concerns, the latest budget and the lack of policy assertiveness had undermined confidence, leaving attractive valuations without strong sponsorship. Reported intervention and a firmer BOJ message could change that quickly. Stronger intervention would show that the authorities are prepared to resist further depreciation, while clearer policy guidance would reduce the credibility discount embedded in JPY assets. With holdings lighter, flow momentum weak and volumes subdued, a shift in expectations could produce a disproportionate response. Investors could add to existing JPY longs and rebuild USDJPY shorts that had been reduced during the recent loss of confidence. Better policy credibility could therefore turn a lightly sponsored currency into a sharp mean-reversion rally.
Record rebound: Euphoria has displaced anxiety, at least for now. South Korea’s KOSPI surged almost 18% in its largest one-day gain on record, led by SK Hynix and Samsung Electronics. The move followed a powerful U.S. technology session and renewed confidence in AI spending after robust hyperscaler earnings. But South Korea still ended July sharply lower. That underlines how much of the rebound reflects positioning, leverage and forced re-entry rather than a fundamental reset.
Relief, not resolution: Strong earnings have answered part of the AI monetization question, but not the broader one. Capital expenditure remains enormous, valuations are elevated and South Korea’s extreme two-way volatility shows how crowded the trade has become. Unease also lingers after the Fed. Equities welcomed the less hawkish outcome, but elevated long-dated Treasury yields show that concerns over inflation and policy credibility haven’t disappeared.
Japan’s credibility test: Intervention appears to have resumed overnight. This is unsurprising as the BOJ sounded hawkish but couldn’t make the message stick. Much of yesterday’s intervention-driven yen appreciation has already been surrendered. Verbal resolve and periodic intervention are still struggling to offset rate differentials, fiscal concerns and imported inflation. The yen therefore remains a live test of policy credibility.
Careful what you wish for: A less hawkish Fed supports equities, but looser financial conditions aren’t a free lunch while inflation remains unresolved. French inflation surprised to the upside despite a hawkish ECB, underscoring the narrow margin facing central banks trying to contain prices amid continued supply volatility.
Bottom line: A light data and earnings calendar gives markets time to digest the rally but offers little fresh support. Euphoria can fade quickly after such an extreme move. The risk of a sharp comedown is rising ahead of next week’s crowded earnings schedule and the key U.S. payrolls report.
South Korean equities staged a record rebound as the KOSPI surged 17.91% to 6,595.45, reclaiming the 6,500 level after three days of heavy selling. The rally was led by chip stocks, with SK Hynix and Samsung Electronics jumping sharply as stronger U.S. cloud results eased fears that AI data center spending wasn’t translating into revenue. Foreign and institutional investors drove the move, while retail investors sold into strength, suggesting positioning rather than pure conviction also shaped the rebound. The rally erased recent semiconductor losses and lifted hardware, component and power equipment names linked to AI infrastructure. However, the scale of the move also underlines how unstable the trade remains, with deleveraging, ETF regulation and sell-into-rally risk likely to keep volatility elevated. KOSPI +17.91% to 6,595, USDKRW +0.499% to 1430.1, 10y KTB +5.6bp to 4.311%.
The BOJ kept policy rates unchanged on Friday, but Governor Kazuo Ueda said the central bank could speed up rate hikes if monetary conditions remain too accommodative. He stressed that currency volatility is increasingly affecting inflation, noting that the yen’s weakness over the past year has raised upside price risks as underlying inflation nears the 2% target. Ueda warned that delaying action could force a rapid tightening later, which would unsettle markets and hurt growth. He also said the BOJ will closely assess AI-related demand, exchange rate moves, and their impact on prices from the next meeting onward, while emphasizing the need for stable policy guidance and market trust. Nikkei +4.03% to 64,362, USDJPY -0.54% to 158.67, 10y JGB -0.8bp to 2.805%.
U.S. Treasury Secretary Scott Bessent said on Thursday that the Japanese yen looks very undervalued and should strengthen further, while stressing that excessive volatility in the currency isn’t healthy. Speaking in a FOX Business interview, he argued that the yen has overshot its equilibrium price and said he isn’t worried about the currency’s recent appreciation against the dollar. His remarks came after the yen jumped to the upper 157 range in New York trading, its strongest level since mid-May, prompting speculation that Japanese authorities may have intervened. Bessent also said the Japanese economy is doing well and that market fundamentals should eventually support the currency. Our flows indicate sustained JPY longs but momentum is weak.
The U.S. and Iran resumed missile exchanges, dashing hopes for a quick end to the five-month conflict. Jordan said it intercepted Iranian missiles for a second straight day, while Kuwait reported a deadly strike in the north. Drone attacks also set fires on ships at Egypt’s Damietta port, with investigators saying the cause was a drone. The fighting has widened regional risks, with attacks reported across Jordan, Kuwait, Saudi Arabia and Iraq. Diplomacy remains focused on restoring security in the Strait of Hormuz, where traffic has fallen sharply and energy shipments have been severely disrupted. There are rising concerns over depleted U.S. weapons stockpiles and the conflict’s impact on global energy markets. Brent -1.157% to 88, WTI -1.245% to 82.55, Omani Crude -3.657% to 78.25, Dubai Crude +0.463% to 76.646.
U.S. Q2 Employment Cost Index is forecast to ease to 0.8% q/q vs. 0.9% q/q.
U.S. July MNI Chicago PMI is forecast at 56 vs. 56.7 prior.
U.S. July final UMich Sentiment is forecast at 54.0 vs. 54.4 prior. UMich Current Conditions is forecast at 54.7 vs. 54.9 prior. UMich Expectations is forecast at 53.8 vs. 54.0 prior.
U.S. July final UMich 1y Inflation Expectations is forecast at 4.3% vs. 4.2% prior. 5–10y Inflation Expectations is forecast unchanged at 3.3%.
Canada May GDP is forecast at 0.2% m/m, 1.4% y/y vs. 0.5% m/m, 1.1% y/y in April.
Mood: iFlow Mood continued its risk-off posture driven by fixed income inflows.
FX: FX Flows were pronounced in the G10 and LatAm space, with inflows into PEN, GBP and CHF and outflows from NZD, COP and CAD.
FI: Fixed income flows favored G10 at the expense of EMs. European, Danish and Japanese sovereign bonds saw inflows while South African, New Zealand and Czech bonds were sold.
Equities: Equity flows were mixed, with Colombian and Danish equities seeing inflows, while Canadian stocks along with equities across APAC and EMEA were sold off.
“Bull markets are born on pessimism, grow on skepticism, mature on optimism and die on euphoria.” – Sir John Templeton
“Whole communities suddenly fix their minds upon one object, and go mad in its pursuit.” – Charles Mackay
Euro area annual inflation for July 2026 was estimated at 2.9%, up from 2.8% in June, according to Eurostat, the statistical office of the EU. The flash estimate showed a broadening price pulse, with energy inflation rising to 10.0% from 8.5% and services edging up to 3.3% from 3.2%. Food, alcohol and tobacco slowed to 1.2% from 1.5%, while non-energy industrial goods increased to 0.9% from 0.7%. Monthly HICP inflation was estimated at 0.2%, indicating modest overall price gains in the euro area. Euro Stoxx 50 +1.02% to 6,409, EURUSD -0.044% to 1.1523, BBG AGG Euro Government High Grade EUR +4.4bp to 3.431%.
Germany’s employment data for June 2026 showed a softer labor market, according to the Federal Statistical Office Destatis. The number of employed residents stood at about 45.54mn. Seasonally adjusted employment fell by 23,000 people, or 0.1%, from May, while the unadjusted figure was nearly unchanged. Compared with June 2025, employment declined by 223,000, or 0.5%, extending the downtrend that has been visible since January 2025. On a quarterly basis, employment in Q2 2026 was also 0.1% lower than in Q1. Meanwhile, the seasonally adjusted unemployment rate rose to 3.9% in June, up from 3.8% in May. DAX +0.88% to 25,837, EURUSD -0.044% to 1.1523, 10y Bund -0.3bp to 3.152%.
French inflation for July came in at 2.4% y/y, above expectations and up from 2.0% in June, according to Insee. The surprise increase was driven by stronger services inflation, which rose to 2.3% from 1.9%, and by a sharp acceleration in energy prices to 12.4%. The reading adds to signs of firmer price pressure across major euro area economies and supports the case for another ECB rate hike. It also followed better-than-expected economic output data, reinforcing market expectations for a 25bp increase in September. Further inflation releases before then could still alter that outlook. CAC 40 +0.85% to 8,558, EURUSD -0.044% to 1.1523, 10y OAT -0.5bp to 3.935%.
U.K. annual house price growth slowed to 1.8% in July from 2.2% in June, while prices rose 0.1% m/m to an average of £277,542. Nationwide said market activity and house prices remained soft amid an uncertain economic backdrop, with geopolitical tensions and energy prices adding pressure, though easing consumer inflation and slower wage growth may give policymakers more room. The release also noted that average home residence is about 14 years, with much longer stays among outright owners and shorter stays among private renters, and that most moves in 2024–2025 occurred within the same tenure type. FTSE 100 +0.66% to 10,969, GBPUSD -0.015% to 1.3464, 10y gilt -1.4bp to 4.97%.
Poland’s flash consumer price index inflation for July 2026 came in at 3.0% y/y, while prices rose 0.8% m/m, according to Statistics Poland. The preliminary reading suggests inflation remained above the 2.5% target but stayed close to it, with the annual rate lower than the peaks seen earlier in 2026. Food and non-alcoholic beverages were down 0.4% from a year earlier, while electricity, gas and other fuels rose 4.0%, and fuels and lubricants for personal transport equipment increased 15.8%. The flash estimate is provisional and may still be revised. WIG +0.26% to 147,154, EURPLN +0.172% to 4.3134, 10y PGB -9.3bp to 5.669%.
Japan’s Tokyo area CPI for July 2026 rose more broadly, with the headline index up 2.0% y/y and 0.4% m/m, after 1.7% y/y in June. Core CPI excluding fresh food increased 1.9% y/y and 0.3% m/m, vs. 1.6% y/y previously. Core-core CPI excluding fresh food and energy also rose 2.0% y/y and 0.3% m/m, after 1.9% y/y in June. Price gains were driven mainly by food (4.0% y/y), especially eating out, prepared foods, confectionery, seafood and meat, alongside higher housing rents (1.5% y/y) and transport (3.0% y/y) costs. The downside came from miscellaneous items (-6.5% y/y), notably childcare fees. Energy remained a drag y/y, but the decline in electricity and gas prices narrowed, helping lift the overall index. Nikkei +4.03% to 64,362, USDJPY -0.54% to 158.67, 10y JGB -0.8bp to 2.805%.
Japan’s June 2026 unemployment rate was unchanged at 2.5%. Employment rose to 68.9mn, up 170,000 y/y and extending gains for a fifth straight month. Employee numbers increased to 62.45mn, with regular employees at 37.41mn and non-regular workers at 21.57mn, both higher than a year earlier. The jobless total edged up to 1.78mn, up 20,000 y/y and rising for an 11th month. By reason, layoffs rose, while voluntary quits fell. The employment rate improved to 62.8%, and the 15-64 employment rate rose to 80.7%. The non-labor force population declined to 38.96mn, falling for a 52nd consecutive month.
Japan’s June 2026 industrial was up 1.3% m/m, 4.2% y/y vs. 0.1% m/m, -2.1% y/y in May. Shipments fell 0.4% m/m to 101.1, inventories rose 2.3% m/m to 97.1, and the inventory ratio climbed 2.3% m/m to 104.7. The ministry said gains led by production machinery, electrical machinery, and information and communication electronics equipment, and general-purpose/business machinery, while electronic parts and devices and iron, steel and non-ferrous metals weighed. Shipments were dragged down by motor vehicles, transport equipment ex-auto, and electronic parts and devices. The forecast survey points to further gains, with production expected to rise 1.2% m/m in July and 4.5% m/m in August.
Australia Producer Price Indexes, June quarter 2026: Final demand excluding exports rose 1.3% q/q and 3.6% y/y. The increase was the largest since September quarter 2023 and was driven mainly by higher energy prices, especially crude oil, petrol and diesel, after supply disruptions linked to the Strait of Hormuz closure and broader Middle East tensions. Continued strength in rental demand also supported prices. Key contributors were petroleum refining and fuel manufacturing (+37.5%), property operators (+1.0%) and heavy and civil construction (+2.3%), while accommodation services (-12.3%) offset some of the gain due to weaker winter demand. Among selected PPIs, manufacturing output rose 2.2%, building construction rose 1.4%, and transport, postal and warehousing prices increased, led by road freight transport (+15.5%) on higher fuel costs. ASX +0.62% to 5,890, AUDUSD +0.228% to 0.7043, 10y ACGB -6.8bp to 4.927%.
Australia’s June private sector credit rose 0.8% m/m, above the 0.6% forecast and unchanged from May’s 0.7% pace. On a y/y basis, credit growth accelerated to 8.5% from 8.2% in May. Lending to non-financial businesses remained the strongest segment, rising 1.1% m/m and 10.8% y/y, while housing credit increased 0.6% m/m and 7.5% y/y. Owner-occupier housing eased to 0.5% m/m, while investor housing held at 0.8% m/m and sped up to 10.4% y/y. Other-personal credit also firmed to 0.8% m/m. Broader money aggregates strengthened, with M3 up 0.8% m/m and broad money up 0.9% m/m, suggesting continued underlying credit and liquidity expansion in Australia.
New Zealand’s ANZ-Roy Morgan Consumer Confidence survey for July 2026 rose 8 points to 99.3, though it remains below the neutral 100 mark. The improvement was broad-based: future conditions jumped to 106.5, back above 100 for the first time since February, while current conditions improved to 88.5. Households also felt less negative about their personal finances, and more expect to be better off over the next year. Still, willingness to buy major household items stayed subdued at -7. Inflation expectations for two years ahead were unchanged at 4.6%, while house price expectations eased to 2.6%. NZX 50 -0.46% to 13,699, NZDUSD +0.137% to 0.5887, 10y NZGB -5.9bp to 4.672%.
China’s July 2026 official PMI readings fell into contraction indicating a broad loss of momentum. The manufacturing PMI fell to 49.2 (49.2% in July vs 50.3% in June), slipping back below the 50 line as growth faded after a strong prior base and seasonal slowdown. High-tech manufacturing and equipment manufacturing still expanded, but consumer goods and high-energy industries weakened. New orders (48.5 vs. June: 51.2) and output (49.9 vs. June: 51.4) both eased, while input (53.2) and output (47.8) prices continued to decline. The non-manufacturing business activity index dropped to 49.0 (vs. June: 50.2), with services easing (49.3 vs. June: 50.4) overall, but tourism- and summer-travel-related sectors such as aviation, lodging, and culture and recreation improving. Construction (47 vs. June: 49) slowed further on adverse weather. The composite PMI output index fell to 49.3, showing overall business activity slowed versus June. CSI 300 +0.85% to 4,588, USDCNY -0.083% to 6.7469, 10y CGB -0.5bp to 1.71%.
South Korea’s June 2026 monthly industrial statistics point to broad-based improvement. All industry production rose 2.3% m/m and 4.2% y/y, led by gains in mining and manufacturing, services and construction, while public administration declined. Manufacturing production increased 6.8% m/m and 6.1% y/y, with shipments up 8.9% m/m and inventories up 0.1% m/m. Capacity utilization improved sharply to 74.9%, up 4.0 percentage points m/m. Services output rose 0.7% m/m and 5.3% y/y. On demand, retail sales increased 2.7% m/m and 4.2% y/y. Equipment investment jumped 5.8% m/m and 21.7% y/y, while construction completed rose 4.1% m/m but fell 4.0% y/y. Leading and coincident business indicators also strengthened. The Composite Leading Index, a gauge of the business cycle turning point, climbed 1.2% m/m (from the previous month), with its cyclical component up 0.9 points m/m, 5.7% y/y. Overall, the data suggest both current activity and forward-looking conditions strengthened in June. KOSPI +17.91% to 6,595, USDKRW +0.499% to 1430.1, 10y KTB +5.6bp to 4.311%.