Market Movers: Direction
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoff Yu
Time to Read: 6 minutes
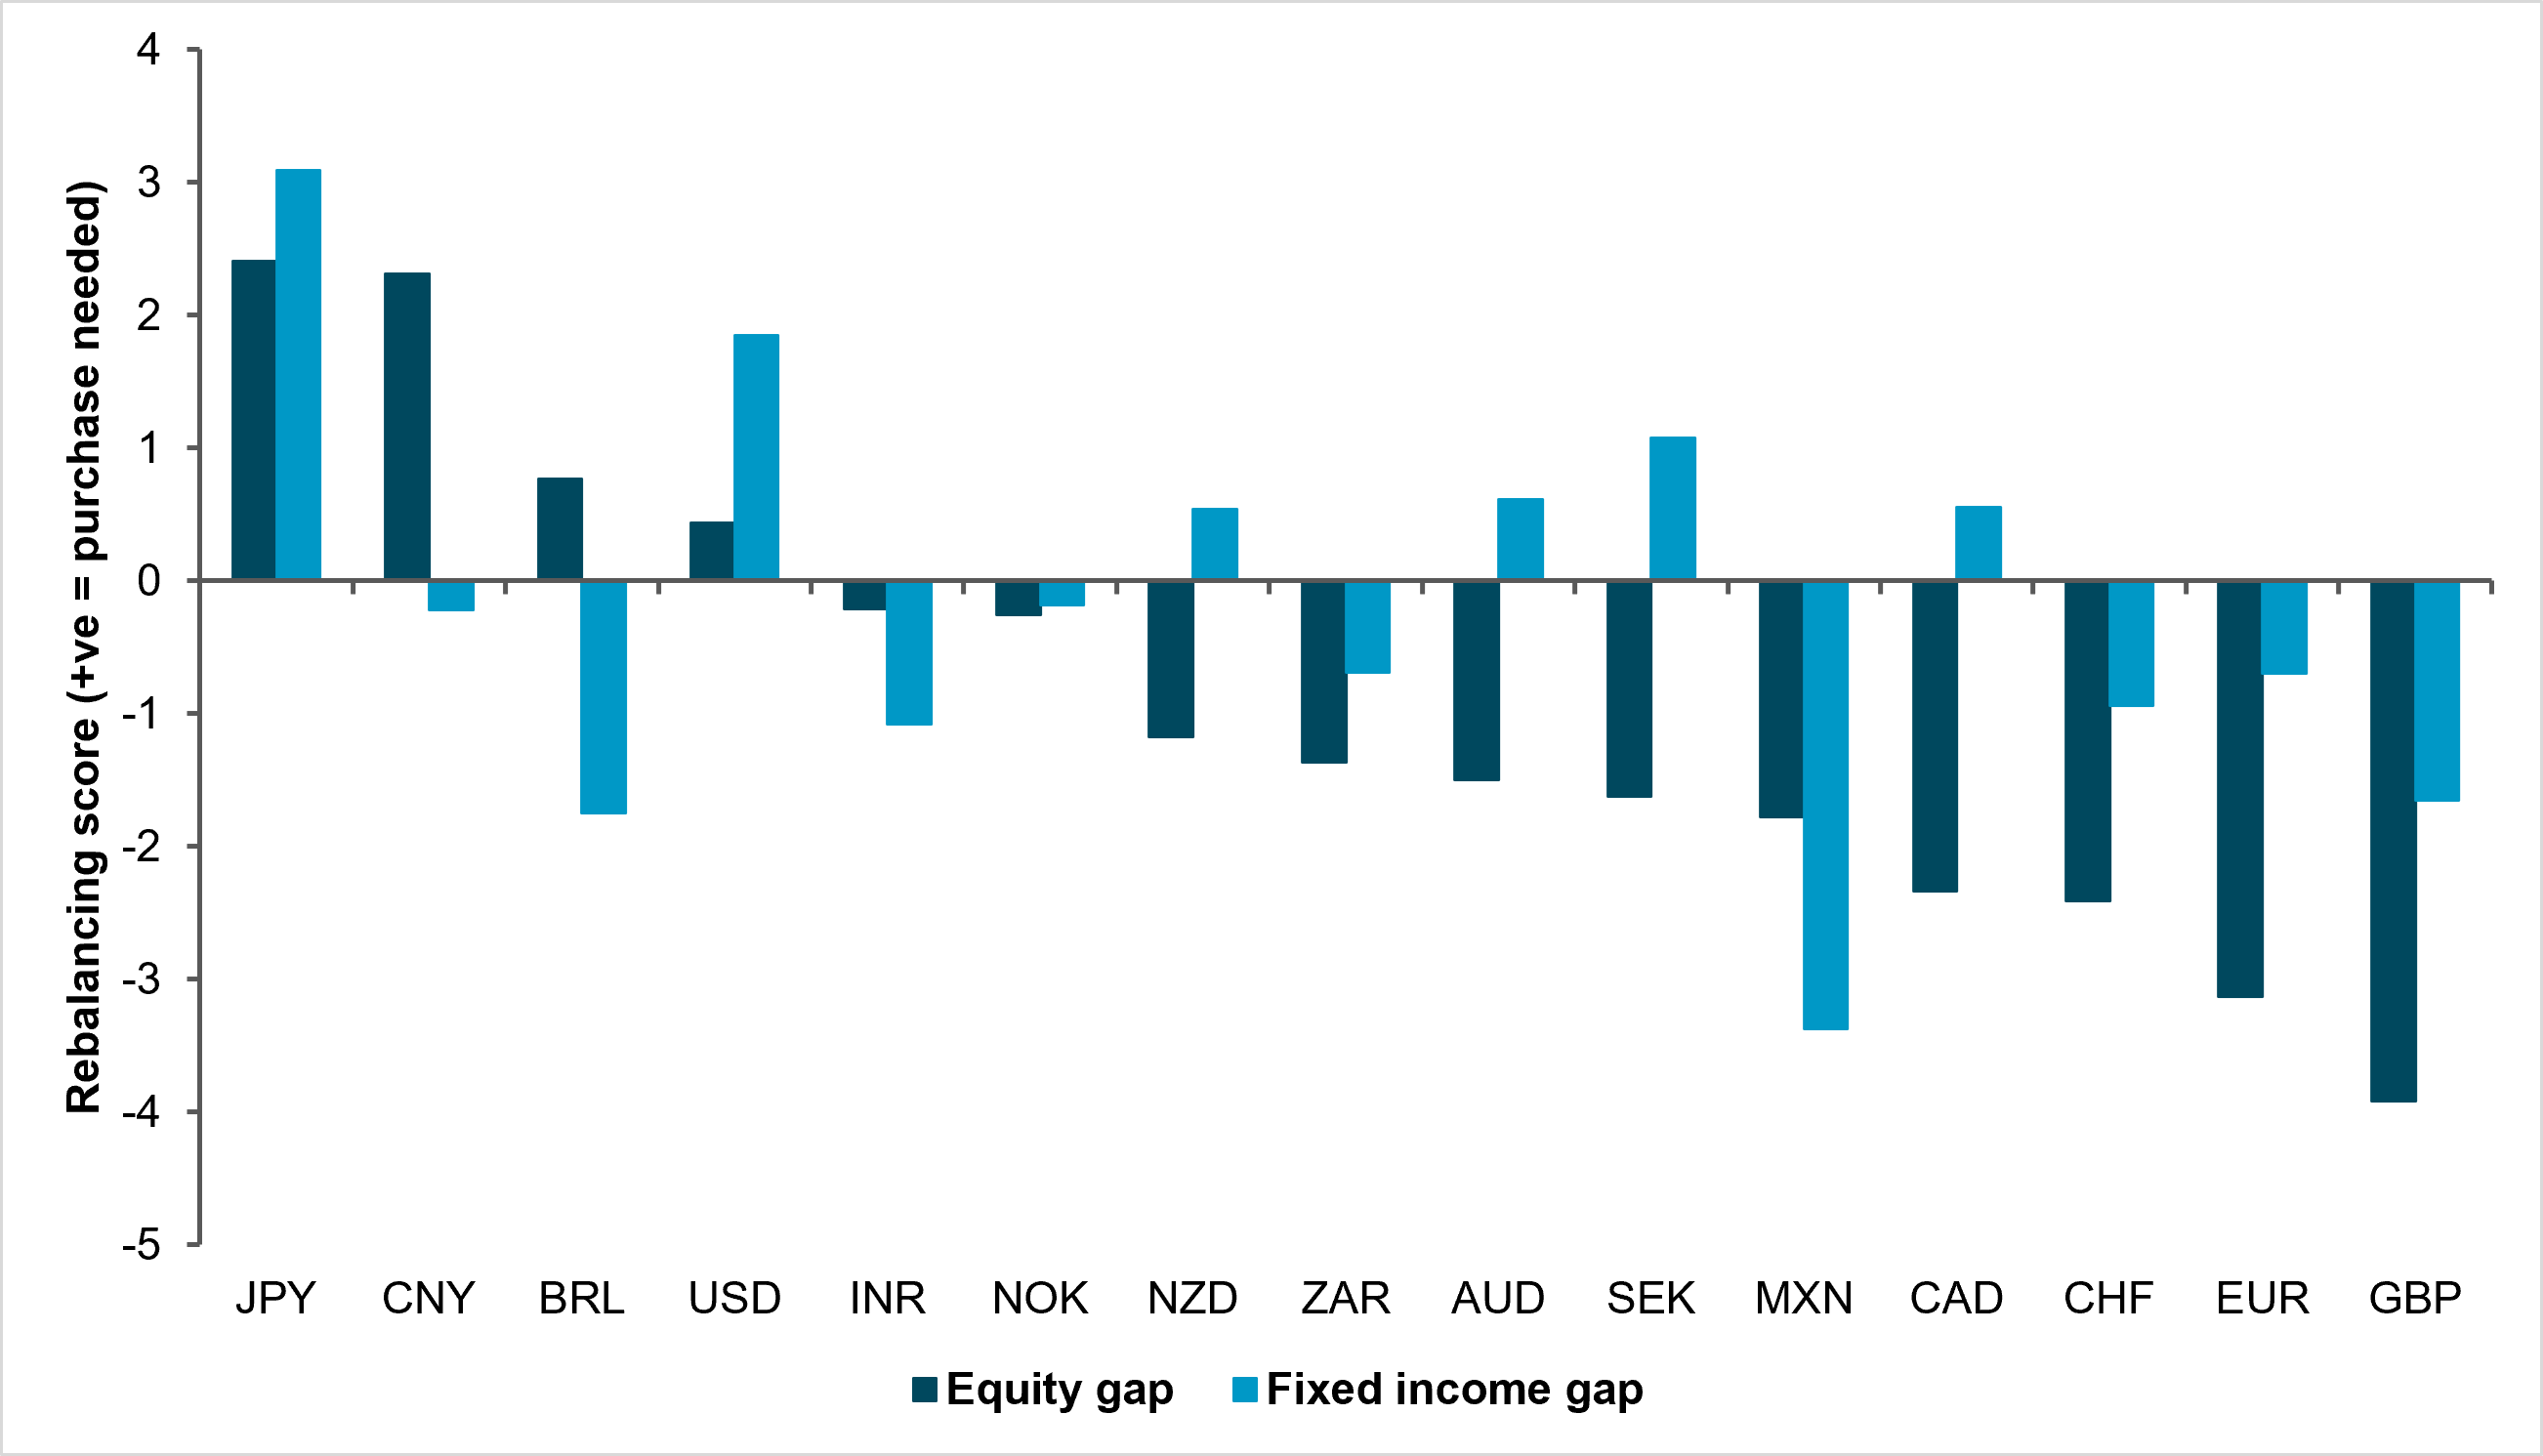
Month-end rebalancing favors JPY and CNY over GBP, EUR, and MXN
Source: BNY
August’s rebalancing dynamics are more selective than thematic. FX flows offered little evidence of a broad carry or dollar trade, with idiosyncratic drivers dominating and central bank divergence likely to remain the key differentiator. MXN stood out as the clearest carry expression, while GBP and EUR benefited from hedging flows and relatively supportive rate profiles. By contrast, JPY and CNY remained weak. The broader implication is that rebalancing should be handled currency by currency rather than through a single macro lens. The clearest signal sits in equities, where strong local-market performance combined with currency appreciation has created meaningful rebalancing pressure in Europe. GBP looks particularly exposed given stretched GBPUSD levels and the associated earnings-translation drag, while EUR faces a similar, if slightly less acute, risk.
Fixed income offers a different message. Emerging market (EM) bonds were the strongest part of the cross-asset picture, helped by a weaker dollar, lower oil prices and attractive real rates, while developed-market bonds largely avoided a worse outcome despite ongoing fiscal concerns. The rebalancing signal is therefore more nuanced than simply fading EM duration. MXN is the clearest candidate for profit-taking, with BRL showing a weaker version of the same signal. Elsewhere, realized FX weakness has offset much of the bond-market gain, particularly in INR, CNY and ZAR. That supports the case for maintaining hedged EM duration exposure rather than reducing it outright.
Policy direction: Markets are looking for direction from Kevin Warsh, but the Fed Chair may deliberately provide very little. Equities and fixed income are calm ahead of his Jackson Hole address, yet Warsh’s retreat from forward guidance means investors may have to infer the reaction function themselves. That carries a cost: prolonged uncertainty could sustain rate volatility and term premia while inflation and fiscal concerns remain unresolved.
Diplomatic direction: The Middle East is offering tentative signs of a better direction, although the economic costs continue to accumulate. Iran says restoring diplomacy with Washington is “not impossible” following Qatari-mediated discussions, even as the U.S. insists formal negotiations are not currently underway. Qatar’s extended force majeure on liquefied natural gas (LNG) supplies meanwhile leaves importers facing a difficult winter and keeps European gas markets vulnerable.
Inflation direction: European inflation is moving higher, strengthening the case for ECB vigilance. French HICP accelerated to 2.7% from 2.4%, while Spanish national CPI rose to 4.3%, slightly above consensus, although harmonized inflation was marginally softer than expected at 4.5%. Both direction and level will be seen as unacceptable to the Governing Council. ECB hawk Isabel Schnabel speaks in Wyoming today, and we expect her to reinforce the need to preempt inflation persistence, despite limited evidence of second-round effects so far.
Ahead today: U.S. data are light, leaving Warsh firmly in control of the session. Final August Michigan sentiment is due, with one-year inflation expectations expected at 4.4%. Central bankers gathering in Jackson Hole can’t appear dismissive of household inflation concerns. Direction matters, but credibility will determine whether markets follow.
Iran’s foreign minister said restoring diplomacy with the U.S. remains possible after talks with Qatar, signaling a modest opening despite Washington’s intensified economic pressure campaign. He said progress depends on the U.S. accepting that coercion will not deliver an agreement and called for greater trust, respect for Iranian rights and adherence to commitments. The comments followed diplomatic visits to Tehran by Qatar, Oman and Pakistan aimed at creating conditions for renewed negotiations. Washington’s public stance remains hard, however, with President Donald Trump unwilling to lift the blockade of Iranian ports simply to restart talks. Iran also indicated that reopening the Strait of Hormuz could form part of a broader deal if unspecified U.S. conditions are met, keeping the shipping route central to any de-escalation. Brent -0.235% to $89.49, WTI -0.228% to $83.34, Omani Crude +2.54% to $91.67, Dubai Crude +0.166% to $88.78.
Qatar extended force majeure on LNG supplies to European and Asian buyers as traffic through the Strait of Hormuz remains heavily constrained, keeping a major source of global gas supply offline. European customers are being warned that cancellations could extend into early November, while Qatari LNG exports remain near a standstill despite improving oil flows through the strait. The key risk for Europe is a prolonged tightening in gas supply ahead of winter, with LNG prices already close to double pre-war levels. Continued disruption would intensify competition with Asian buyers for alternative cargoes, raise import costs and potentially rebuild inflation pressure through energy and industrial channels. Europe therefore remains highly exposed to any failure to reopen Hormuz and restore Qatari LNG flows. HH Natural Gas -0.824% to 2.89, Dutch TTF Natural Gas +2.318% to 69.85.
U.K. Chancellor John Healey said fiscal discipline will be the bedrock of the Labour government’s first budget under Prime Minister Andy Burnham, pledging to remain within existing fiscal rules while deferring decisions on raising defense spending to 3% of GDP until next year's spending review. The stance comes as the government also prepares a nationwide resilience campaign encouraging households to prepare for cyberattacks, extreme weather and other emergencies, although its launch has been delayed to avoid overshadowing the new administration’s early messaging. The broader policy challenge is balancing tighter fiscal constraints with growing defense and resilience demands, as the U.K. responds to higher security risks, hybrid threats and pressure to increase military preparedness without undermining confidence in the public finances. FTSE 100 +0.17% to 10,811, GBPUSD -0.059% to 1.3585, 10y gilt +2.8bp to 5.058%.
ECB Governing Council member Martins Kazaks warned that above-target inflation cannot be allowed to become entrenched and said another rate increase in September is a considerable possibility. He argued that tighter policy may be needed to prevent persistent price pressures from feeding into expectations and broader inflation dynamics, following the ECB’s initial hike in June. The latest national data reinforce the concern around headline inflation: French CPI accelerated to 2.4% y/y in August from 2.1%, while Spanish CPI jumped to 4.3% from 3.6%, largely on stronger energy and fuel prices. However, Spain’s core inflation eased slightly to 2.9%. Kazaks said the September decision will depend on incoming data and the ECB’s updated economic projections. Euro Stoxx 50 +0.76% to 6,473, EURUSD -0.086% to 1.1643, BBG AGG Euro Government High Grade EUR +1.4bp to 3.483%.
Jackson Hole Symposium
U.S. August MNI Chicago PMI is forecast to rise to 57.9 vs. 57.6 prior.
U.S. 2026 preliminary Benchmark Payrolls Revision is forecast at 185k vs. -911k prior.
U.S. August final UMich Sentiment is forecast to hold at 51.0. Current Conditions is forecast at 51.9 vs. 51.8 prior. Expectations is forecast at 51.5 vs. 50.6 prior.
U.S. August final UMich 1-year Inflation Expectations is forecast at 4.4% vs. 4.3% prior. 5–10 year Inflation Expectations is forecast to be unchanged at 3.3%.
U.S. August Kansas City Fed Services Activity, 14.0 prior.
Canada Q2 GDP is forecast to rise to 3.4% q/q annualized vs. -0.1% q/q annualized. Canada June GDP is forecast at 0.2% m/m, 2.0% vs. 0.3%, 1.7% y/y prior. Canada July GDP advance, 0.2% m/m prior.
Central bank speakers: Fed’s Warsh speaks at Jackson Hole Symposium at 10:00 ET. ECB’s Schnabel also speaks at Jackson Hole.
Mood: iFlow Mood was unchanged, with continued demand for both core sovereign bonds and global equities.
FX: LatAm currencies attracted moderate inflows, while APAC and EMEA currencies were broadly sold. G10 flows were mixed, led by buying in GBP and CHF against selling in NZD and SEK.
Fixed income: U.K. gilts, Eurozone government bonds and U.S. Treasurys saw solid demand, while selling was broad across APAC and LatAm, including New Zealand government bonds.
Equities: Equities were broadly sold across APAC, G10 and LatAm, led by Thailand. Peru and Poland were notable exceptions, attracting inflows.
“Clear communication is itself a vital tool for increasing the efficacy and reliability of monetary policy.” – Janet Yellen
“Clear, transparent communication … is critical for the effectiveness of our tools and for our accountability to the public.” – Jerome Powell
Euro area economic sentiment for August rose 1.3 points to 98.4, while the EU indicator increased 1.0 point to 98.2, bringing both closer to their long-term average of 100. Employment expectations also improved, rising to 98.9 in the euro area and 99.0 in the EU. The increase in sentiment was driven by stronger confidence in industry, services and retail trade, while construction and consumer confidence were broadly stable. Among the largest economies, sentiment improved in France, Germany and Italy, but declined in Spain and Poland. Selling price expectations eased in industry and retail, although consumer price expectations increased sharply. Overall economic uncertainty fell for a fourth consecutive month, reinforcing signs of improving confidence. Euro Stoxx 50 +0.76% to 6,473, EURUSD -0.086% to 1.1643, BBG AGG Euro Government High Grade EUR +1.4bp to 3.483%.
Germany’s employment in July was broadly unchanged m/m on a seasonally adjusted basis, with the number of people in work edging down by 13,000 to 45.48mn. Employment fell 0.5% y/y, equivalent to 223,000 fewer people, extending the annual decline that has persisted since January 2025. Unadjusted employment decreased 0.1% from June. Labor market weakness was also visible in unemployment, with 1.84mn people unemployed in July, up 8.8% y/y, pushing the unadjusted unemployment rate to 4.2% from 3.9% a year earlier. On a seasonally adjusted basis, unemployment increased by 11,000 m/m to 1.74mn, while the adjusted unemployment rate remained unchanged at 4.0%. DAX +0.58% to 26,520, EURUSD -0.086% to 1.1643, 10y Bund +1.5bp to 3.268%.
French CPI inflation for August 2026 is provisionally estimated at 2.4% y/y, accelerating from 2.1% in July, while prices are expected to rise 0.7% m/m after 0.6% previously. The increase in annual inflation is mainly driven by faster energy price growth, particularly petroleum products, while food inflation should also edge higher and the decline in manufactured goods prices should moderate. Services inflation is expected to slow slightly, with tobacco inflation unchanged. On the month, manufactured goods prices should rebound seasonally after July sales, while energy and fresh food prices also rise. Harmonized inflation is estimated at 2.7% y/y and 0.8% m/m, up from 2.4% and 0.6% respectively.
Spain’s preliminary CPI inflation for August rose to 4.3% y/y from 3.6% in July, while prices increased 0.7% m/m. The acceleration was driven mainly by fuel and lubricant prices, which rose this year after falling in August 2025, with food and non-alcoholic beverages also contributing as prices declined less than a year earlier. Underlying inflation moved in the opposite direction, with core CPI easing to 2.9% y/y from 3.0%, suggesting headline pressure remains concentrated in more volatile components. Harmonized inflation increased to 4.5% y/y, up 0.6pp from July, while the harmonized core measure stood at 3.2%. On a monthly basis, HICP inflation was 0.6%. IBEX 35 +0.56% to 20,012, EURUSD -0.086% to 1.1643, 10y Bono +1.1bp to 3.712%.
The U.K.’s August 2026 Lloyds’ Business Barometer showed business confidence rose 4 points to 53% in August, the highest since March and above the 12-month average of 47%. The gain was driven by stronger economic optimism, which climbed seven points to 49%, and a higher trading outlook, up two points to 58%. Firms cited stronger customer demand, improving financial conditions, better supply chains and increased investment in capacity and technology. Pricing intentions eased further, with the share of firms expecting to raise prices falling three points to 51%, the third straight monthly decline and the lowest since 2022. Domestic confidence jumped ten points to 44%, while international firms remained more confident at 59%. Services led sector confidence at a 13-month high, with manufacturing also improving. FTSE 100 +0.17% to 10,811, GBPUSD -0.059% to 1.3585, 10y gilt +2.8bp to 5.058%.
Sweden’s GDP in Q2 2026 rose 1.6% q/q and 3.3% y/y, marking a broad-based acceleration in activity after a revised 0.1% contraction in Q1. Growth was led by gross fixed capital formation, which increased 3.5% and contributed 0.9pp to GDP, alongside exports, up 1.0%, and household consumption, up 0.9%. Public consumption increased 0.7%, while inventories subtracted 0.4pp from growth. On the production side, manufacturing output rose 3.0% q/q, services increased 2.0%, and overall business-sector value added climbed 1.8%. Employment rose 0.1% and hours worked increased 0.5%, while business-sector labor productivity gained 1.4%, pointing to a strong rebound in underlying activity. OMX +0.62% to 3,342, EURSEK -0.018% to 11.0875, 10y Swedish GB +2.3bp to 3.05%.
Sweden’s retail sales volume for July fell 0.2% m/m in calendar and seasonally adjusted terms, leaving overall activity broadly unchanged after recent gains. Durable goods sales declined 0.4%, while consumables excluding the state-owned alcohol retailer increased 0.9%. Over the latest three-month period, total retail volumes rose 2.3% compared with the previous three months, with durables up 2.8% and consumables up 1.9%. Annual growth remained strong, with calendar-adjusted retail volumes up 6.2% y/y, led by an 8.6% rise in durable goods and a 5.3% increase in consumables. In non-calendar-adjusted terms, total retail volumes increased 7.1% y/y, while current-price turnover rose 4.6%.
Norway’s registered unemployment rate in August remained unchanged at 2.1% of the labor force on a seasonally adjusted basis, with 62,164 people fully unemployed vs. 62,104 in July. Unadjusted data showed 62,800 fully unemployed, alongside 20,100 partially unemployed, and 11,400 jobseekers participating in labor-market programs, taking total registered jobseekers to 94,400, or 3.1% of the labor force. Labor demand softened slightly, with 30,600 vacancies advertised during the month, down 2% y/y, although demand remained relatively high, particularly in healthcare. Regional unemployment was highest in Oslo at 2.8% and Ostfold at 2.7%, while youth unemployment generally declined or held steady. OSE +0.56% to 2,101, EURNOK -0.128% to 10.8492, 10y NGB -0.8bp to 4.401%.
Czech GDP in Q2 2026 increased 0.4% q/q and 1.9% y/y, confirming continued economic expansion. Growth was supported by household consumption, gross fixed capital formation and external demand, while inventories remained a notable drag. Household consumption rose 0.5% q/q and 2.7% y/y, while fixed investment increased 1.5% q/q and 7.1% y/y, led by dwellings, other structures and transport equipment. Industry expanded 0.9% q/q, with financial and insurance activity up 2.7%. Exports increased 0.9% q/q and 3.3% y/y, while imports were unchanged q/q. Employment rose 0.9% q/q and 1.5% y/y, hours worked increased 0.7%, and the GDP deflator rose 2.6% y/y. Prague SE -0.04% to 2,797, EURCZK +0.009% to 24.144, 10y CZGB +1.2bp to 5.068%.
Türkiye’s foreign trade in July 2026 showed exports rising 2.9% y/y to $25.6bn and imports increasing 5.1% to $33.0bn, widening the trade deficit by 13.6% to $7.3bn. The export-import coverage ratio slipped to 77.7% from 79.4% a year earlier. Excluding energy and non-monetary gold, exports rose 3.1% and imports 3.6%, leaving a deficit of $2.4bn. Manufacturing accounted for 94.4% of total exports, while intermediate goods made up 69.4% of imports. Seasonally and calendar-adjusted exports increased 2.6% m/m, while imports fell 7.2%. In January–July, exports rose 3.4% y/y and imports 4.7%, pushing the cumulative deficit up 8.3%. BI 100 -0.22% to 14,543, USDTRY +0.245% to 48.2451, 10y TGB -6bp to 34.35%.
Japan’s Tokyo CPI for August 2026 showed inflation edging up. The headline CPI rose 1.9% y/y (1.8% in July) and 0.2% m/m seasonally adjusted. The CPI excluding fresh food increased 1.8% y/y (1.7% in July) and 0.1% m/m, while the CPI excluding fresh food and energy rose 2.0% y/y (1.8% in July) and 0.3% m/m. Main upward pressure came from food (3.9% y/y), housing (1.9% y/y), and transportation/communications (2.8% y/y), with notable gains in out-of-home meals, prepared foods, fresh fish, meat, vegetables, rent, and transport fares. The rise was partly offset by declines in miscellaneous expenses, including childcare fees, and softer communication charges. On energy, electricity and city gas remained negative y/y, while gasoline also fell. Nikkei +0.41% to 66,406, USDJPY +0.145% to 159.62, 10y JGB +2.6bp to 2.931%.
Japan’s July 2026 Labour Force Survey showed a broadly stable labor market. Unemployment was unchanged at 1.69mn y/y, while the jobless rate fell to 2.4% from 2.5% in June and the jobs-to-applicant ratio was unchanged at 1.18. Employment was flat at 68.5mn y/y, while employee numbers rose 0.6% y/y to 62.33mn, extending the increase to a 53rd straight month. Regular employees rose to 37.36mn, and non-regular workers increased for a fourth month. By industry, employment rose in living-related and entertainment services but fell in wholesale and retail. The employment rate edged up to 62.6%, with the 15–64 age group at 80.5%. Non-labor force population declined by 24mn y/y to 39.24mn. On a seasonally adjusted basis, employment fell 15,000 m/m, while unemployment dropped 8,000 to 1.67mn.
New Zealand consumer confidence edged lower in August 2026, with the ANZ-Roy Morgan index falling 1 point to 98.0, still below par but well above the April low. Households remained cautious on spending: the net view on buying major household items slipped to -12, while current conditions weakened more sharply than future expectations. Perceptions of personal finances reversed much of last month’s improvement, and views on the next 12 months also deteriorated slightly. By contrast, confidence in the five-year outlook improved to its strongest since May 2021. Inflation expectations were broadly steady at 4.7% for two years ahead, and house price inflation expectations eased to 2.5%. ANZ said August was relatively quiet, but higher gas prices may have weighed on current sentiment. NZX 50 -0.81% to 13,768, NZDUSD -0.051% to 0.5948, 10y NZGB +1.3bp to 4.74%.
New Zealand’s July 2026 employment indicators showed seasonally adjusted filled jobs rose 0.3% m/m in July 2026, up 7,746 to 2.36mn (vs. June 2026). By sector, primary industries increased 0.4%, goods-producing industries 0.4%, and service industries 0.3%. Actual filled jobs reached 2.34mn, up 0.8% y/y, or 18,033 jobs, versus July 2025. The strongest annual gains came from health care and social assistance, public administration and safety, and education and training, while professional, scientific and technical services declined. Gross earnings increased 3.8% y/y to $16.5bn, up $607mn from July 2025.
The Philippines’ July 2026 merchandise trade data showed external trade rose 16.3% y/y to $22.27bn, though it was the lowest since May. The trade deficit widened to $5.97bn, up 34.9% y/y and the largest since May. Exports increased 10.8% y/y to $8.15bn, driven by electronic products, gold, and electronic equipment and parts. Electronic products remained the top export at $4.79bn, with the U.S. the largest market, followed by Hong Kong, China, Japan, and Singapore. Imports climbed 19.8% y/y to $14.12bn, led by electronic products, mineral fuels, and cereals. China remained the top supplier, followed by South Korea, Japan, Indonesia, and the U.S. APEC and East Asia dominated both exports and imports. PSEi -0.8% to 5,956, USDPHP +0.647% to 62.26, 10y PHGB +0.2bp to 7.153%.