Market Movers: Delayed
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Bob Savage
Time to Read: 7 minutes
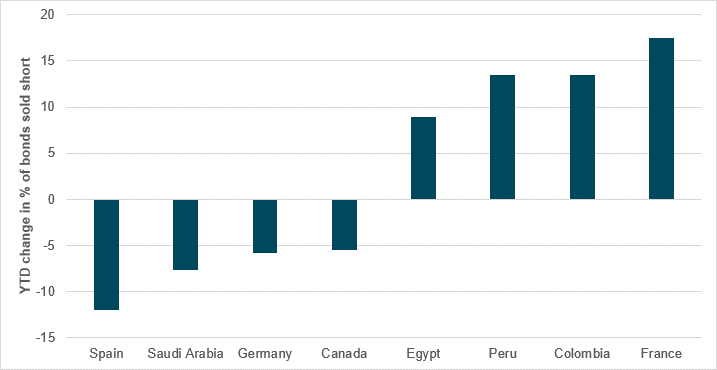
YTD change in short utilisation in sovereign bonds
Source: BNY
Inflation risk continues to permeate through markets, and the adverse reaction in rates to fears of escalation on Monday is a stark reminder of sensitivity. Meanwhile, there are other push factors in place, such as the lack labor market slack and strong investment growth related to AI/semiconductor production. Where data density is sufficient, we can use the YTD change in a bond market’s short utilization (measured as the fraction of sovereign bonds in the BNY lending program that have been sold short, expressed in percent) to assess whether the changes are simply tracking the general global supply-driven inflation view, or whether idiosyncratic factors are in play.
The eight names in the chart above have seen the biggest shifts in short utilization since the beginning of the year. The current inflationary environment supports the asymmetry, with the median gain in short utilization bigger than the median loss, but these markets all face local constraints which have clearly contributed to the changes in risk premiums. For example, France faces material stagflation risk which has added to fiscal premiums, whereas strong Spanish growth has reduced the same risks. Peru and Colombia may struggle with excessive investment growth in commodity sectors. By contrast, Canada and Germany are facing significant growth headwinds, while domestic demand is weakening strongly but in fiscally stable economies.
The third day of oil price rises has left global shares lower and U.S. equity futures weaker. The escalation in the U.S.-Iranian conflict has again been the driving force, pushing bond yields and USD higher. The economic data produced mixed results: China’s services PMI rose to a three-month high, while Australian Q1 GDP was softer than expected.
Bottom line: Economic data will be important for the U.S. session ahead, but the risks from the war and energy remain in control of the rate narrative and threat to growth. An extended period of WTI oil prices above $90/barrel is shifting expectations and testing hopes that the conflict can be looked through. Any turnaround in risk today starts from a high base given May’s gains, leaving little room for any disappointment. Markets are quietly reaching levels that are significant for investors and represent potential triggers for action. The delays and wait for moments of clarity are passing, leaving tough choices for policymakers and money managers as they look to find the right position heading into H2 2026. USD will be important in modeling out risk rebalancing, as it looks at 160 JPY and 10y bond yields at 4.50%.
Gulf hostilities escalated again overnight, with the U.S. military saying Iranian missile and drone attacks on Bahrain, Kuwait and other regional targets were intercepted, failed or fell short. U.S. Central Command said missiles aimed at Kuwait broke apart in flight, several ballistic missiles did not reach their targets and three missiles heading for Bahrain were intercepted, while U.S. forces also downed drones and struck Qeshm Island after attempted attacks. Iranian state media said the Revolutionary Guards targeted the U.S. Fifth Fleet headquarters and other sites in response to a U.S. strike. The flare-up drove oil prices higher and came as tentative Iran-U.S. talks remained unresolved. Brent +2.698% to 98.59, WTI +2.902% to 96.48, Omani crude -0.109% to 91.96, Dubai crude +1.716% to 93.906.
Japanese Prime Minister Sanae Takaichi said today that G7 leaders agreed that excessive foreign exchange volatility is harmful to the economy, underscoring the need for close international coordination on currency markets. Takaichi said Japan would work with partners, including the U.S., to deepen cooperation on foreign exchange issues, while stressing the importance of the government’s forex policy in supporting the domestic economy. She also reiterated her commitment to taking “appropriate steps” in response to currency market movements whenever necessary. USDJPY fell in response to the comments, as markets were already nervous about intervention risk as the pair approached the key 160.00 level. Nikkei +2.5% to 68402, USDJPY -0.151% to 159.67, 10y JGB +6bp to 2.639%.
BoJ Governor Kazuo Ueda has acknowledged that the situation in the Middle East “has not subsided as quickly as initially expected” and that the central bank may need to keep raising policy rates in response to inflationary pressures. He called the current supply shock during an inflationary period “something the country has not experienced in decades.” However, despite the need to respond to upside price risks, he also stated that the BoJ would need to discuss the pros and cons of a rate hike for the price target, which is a policy debate most central banks are undertaking given the impact on growth of tighter monetary policy.
President Trump has proposed new tariffs of at least 10% on imports from 60 trading partners, following a forced labor investigation and as part of a wider effort to rebuild the tariff wall previously struck down by the Supreme Court. The Office of the U.S. Trade Representative said Canada, Mexico, the EU, Taiwan and the U.K. would face a 10% rate, while goods from major economies such as China, India, Japan, South Korea, Brazil and Switzerland would be hit with 12.5%. The levies are not immediate and will undergo public comment and hearings before finalization, leaving room for changes. The move has heightened trade tensions and raised inflation risks. S&P Mini -0.09% to 7617, DXY +0.137% to 99.354, 10y UST +3.6bp to 4.479%.
The Office of the U.S. Trade Representative is seeking public comments on the scope and operation of a mechanism to promote balanced and reciprocal trade with China. The U.S.-China Board of Trade, a new government-to-government mechanism intended to manage bilateral trade on an ongoing basis. The consultation is asking for views on non-sensitive products that could be eligible for tariff modifications on both sides, with the stated goal of promoting more balanced and reciprocal trade. The USTR said the initiative is aimed at supporting American farmers, ranchers, fishermen, small businesses, manufacturers and workers, while preserving tariffs as a tool to defend U.S. economic and national security interests. Comments are due by July 10, 2026, with rebuttals or responses to comments accepted until July 27, 2026.
U.S. Fed releases Beige Book.
U.S. May ADP employment change is expected to rise to 120k vs. 109k.
U.S. May final S&P Global Services PMI is forecast to hold at 51 vs. 50.9. Final S&P Global Composite PMI is expected to hold at 51.7 vs. 51.7.
U.S. April factory orders are forecast to rise to 4.6% m/m vs. 1.5% m/m, with the ex-transportation measure expected at 0.6% m/m vs. 1.6%.
U.S. May ISM Services Index is forecast to rise to 53.8 vs. 53.6. Prices paid are expected to rise to 72.3 vs. 70.7. Employment is expected to rise to 49.0 vs. 48.0.
U.S. April final durable goods orders are forecast to hold at 7.9% m/m vs. flash 7.9% m/m and 1.3% in March; the final ex-transportation reading is expected at 1.1% vs. flash 1.1% m/m and 1.1% m/m in March.
Canada Q1 labor productivity is expected at 0.3% q/q vs. -0.1% q/q.
Canada May S&P Global Services PMI is forecast at 49.5 vs. 49.2.
Central bank speakers: The ECB’s Piero Cipollone speaks to EU lawmakers, BoJ Governor Kazuo Ueda gives a speech.
U.S. Treasury sells 17-week bills.
Mood: iFlow Mood has stabilized as June has got underway but remains firmly in risk-off territory, characterized by continued equity outflows and sustained demand for core government bonds.
FX: Outflows were concentrated in DKK, CAD, NZD and TRY, followed by BRL and CLP. In contrast, inflows favored USD, JPY, MXN and ZAR, along with EUR and GBP.
Fixed income: Demand for government bonds remained strong across G10 markets, led by Eurozone, Danish and Canadian government bonds and U.S. Treasurys, with additional buying across LatAm. Flows in EMEA and APAC were mixed, though notable inflows were recorded in Chinese and Hungarian government bonds, while Indonesian bonds continued to face selling pressure.
Equities: Selling pressure remained intense across APAC (excluding China), EMEA and LatAm. Within the G10, flows were mixed: EU, U.K. and Japanese equities saw outflows, while U.S., Australian and New Zealand equities attracted inflows.
“There is no avoidance in delay.” – Aeschylus
“Courage is more important than to be deceived by shallow victory waiting for a delayed defeat.” – Dejan Stojanović
European producer prices rallied strongly in April, with euro area industrial producer prices up 4.9% y/y after a 2.0% rise in March, while the EU also posted a 4.9% y/y gain. On a m/m basis, prices increased by 0.6% in the euro area and 0.7% in the EU. The main driver was energy, which jumped 12.3% y/y in the euro area and 12.6% y/y in the EU, while intermediate goods also accelerated. Excluding energy, prices rose 2.3% in the euro area and 2.1% in the EU. M/m gains were broad-based, though energy was slightly negative in the euro area. Euro Stoxx 50 -0.37% to 6085, EURUSD -0.181% to 1.161, BBG AGG Euro Government High Grade EUR -2.5bp to 3.245%.
The Eurozone composite PMI for May fell to 48.5 points from 48.8 in April, marking an 18-month low and signaling a further contraction in private sector activity. The decline reflected weaker demand across goods and services, with export orders falling at the fastest pace in five months and job losses picking up. Services activity edged up slightly to 47.7 from 47.6, but remained in contraction. Germany and France continued to drive the downturn, while Italy and Spain saw only marginal growth. Inflation pressures intensified, with input costs rising at the sharpest rate in three and a half years and output charges increasing for a third month in a row.
Germany’s services PMI for May came in at 48.1 points, up from 46.9 in April, indicating that the sector remained in contraction for a second straight month, but at a slower pace. New business also fell for a third consecutive month, though only marginally, while export orders declined at the sharpest rate in a year. Employment continued to edge lower and backlogs were reduced again, but the pace of job losses was modest. Cost pressures remained elevated, with input inflation near a three-year high, while output price inflation eased slightly. Business confidence rallied to a three-month high, suggesting firms saw some improvement in the outlook despite weak demand and uncertainty. DAX -0.8% to 24924, EURUSD -0.181% to 1.161, 10y Bund +3.5bp to 3.01%.
France’s S&P Global services PMI for May came in at 44.3 points, down from 46.5 in April, pointing to a deeper contraction in the sector. The survey showed the sharpest fall in output and new business since late 2020, with export orders also weakening at one of the fastest rates since the series began in 2014. Employment declined for the first time in months, while backlogs were reduced further. Cost pressures intensified, with input inflation hitting its highest level in more than three years and output prices rising at the fastest pace since June 2023. Confidence weakened to a one-year low, leaving the outlook subdued. CAC 40 -0.37% to 8179, EURUSD -0.181% to 1.161, 10y OAT +4.3bp to 3.638%.
Italy’s services PMI for May slipped to 49.4 points from 49.8 in April, indicating a second straight m/m contraction and the third decline in business activity in a row. New business returned to fall, with weak domestic demand and customer caution linked to difficult economic conditions, higher prices and geopolitical uncertainty. Export sales fell only marginally. Employment still increased for the 16th month running, while backlogs dipped just fractionally. Cost pressures intensified sharply, with input inflation rising to a 40-month high as energy and fuel costs climbed, though firms passed on only a limited part of these costs to customers. Confidence improved slightly but remained subdued. FTSE MIB -0.5% to 50325, USDJPY -0.151% to 159.67, 10y BTP +4.5bp to 3.735%.
Spain’s services PMI came in at 50.1 points in May, up from 47.9 in April, indicating that the sector stabilized following its first contraction since August 2023. The reading was supported by a marginal rise in activity and a return to growth in new business, although demand remained weak and new export orders fell for a fifth straight month. Employment growth remained solid and helped to clear backlogs. The composite PMI also improved to 50.2 from 48.7, suggesting a slight increase in overall output. However, cost pressures remained intense as fuel, energy, supplier and labor costs rose sharply, while confidence improved only modestly and remained below historical norms. IBEX 35 +0.4% to 18355, EURUSD -0.181% to 1.161, 10y Bono +3.9bp to 3.43%.
U.K. services sector activity PMI for May fell to 49.3 points from 52.7 in April, slipping below the 50-point growth threshold for the first time since April 2025 and signaling a marginal contraction. The decline reflected weaker new work, softer export sales and cautious hiring, with business confidence dropping to a 13-month low. S&P Global said subdued demand, elevated uncertainty and the Middle East conflict weighed on client spending, while input costs rose sharply on higher fuel, transport, wage and energy expenses. The broader U.K. composite PMI also eased to 49.7, indicating a renewed downturn in private sector activity as services weakness outweighed manufacturing gains. FTSE 100 -0.32% to 10340, GBPUSD -0.119% to 1.345, 10y gilt +4.1bp to 4.9%.
Sweden’s private services PMI for May rose to 53.9 points from 52.6 in April, marking a second straight month below its historical average of 55.6 but still pointing to expansion. The increase was driven mainly by stronger order intake, with employment and delivery times also contributing, while business volume declined. Delivery times lengthened for a fourth consecutive month and reached the highest level in four years. Cost pressures intensified, as the input price index jumped to 80.1 from 73.4, the highest since 2022 and well above average. The composite PMI improved to 54.9 from 53.9, indicating a broader but uneven recovery. OMX -0.33% to 3139, EURSEK +0.37% to 10.8741, 10y Swedish GB +4.2bp to 2.873%.
Norway’s Q1 external accounts showed a stronger trade balance, driven by higher oil and gas prices, with the trade surplus rising to NOK 226bn, up NOK 80bn from the previous quarter and more than 50% higher q/q. Exports of goods and services totaled NOK 667bn, down 1% y/y but up 6% vs. Q4, while imports reached NOK 441bn, up 1% y/y. The current account surplus was NOK 267bn, slightly below the year-earlier level. Net foreign assets fell by NOK 1.6tn, or nearly 8%, as global equity market turbulence and a stronger krone reduced the value of foreign investments. OSE +0.15% to 2011, EURNOK -0.14% to 10.7873, 10y NGB +3.4bp to 4.388%.
South Africa's S&P Global PMI fell to 49.6 points in May from 51.6 in April, slipping below the 50-point no-change mark for the first time in five months and signaling a marginal deterioration in private sector conditions. The decline reflected renewed falls in output and new orders, with new business dropping at the fastest pace so far this year and export orders also easing. Firms cited weak demand, uncertainty linked to the Middle East war and higher fuel prices. Input cost inflation accelerated to a near-four-year high, while selling price inflation reached a 46-month high. Employment still rose, at the fastest pace since September 2022.
Japan’s services PMI for May showed the sector stagnating, with the headline index slipping to 50.0 points from 51.0 in April, ending 13 months of expansion. New order growth slowed to a 23-month low, while foreign demand fell at the sharpest pace in over four years. Input cost inflation surged to its fastest in 43 months, driven by higher fuel, energy, raw materials and labor costs, which were attributed in part to Middle East-related supplier price hikes. This pushed output charges higher at a near-record pace, the second-fastest since the survey began in 2007. Employment rose only marginally and at the weakest rate in nine months. Business confidence improved slightly for a second successive month, but remained below the post-pandemic average. JSE TOP 40 -0.35% to 105882, USDZAR +0.415% to 16.2999, 10y SAGB +6bp to 8.678%.
Australian GDP for the March quarter rose 0.3% q/q and 2.5% y/y. Growth slowed as household and public spending were modest and cyclone disruptions hit mining and exports. Household spending increased by 0.5%, led by higher electricity, gas and fuel outlays after rebates ended, while government final consumption fell 0.2%. Exports declined by 1.1%, and net trade subtracted 0.8 percentage points from growth. Private business investment rose 6.0%, driven by machinery and equipment, but much of it was imported. The household saving ratio eased to 6.2% from 7.0%. ASX -0.32% to 5568, AUDUSD -0.237% to 0.7163, 10y ACGB +3.1bp to 4.912%.
Australia’s S&P Global Services PMI for May saw a renewed contraction, with the business activity index falling to 48.7 points from 50.7 in April. The decline reflected weaker demand, market uncertainty and higher costs, with new business dropping at the fastest pace in almost two and a half years and export orders also falling solidly. Employment declined for the first time in 17 months, while backlogs eased and business confidence fell to a two-and-a-half-year low. Input cost inflation remained elevated, though slightly lower than in April, while selling price growth stayed near April’s 39-month high. Respondents cited higher fuel costs linked to the war in the Middle East as a key pressure, alongside rising interest rates and softer sales expectations.
Australian financial aggregates for April showed total credit rising 0.7% m/m, matching March, while the annual pace accelerated to 8.0% from 6.7% in April 2025. Housing credit increased by 0.6% m/m and 7.5% y/y, while personal credit rose just 0.1% m/m but 4.3% y/y and business lending advanced by 0.7% m/m and 9.6% y/y. Broad money also strengthened, increasing by 0.8% m/m and 8.2% y/y, indicating continued expansion in monetary conditions and private sector borrowing demand.
New Zealand’s Q1 international trade data showed total exports of goods and services rising to NZ$31.4bn from NZ$29.8bn in Q1 2025, while total imports increased to NZ$29.5bn from NZ$27.4bn. Total two-way trade reached NZ$60.9bn. Services exports were a key driver, rising to NZ$11.5bn, led by travel services (NZ$7.0bn), transportation services (NZ$1.4bn) and other business services (NZ$1.0bn). Services imports also increased to NZ$8.9bn, supported by higher other business services (NZ$1.7bn), telecommunication services (NZ$1.2bn) and transportation services (NZ$1.8bn). Overall, the trade update points to stronger external activity, with services outperforming and both exports and imports expanding y/y. NZX 50 -0.42% to 13115, NZDUSD -0.439% to 0.5898, 10y NZGB +0.5bp to 4.558%.
In New Zealand, building consents issued in April showed a solid m/m pickup in residential activity. The seasonally adjusted number of new dwellings granted consent rose 11% m/m, after a 0.8% m/m decline in March. 3,692 new dwellings were consented, led by stand-alone houses and townhouse/flat/unit projects, while stand-alone houses consented increased by 6.0% m/m after a 0.6% m/m gain in March. On an annual basis, the number of new dwelling consents reached 39,087 in the 12 months to April, up 16% y/y. Non-residential building work consented was worth NZ$8.9bn in the year ended April, down 0.4% y/y, with offices, education and storage buildings the largest categories.
The RatingDog China General Services PMI rose to 54.4 points in May from 52.6 in April, indicating a stronger expansion in services activity and the fastest pace in three months. New business also accelerated, helped by improved client demand, business innovation, new project launches and firmer domestic and export orders. Employment rose for the first time in four months as backlogs increased at the fastest rate since June 2024. Cost pressures intensified, with input price inflation reaching the highest level since October 2024, driven by oil and fuel costs, increased procurement, and higher wages and other labor expenses. Despite rising costs, services firms kept selling prices broadly unchanged. The composite output index climbed to 54.0 from 53.1, showing the fastest overall output growth since February. CSI 300 +0.49% to 4939, USDCNY +0.132% to 6.7727, 10y CGB +0.8bp to 1.711%.
India’s services activity strengthened in May, with the HSBC Services PMI rising to 59.8 from 58.8 in April, signaling the fastest expansion since last November. The improvement was driven by firmer demand, higher new business and improved external orders, while firms also continued to add staff. Pricing pressure eased significantly, as charge inflation fell to a four-month low and selling price increases were the softest since January, even though input costs still rose at an above-trend pace. Composite private sector output also improved, with the HSBC India Composite PMI at 59.3, as both services and manufacturing recorded more rapid growth and new orders expanded at the fastest pace in six months. SENSEX -0.46% to 74307, USDINR +0.542% to 95.7863, 10y INGB +2.8bp to 7.041%.
Hong Kong’s private sector returned to expansion in May, with the S&P Global Hong Kong SAR PMI rising to 50.4 points from 48.6, representing a modest improvement in business conditions. Output expanded for the first time in three months, supported by a small rally in new orders and stronger export demand, while backlogs continued to fall and employment decreased only mildly. Business sentiment remained negative, though it was the least pessimistic in three months. Price pressures were again intense: input costs increased sharply, driven by the steepest surge in purchasing prices since December 2021, while output prices also rose further as firms passed on costs. Supply chain delays worsened, with delivery times lengthening for the first time in three months. Hang Seng +0.81% to 25591, USDHKD -0.022% to 7.8363, 10y HKGB -1.2bp to 1.417%.