Market Movers: Defiance
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 5 minutes
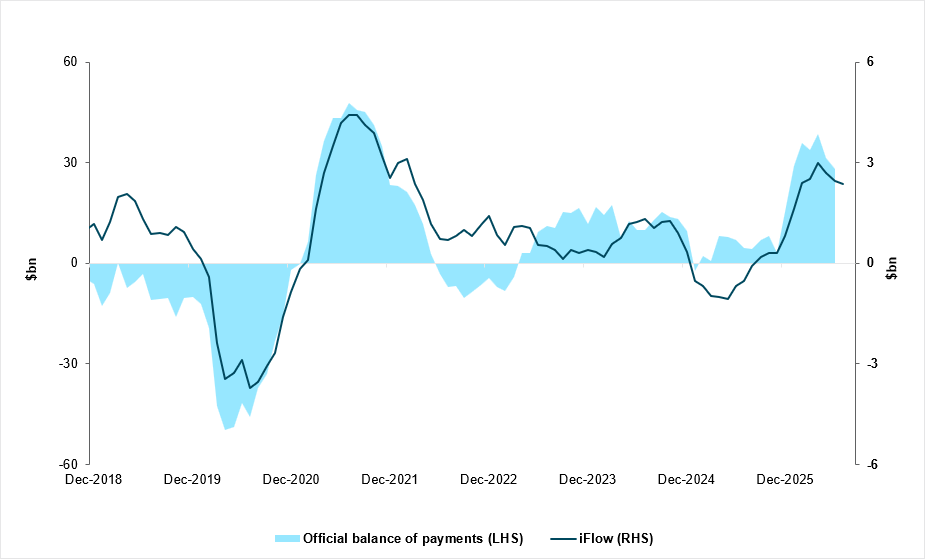
iFlow and official data indicate Brazilian inbound portfolio flows at post-COVID highs
Source: BNY
BRL flows are recovering ahead of today’s Selic rate decision, supported by renewed terms of trade interest, strong equity demand and continued purchases of Brazilian government bonds. Conviction remains limited, however, because FX volumes are exceptionally low, currency holdings are effectively neutral and the broader portfolio flow cycle appears to have peaked. The recent sharp spot outflow looks more transaction-driven than evidence of a wider reversal, particularly given the otherwise constructive asset flow backdrop. There is also still little indication that investors are expressing a dedicated food security or soft commodity theme through Brazilian assets, despite the potential benefit to the country’s terms of trade.
Despite our caution on the currency itself, the clearest validation of a stronger market view on Brazil is the continued improvement in underlying asset flows. Equities and sovereign bonds have recorded very few outflow sessions over the past month, with equity demand particularly firm. Government bond inflows should remain the main anchor for Brazil’s external liability position. Although flow magnitudes have been softer for bonds than for equities, momentum remains positive and points to continued carry demand. The main challenge is duration. The current Fed backdrop and steeper U.S. Treasury curve are more supportive of front-end exposure, while emerging markets benefit most when hawkish monetary policy and fiscal credibility reduce term premiums and improve access to longer-term funding.
Brazil’s financial account nevertheless remains strong, although momentum is slowing. Our iFlow EM portfolio flow proxy continues to track the official balance-of-payments data closely and suggests combined inflows peaked in April, which is consistent with the official figures. The pace of deterioration eased in July, but the broader direction remains clear. Following a decline of roughly $1bn in June, the monthly net financial account balance is likely to stabilize around zero rather than return quickly to the exceptional inflow levels seen earlier in the year.
Peace defied: Washington is saying that an agreement with Iran to reopen the Strait of Hormuz may be close, although the Houthis supplied an immediate reminder that a state-to-state deal may not bind every regional actor. The group said it had attacked a Saudi tanker in the Red Sea, reviving the threat of a second shipping chokepoint. Oil initially reacted with gains. The physical impact appears contained, but the attack represents a challenge to hopes that diplomacy will deliver a clean de-escalation.
Fiscal defiance: Japanese Prime Minister Sanae Takaichi is pressing ahead with a two-year cut in the country’s food consumption tax despite fiscal concerns and continued yen weakness. The measure may ease household pressure, but funding details remain the key credibility test. It also cuts against the fiscal discipline needed to make coordinated currency intervention durable. Markets may support near-term relief, but not at any cost to Japan’s debt trajectory.
Reflation resistance: Beijing wants stronger growth and domestic demand, but bond investors remain unconvinced. New long-dated offshore yuan debt cleared at record-low yields, signaling continued demand for duration and safety rather than a decisive reflation trade. That is not a rejection of stimulus, but it leaves the burden of proof firmly on policy execution.
Growth defies gloom: Europe’s latest PMIs have generally surprised to the upside, pushing back against immediate stagflation fears. That resilience is welcome, but it is not a clean invitation for the ECB to tighten again. Another hike risks turning a nascent recovery into a policy-induced slowdown.
Bottom line: U.S. services ISM and earnings now take center stage. Markets will test whether equities can defy geopolitical, policy and valuation risks to reach fresh highs. Defiance can sustain momentum, but it can also delay necessary adjustment. Expect volatility to remain elevated as investors seek protection amid the sentiment push.
Yemen’s Houthi movement has said that it carried out a missile attack on a Saudi oil tanker near the Red Sea port of Yanbu, a key hub for Saudi crude exports. The claim, which was not immediately confirmed by Saudi authorities, the vessel operator or maritime security agencies, comes amid a sharp escalation in tit-for-tat attacks between the Houthis and Saudi Arabia over recent weeks. The group has previously said it struck other Saudi tankers and oil infrastructure, while Saudi Arabia responded with airstrikes on Houthi facilities at Hodeidah. The incident heightens concern over Saudi Arabia’s alternative export route through Yanbu as disruptions in the Strait of Hormuz continue. Brent +1.147% to 80.27, WTI +0.515% to 76.16, Omani crude +0.344% to 78.83, Dubai crude -3.069% to 75.645.
Japan’s ruling Liberal Democratic Party has backed Prime Minister Sanae Takaichi’s food consumption tax cut plan amid growing fiscal concerns. The proposal, approved unanimously by the party’s General Council, is expected to receive cabinet endorsement later and would take effect in April 2027 after parliamentary debate. It would reduce the tax on food items to 1% from 8% for two years, with an extra 1% rebate or benefit payment effectively removing the burden on food purchases. The plan carries a revenue shortfall of about ¥5tn and comes as Japan faces heavier spending needs, including investment and defense commitments, while pressure on the yen and government bond yields has already intensified. Nikkei +3.66% to 66300, USDJPY +0.019% to 157.78, 10y JGB -3.1bp to 2.829%.
The RBI has left its repo rate unchanged at 5.25%, with the MPC voting unanimously to retain a neutral stance while waiting for greater clarity on inflation. The SDF remains at 5.00%, while the MSF and bank rate stay at 5.50%. India’s growth was described as resilient, supported by private consumption, investment, services, exports and credit, with real GDP projected at 6.7% for 2026-27 and risks evenly balanced. Inflation has moved back above target, reaching 4.4% in June, mainly due to food and fuel, but core inflation remained contained at 3.9%. CPI is projected at 5.0% for 2026-27 and is expected to peak in Q3 before moderating. SENSEX -0.07% to 78375, USDINR -0.228% to 95.1675, 10y INGB -2.7bp to 6.788%.
In yet another sign of growth weakness, China’s sale of 15y and 30y offshore yuan sovereign notes was priced at record-low yields despite broader pressure on global bond markets. The Ministry of Finance sold ¥1bn each of the 15y and 30y tenors at 1.99% and 2.24%, respectively, alongside shorter-dated issuance at 1.27% for 2y, 1.30% for 3y and 1.43% for 5y bonds. The overall bid-to-cover ratio reached 4.67 times, the strongest since June last year, showing investors remain willing to take duration risk in China. The demand also fits with the rally in onshore Chinese bonds, where the 10y yield fell to a two-month low even as U.S. yields rose. CSI 300 +1.24% to 4658, USDCNY -0.006% to 6.7488, 10y CGB 0bp to 1.706%.
S&P Global U.S. Services PMI is expected to remain unchanged at 53.6.
ISM Services Index is forecast to increase slightly to 54.5 vs. 54.0 last month.
Mood: iFlow mood continued to improve, driven by renewed inflows into equities, though it remained in risk-off territory.
FX: FX flows were mixed, with the Mexican peso seeing substantial inflows alongside EUR and GBP, while NZD and CNY continued to post outflows.
FI: Fixed income flows were largest in the G10 space, with Danish and Eurozone sovereign bonds continuing to see inflows, while Norwegian and New Zealand bonds faced selling pressure.
Equities: Equity flows diverged significantly across the world: Danish, Polish and Indian equities saw inflows, while Canadian, Hungarian and Mexican equities recorded the largest outflows.
“The real key to making money in stocks is not to get scared out of them.” – Peter Lynch
“Worldly wisdom teaches that it is better for reputation to fail conventionally than to succeed unconventionally.” – John Maynard Keynes
Eurozone composite PMI came in at 52.0 points in July, up from 50.0 in June, marking an eight-month high and a return to modest private sector growth at the start of Q3. The services PMI also rose into expansion territory at 51.7 from 49.4, ending a three-month downtrend. Output and new orders increased at the fastest pace since last November, with Germany, Italy and Spain all improving, while France remained in contraction. The survey pointed to softer inflationary pressures, as both input costs and output charges eased further. Confidence improved to a five-month high, but export demand remained weak. Euro Stoxx 50 +0.08% to 6492, EURUSD +0.087% to 1.1541, BBG AGG Euro Government High Grade EUR -3.4bp to 3.382%.
Germany’s services PMI reading for July was 49.8 points, up from 48.6 in June, indicating that activity fell only fractionally and moved closer to stabilization. The survey showed the first marginal rise in new business in five months, while export demand continued to decline, though at a slower pace. Employment also edged lower, but the pace of job losses was the softest in seven months. Input cost inflation and output price inflation both picked up again, helped by higher fuel costs and persistent wage pressures. Business confidence improved further, suggesting firms are becoming more optimistic about the year ahead, although high prices and geopolitical uncertainty still weighed on activity. DAX +0.19% to 26253, EURUSD +0.087% to 1.1541, 10y Bund -1.2bp to 3.095%.
French services PMI for July came in at 49.6 points, up from 46.8 in June, signaling that the sector remained in contraction but that the downturn eased to only a marginal pace. The report showed the first rise in new business since last November, although the improvement was slight and was driven by domestic demand, as export orders fell for a twelfth straight month. Backlogs declined sharply, employment dropped at a faster rate and firms remained cautious despite a firmer confidence reading. Input cost inflation eased to a five-month low, while output charges rose more slowly. The composite PMI also improved to 49.4, indicating a smaller overall decrease in private sector activity. CAC 40 +0.09% to 8674, EURUSD +0.087% to 1.1541, 10y OAT -0.5bp to 3.879%.
Italy’s services PMI climbed to 52.5 points in July, from 50.2 in June, pointing to a moderate and faster expansion in the service sector. This was the strongest reading in six months. Growth was driven by a sharper rise in new business, which saw its strongest reading YTD, while export demand also improved slightly after several months of decline. Employment increased at the fastest pace in 13 months, reflecting stronger orders and staff replacement. Cost pressures eased to their softest level since February, although selling prices rose a little faster. The composite PMI also climbed to 52.5, indicating the fastest private sector expansion in eight months. FTSE MIB +0.35% to 53725, EURUSD +0.087% to 1.1541, 10y BTP -0.3bp to 3.86%.
U.K. services PMI for July rose to 52.1 points from 48.8, moving back above the 50-point threshold for the first time in three months and indicating a modest return to growth. New business increased marginally, ending a four-month downtrend, helped by stronger technology demand, tentative recovery in consumer spending and some improvement in client risk appetite. Export business still fell, but at the slowest pace in five months. Employment shrank again, though job losses were the mildest since October 2025, while backlogs continued to fall, pointing to limited capacity pressure. Input cost inflation eased for a third successive month to its lowest mark since February, helped by lower fuel bills, and output price inflation also slowed to a five-month low. FTSE 100 +0.12% to 10893, GBPUSD +0.097% to 1.3465, 10y gilt -0.9bp to 4.888%.
Sweden’s services PMI for July was down to 54.2 points from 56.5 in June, while the PMI Composite eased to 54.7 from 56.9, showing that the recovery in business activity lost some momentum but remained in expansion territory. The services index was still above the seven-month average of 53.7, indicating continued growth after a weak Q1. All sub-indexes declined, with delivery times and new orders making the largest negative contributions, though both held above 50. Employment dropped to a new YTD low of 45.9, suggesting firms are still hesitant to hire. Cost pressure also eased sharply, as input price inflation fell to 65.5 from 75.1, which may support the outlook for the central bank later in August. OMX -0.13% to 3322, EURSEK +0.195% to 10.9982, 10y Swedish GB -1.2bp to 2.959%.
Czech flash inflation came in at 1.7% y/y in July, up from 1.5% in June, while prices rose 0.6% m/m. The reading suggests a modest reacceleration in price growth, with services inflation remaining the main driver at 4.7% y/y and goods prices still slightly negative at -0.2%. Energy prices were nearly flat y/y at -0.3%, while food and non-alcoholic beverages remained in deflation at -3.1%. The final CPI data will be published on August 11. Prague SE -0.23% to 2760, EURCZK +0.12% to 24.203, 10y CZGB -1.9bp to 4.819%.
Japanese real wages rose 1.6% y/y in June, marking a sixth straight month of gains and reinforcing the case for further BoJ tightening. Nominal wages, or total cash earnings, climbed 3.4% to ¥531,677/month, faster than the revised 3.3% rise in May, while base pay increased by 3.4% after a 3.0% gain. Overtime pay rose 2.8%, unchanged from May after revision, and special payments advanced by 3.5% following a revised 7.4% increase. The data suggest wage momentum remains supportive even as inflation persists. Nikkei +3.66% to 66300, USDJPY +0.019% to 157.78, 10y JGB -3.1bp to 2.829%.
Japanese services activity came in at 51.2 points in July, down from 52.2 in June, indicating a second straight month of expansion but at a slower pace. New business growth slipped to a 25-month low, while foreign demand fell for a fourth consecutive month, though the pace of decline eased. Input costs remained highly elevated, driven by the Middle East conflict, higher staff costs and a weak yen, and firms responded by lifting selling prices at the second-fastest rate on record. Employment growth slowed to a marginal pace as capacity pressures eased, while business confidence also softened. The report suggests inflationary pressure remains intense and may keep the policy focus on the BoJ.
New Zealand unemployment for the June quarter came in at 5.6%, up from 5.4% in the March quarter. The broader underutilization rate also rose, reaching 13.8% from 12.9%, indicating more unused labor market capacity. Employment increased by 0.5% q/q, while annual wage inflation measured by the labor cost index was 2.0% and average ordinary-time hourly earnings were NZ$44.62. Stats NZ also said 166,500 people were unemployed, with long-term unemployment rising; the biggest increases in underutilization were among young people and the Māori population. NZX 50 +0.67% to 13997, NZDUSD -0.492% to 0.5865, 10y NZGB -7.5bp to 4.657%.
China’s general services PMI for July came in at 50.4 points, from 54.1 in June. This represents the weakest pace of service sector growth since September 2024 while still remaining in expansionary territory. The release showed that total activity and new business both slowed for a second straight month, with domestic demand softer, although overseas demand stayed resilient and export business remained above 50. Employment rose for a third month to make the longest run of job gains since H2 2024, and backlogs continued to build. Price pressures eased further, with input cost inflation close to a seven-month low and output charges rising only modestly. Business confidence remained positive but weakened to its softest print since February 2020. CSI 300 +1.24% to 4658, USDCNY -0.006% to 6.7488, 10y CGB 0bp to 1.706%.
Philippine inflation was 6.2% y/y in July, easing from 6.4% in June but remaining well above the 0.9% recorded a year earlier. Core inflation also cooled to 4.2% from 4.4%. The Philippine Statistics Authority said the moderation was mainly driven by slower price growth in transport, education services, and restaurants and accommodation services, although larger increases were still seen in housing, utilities, health and some other categories. Food inflation held at 5.3%, keeping it a major contributor to headline inflation. On a YTD basis, average inflation reached 5.0%, while inflation slowed to 4.4% in the National Capital Region and to 6.7% elsewhere. PSEi -0.16% to 6286, USDPHP -0.7% to 60.756, 10y PHGB -9bp to 7.157%.