Market Movers: Cross-currents
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Wee Khoon Chong
Time to Read: 5 minutes
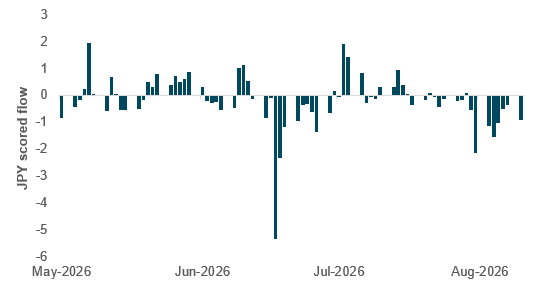
JPY scored flows vs. USD
Source: BNY
On June 17, despite a widely anticipated BoJ rate hike, institutional investors poured into USD and sold JPY due to the hawkish interpretation of new Fed Chair Kevin Warsh’s first meeting at the helm of the FOMC. This represented quite a shock to the market and led to significant USD appreciation – not just against the yen, but also more broadly.
Fast forward to the end of July, when joint intervention between the U.S. and Japan was aimed at weakening the USD/JPY cross. Despite the move, real money bought USD and sold yen, perhaps indicating the perception of a USDJPY buying opportunity. With the yen having weakened since July 31, and observing the behavior of institutional investors, that begs the question of whether these interventions have any durable efficacy.
Long-end yield pressure: Long-end yields have continued to come under upward pressure, driven by high energy prices, monetary policy tightening expectations and fiscal concerns. Chinese government bonds stood out as the most resilient in the region. The yield on 30y South Korean government bonds (KTBs) hit a record high and the 10y JGB-CGB spread returned to the upper end of its range at around 115bp, while 30y U.S. Treasury yields remain elevated.
Continued tech optimism: Tech optimism has persisted as quarterly earnings delivered upside surprises in both revenue and profits. Reports that regional sovereign wealth funds may invest in South Korean technology companies provided an additional boost. The region’s healthy pipeline of tech-related IPOs will be a key test of investor sentiment. Near-term attention is on Unitree Robotics, whose retail offering was reportedly 8,000 times oversubscribed.
Volatility continues to cool: Improving risk sentiment has translated into broad easing in cross-asset volatility. KOSPI volatility has roughly halved from its late-June peak, while volatility across the Nikkei, the Euro Stoxx and U.S. equities has fallen back to relatively low levels. Credit conditions have also improved, with Asia IG and Eurozone high-yield crossover spreads retracing tighter. Meanwhile, EM and G7 FX volatility has stabilized since the start of the month, reinforcing the broader normalization in risk conditions.
Bottom line: Risk sentiment is continuing to improve, with tech optimism and easing cross-asset volatility supporting risk assets and tighter credit spreads. However, the rates backdrop remains a key constraint, as high energy prices, fiscal concerns and tighter policy expectations are keeping long-end yields under upward pressure. The resulting mix remains supportive for risk-taking, but with duration increasingly the key vulnerability.
Boston Fed President Susan Collins has said poorer Americans are increasingly struggling to make ends meet, with inflation and higher energy costs weighing heavily on households and businesses in the northeast of the country. She said price pressures remain too high, especially for oil-linked heating costs, and that inflation has been above the Fed’s 2% target for more than five years. Collins backed leaving rates unchanged in July, calling policy mildly restrictive, but said she would be open to a rate increase as early as September if incoming data justify tighter policy. She noted that the labor market is mixed and weak payrolls should not be overread, though inflation risks still dominate. Her comments came ahead of the July U.S. inflation release, which is expected to show that price growth remains elevated. S&P Mini +0.15% to 7759, DXY +0.054% to 99.881, 10y UST -1.1bp to 4.678%.
President Trump is weighing fresh campaign pledges ahead of the U.S. midterm elections, including possible cuts to capital gains tax and a broader exemption for home sales. National Economic Council Director Kevin Hassett has said Trump wants policies that could help Republicans win in November, while Larry Kudlow said Trump is interested in indexing capital gains for inflation and raising the home-sale exemption for properties worth up to $2mn. However, most tax changes would require congressional approval, making passage before the midterms unlikely. The report says the proposals would mainly benefit wealthier households, creating political vulnerability for Republicans. The White House said any policy announcement would come directly from the administration.
Official comments ahead of the U.K.’s October 28 budget signal further support for high street businesses, with Prime Minister Andy Burnham saying he wants to go “further” on business rates relief. He said the government will bring forward VAT cuts on electricity and business rate cuts for pubs, while reviewing broader business rates support for high street firms. Burnham acknowledged that the cost of doing business remains too high and said businesses are under pressure from energy costs and higher employer national insurance contributions. He stressed that any additional measures must be affordable, given the “difficult financial outlook” and limited fiscal room. The key message is that more targeted relief for small businesses and high street venues is being considered, but without promises beyond what can be fully funded. FTSE 100 -0.17% to 10844, GBPUSD +0.089% to 1.351, 10y gilt +0.3bp to 4.967%.
New Zealand Prime Minister Christopher Luxon has survived a leadership challenge after Defense Minister Chris Penk mounted a bid to unseat him. Luxon said the National Party’s caucus had reaffirmed its confidence in his leadership. The episode leaves Luxon in office but politically weakened with just under three months to go before New Zealand’s November 7 election. The National Party has been trailing behind Labour in recent polls, and Luxon’s personal approval has slipped. The challenge is the second confidence vote Luxon has faced this year, reinforcing concerns about leadership instability and distracting the government from its campaign focus on the economy. Markets took the news calmly, with the New Zealand dollar slightly lower and bond yields little changed. NZX 50 -0.89% to 13738, NZDUSD -0.188% to 0.5867, 10y NZGB +1.2bp to 4.694%.
The IEA has said that global oil markets tightened further in July, with demand, supply, refining runs and inventories all hit by renewed geopolitical disruptions and high fuel prices. The 2026 oil demand outlook was cut to a decline of 1.6 million barrels/day (b/d) – 510k b/d lower than last month’s estimate – as the closure of the Strait of Hormuz and high prices weigh on consumption. Supply rose to 101.5 million b/d in July but remained well below year-earlier levels, with Gulf output still largely shut in; Q3 supply was also down substantially. Refinery crude throughputs climbed to 80.9 million b/d in July but remained nearly 5 million b/d below last year’s levels, with further cuts to Q3 runs expected. Observed inventories fell by 69 million barrels in July, while crude prices swung sharply higher amid backwardation and tighter product markets. Brent +0.293% to 89.17, WTI +0.409% to 83.54, Omani crude +3.967% to 88.6, Dubai crude +0.592% to 84.561.
U.S. July CPI is forecast at 0.1% m/m, 3.4% y/y vs. -0.4% m/m, 3.5% y/y in June. Core CPI is forecast at 0.2% m/m, 2.5% y/y vs. 0.0% m/m, 2.6% y/y in June.
U.S. real average weekly earnings are released; last month’s reading was 0.2% y/y. The prior change in real average hourly earnings was 0.0% y/y.
U.S. July federal budget balance is forecast to widen to -$346bn vs. -$291.1bn.
Canada June building permits are forecast to rise to 0.8% m/m vs. -1.7% m/m.
U.S. Treasury sells $72bn in 17-week bills and $42bn in 10y notes.
Mood: iFlow Mood remains in risk-neutral territory, bolstered by strong equity buying.
FX: FX flows were slightly biased toward outflows, with JPY, BRL and USD all coming under selling pressure. MXN, GBP and KRW all saw inflows.
FI: Fixed income flows were modest and skewed toward inflows with Argentine, U.K and Eurozone sovereign bonds all seeing inflows, while Norwegian bonds posted outflows.
Equities: Inflows into equities were broad-based. Taiwanese, Polish and Indian equities led the way, while Argentina saw outflows.
“When investing, pessimism is your friend, euphoria the enemy.” – Warren Buffett
“Price is what you pay; value is what you get.” – Benjamin Graham
German inflation accelerated in July, with CPI at +2.8% y/y and +0.8% m/m. The rise from +2.3% y/y in June was driven mainly by energy, which remained the key inflation contributor as motor fuel prices surged after the fuel discount ended on June 30 and crude oil prices rose. Energy prices were +8.3% y/y and +5.0% m/m, with motor fuels up +23.0% y/y and +11.2% m/m. Food inflation remained subdued at +0.4% y/y and +0.1% m/m, while core inflation (excluding food and energy) was +2.4% y/y. Services rose +2.9% y/y after +3.1% in June, supported by package holidays, social protection and vehicle repair costs. The HICP came in at +2.8% y/y and +0.9% m/m. DAX +0.26% to 26391, EURUSD 0% to 1.1537, 10y Bund +0.2bp to 3.16%.
Italy’s consumer price data for July showed national inflation at +0.3% m/m and +2.9% y/y, easing slightly from +3.0% in June and matching the flash estimate closely. The slowdown was driven by softer gains in non-regulated energy products, unprocessed food and miscellaneous services. Offsetting this, regulated energy products, transport services and recreation/personal care services accelerated. Goods inflation eased to +3.2% y/y from +3.3%, while services rose to +2.7% from +2.6%, narrowing the services-goods gap to -0.5 percentage points from -0.7. On a m/m basis, the increase was mainly led by regulated energy, transport services, recreation/personal care, non-regulated energy, processed food and housing services, while unprocessed food declined. HICP was -1.0% m/m and +2.9% y/y, reflecting summer sales. FTSEMIB +0.1% to 53760, EURUSD +0.009% to 1.1538, 10y BTP -1bp to 3.94%.
Swedish household consumption rose 1.6% m/m and 4.3% y/y in June. The gain was broad-based across all purpose categories both m/m and y/y. On the m/m side, personal care, social protection, and miscellaneous goods and services posted the strongest increase, up 5.9%. On the y/y measure, information and communication led growth, rising 12.8% y/y. The weekly indicator also pointed to firmer spending, with household consumption up 1.7% in weeks 24-27 versus weeks 20-23. Across the weekly breakdown, all purposes rose, led by restaurants and accommodation services at +4.9%. OMX +0.05% to 3299, EURSEK -0.168% to 10.9911, 10y Swedish GB +0.7bp to 3.026%.
Japanese business sentiment improved in August, according to the Reuters Tankan survey, with manufacturers’ confidence rising to +18 points from +13 in July as semiconductor-related demand boosted orders. The gains were led by chemicals and metal/machinery, while transport equipment stayed flat, reflecting mixed auto sector conditions. Non-manufacturers also strengthened to +28 from +25, supported by solid domestic consumption and broader improvements in wholesale trade, information services and other services. Respondents pointed to strong order intake for semiconductor-related products, including a sharp pickup in machinery and precision equipment demand both in Japan and overseas. Looking ahead, manufacturers expect sentiment to ease to +16 in November, suggesting some caution, while non-manufacturers are seen holding at +28. Nikkei +0.83% to 67524, USDJPY -0.088% to 159.37, 10y JGB +2.9bp to 2.857%.
The BoJ has reported that M2 rose 2.2% y/y in July, slowing from 2.3% in June, while M3 increased by 1.4% y/y vs. 1.6%. M1 growth eased to 0.5% y/y from 2.2% in June. Broadly defined liquidity (L) expanded by 4.4% y/y, down slightly from 4.5%, with the outstanding stock at ¥2.338qn. Within broad liquidity, investment trusts and pecuniary trusts were again the main positive contributors, while bank debentures and CDs remained weak. Overall, the release points to steady but moderating money growth, with demand deposits and narrow money losing momentum.
South Korea’s labor market was broadly stable in July. The economically active population rose to 29.912 million, up 0.5% y/y, while the labor force participation rate was unchanged at 65.0%. Employment increased to 29.136 million, up 0.4% y/y, but the employment-to-population ratio slipped 0.1 percentage point to 63.3%. Unemployment rose to 776k, up 6.9% y/y, lifting the unemployment rate to 2.6% from 2.4% a year earlier. The economically inactive population also edged higher to 16.103 million, up 0.6% y/y. By sector, gains were led by business, personal and public services, and electricity, transport, communication and finance, while agriculture, manufacturing and construction continued to shed jobs. KOSPI +3.68% to 6579, USDKRW -0.3% to 1417.65, 10y KTB +6bp to 4.295%.