Market Movers: Coordination
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 5 minutes
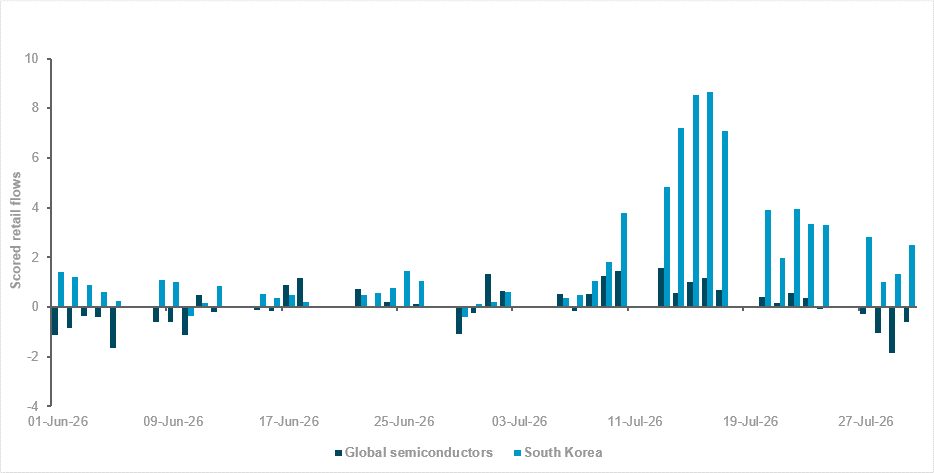
Retail flows into South Korea still excessive compared with global semiconductor flows
Source: BNY
South Korea’s retail investors were deeply embedded in the KOSPI rally and subsequent unwind, with participation concentrated in highly leveraged products linked to the country’s two dominant chipmakers. Single-stock leveraged ETFs, which elsewhere are usually the preserve of professionals, were in the case of South Korea mostly owned by retail investors. Together with the underlying chip stocks, they at one point accounted for more than 70% of daily traded value. That structure amplified both upside and downside: Bloomberg reports that the KOSPI has moved by 5% or more in roughly one in four sessions this year, while retail investors sold heavily into Friday’s record rebound. The key point is that South Korea’s equity volatility is not just about AI fundamentals, but about intense retail participation through a leveraged market structure.
Despite the severe volatility, our data indicate that it is still too early to call total capitulation in global retail participation in South Korea, even if semiconductor stocks globally have come under much greater pressure. Scored daily retail flows into South Korea have fallen sharply since early July, with the earlier astronomical readings above 8 clearly unsustainable. Even so, flows have only fallen back into the 2-4 score range; this remains well above the levels seen in June and a clear outlier in global performance. By contrast, global semiconductor flows have shifted toward strong outflows, with last Wednesday registering the largest wave of retail selling in two months. South Korean memory stocks have clearly contributed to the broader semiconductor underperformance, but the buy-the-dip mentality in retail flows toward South Korea remains intact.
Talk becomes action: FX has provided the clearest example of coordination. The U.S. and Japan have jointly intervened to strengthen the yen, their first such operation since 1998. The currency rallied sharply, weighing on Japanese exporters and contributing to a softer Asian session. The KOSPI also surrendered part of Friday’s extraordinary rebound. Coordination has reduced the immediate currency instability, but it has not removed the rate and fiscal pressures driving underlying yen weakness.
Diplomacy buys time: The U.S. and Iran are also communicating again, likely through regional intermediaries. President Trump canceled planned strikes after allies outlined a potential framework covering de-escalation, the Strait of Hormuz and Iran’s nuclear program. Oil prices have fallen sharply in response. The relief is meaningful but provisional. Tehran has yet to endorse the reported framework publicly, leaving markets alert to another reversal.
Political coordination delivers: Washington has produced a rare domestic agreement. U.S. Senate appropriators unveiled a bipartisan stopgap bill that would fund the government at broadly current levels until December 11. A vote is expected before the August recess. The deal reduces the near-term shutdown risk and removes one avoidable source of fiscal uncertainty during the midterm campaign.
The Fed’s test: The coordination deficit at the Federal Reserve persists. The FOMC’s recent “family fight” has left markets unsure whether the current stance reflects deliberate patience or policy drift. This week’s labor data will test whether the Fed has a credible path forward. The JOLTS report arrives on Tuesday, followed by payrolls on Friday. Strong data could revive tightening expectations; weakness would validate restraint but sharpen growth concerns.
Bottom line: Better coordination has reduced several tail risks and improved sentiment, but markets remain nervous. Diplomacy must hold, currency intervention must retain traction, and earnings and labor data must provide the policy clarity the Fed has yet to supply.
Japan’s finance ministry and the U.S. Treasury have intervened in the foreign exchange market to support the yen. Japanese Finance Minister Satsuki Katayama said the joint action was aimed at countering excessive volatility and disorderly movements in recent months. She added that Tokyo would not hesitate to carry out further joint intervention if needed, making it clear that the authorities remain ready to defend the currency after it weakened to its lowest level against the dollar since 1986. The move, the first coordinated outright support for the yen in nearly 30 years, follows market concern over Prime Minister Sanae Takaichi’s spending plans and comes as traders watch for more intervention. Nikkei -0.94% to 63755, USDJPY -0.426% to 156.73, 10y JGB +3bp to 2.835%.
Emerging market equities slipped as South Korean chipmakers ceded part of Friday’s record rally, underscoring how fragile the AI and semiconductor rebound remains. The MSCI EM equity index fell 1.1% after a 6.6% jump, while the KOSPI dropped 5% as Samsung Electronics and SK Hynix both declined by more than 7%. The pullback suggests the South Korean rally was driven partly by forced deleveraging and position adjustment rather than a clean return of conviction, with leverage still amplifying volatility. EM currencies were firmer as oil prices eased after President Trump said new U.S.-Iranian talks would begin, reducing some energy and dollar pressure. The Malaysian ringgit underperformed after a state election result raised fresh political uncertainty. KOSPI -5.12% to 6257, USDKRW -0.654% to 1429.65, 10y KTB -4.9bp to 4.262%.
President Trump said new Iran talks would begin on Monday afternoon after he scrapped a planned military strike, framing the decision as a response to allied appeals from the Middle East, including Saudi Arabia, and as part of efforts to reach a broader deal. He said the talks could help reopen the Strait of Hormuz and keep alive a path to curb Iran’s nuclear program. Iranian Foreign Minister Abbas Araghchi said Iran and Oman were in the final stages of negotiations on a new route through the strait. The remarks eased market stress, with Brent crude falling sharply in early Monday trading after recent gains. However, Iran stated today that the country currently has “no negotiations with the U.S.” Brent -4.652% to 83.84, WTI -5.799% to 79.76, Omani crude -3.525% to 79.93, Dubai crude +1.8% to 81.109.
U.S. Senate appropriators reached a bipartisan funding deal on Sunday to avert a government shutdown at the end of September. If approved, the stopgap measure will keep the government funded through to December 11. The bill includes adjustments for the women, infants and children nutrition program, the disaster relief fund and shipbuilding, while also temporarily blocking changes to the federal grant approval process. Senate leaders are planning an initial procedural vote on Monday night and aim to pass the measure before recess. Key lawmakers from both parties said the deal preserves time for broader appropriations talks and helps avoid disruption to federal workers and vital programs. S&P Mini +0.47% to 7555, DXY -0.139% to 99.776, 10y UST -4.7bp to 4.688%.
S&P Global U.S. Manufacturing PMI is forecast at 53.8, unchanged from last month.
U.S. ISM Manufacturing is forecast to rise to 53.9 vs. 53.3.
Mood: iFlow Mood remained in risk-off territory with strong fixed income flows into G10 markets.
FX: FX flows were mixed globally: GBP and PEN saw inflows while NZD and CAD recorded outflows in the G10 space and CNY and KRW came under pressure in APAC.
FI: FI flows were strong into G10 with Eurozone, Danish and Japanese sovereign bonds all seeing strong inflows, along with Treasurys and gilts. New Zealand sovereign bonds posted substantial outflows to go along with outflows from NZD.
Equities: Global equity flows were mixed, with Danish and Colombian equities remaining popular while investors reduced exposure to Canadian equities.
“The impact of intervention usually does not last very long.” – Haruhiko Kuroda, former BoJ Governor
“The weak yen has no merit.” – Tadashi Yanai, founder of Uniqlo owner Fast Retailing
The Eurozone manufacturing PMI rose to 51.9 points in July from 51.4 in June, while the output index climbed to 52.9, the strongest reading in 52 months. The data indicate the fastest increase in factory production since March 2022, supported mainly by backlog completion and only a slight rise in new orders, which remained sluggish. Demand from export markets weakened again, though only marginally. Firms continued to cut employment, purchases and inventories, while supply chain pressures remained elevated but eased somewhat. Input and output price inflation also moderated, and business confidence improved to a five-month high, although it remained below the long-run average, suggesting the recovery may still be fragile. Euro Stoxx 50 +0.79% to 6408, EURUSD -0.035% to 1.1523, BBG AGG Euro Government High Grade EUR 0bp to 3.456%.
Germany’s manufacturing PMI rose to 52.2 points in July from 50.3 in June, indicating a solid improvement in factory conditions at the start of Q3. Output growth accelerated to its fastest pace since February 2022, supported by stronger export sales and efforts to clear backlogs of work. New orders also rose for the second month in a row, while purchasing activity recovered slightly after two months of decline. Cost pressures eased further, with input inflation and factory gate charges both cooling, though supply chains remained strained and employment continued to fall. Business confidence was again cautious and below pre-conflict levels. DAX +1.33% to 25970, EURUSD -0.035% to 1.1523, 10y Bund -5.3bp to 3.153%.
France’s manufacturing PMI for July fell to 49.8 points from 51.2 in June, indicating a renewed deterioration in factory conditions as the third quarter began. The survey showed faster declines in new orders, output and purchasing activity, with export demand weakening at the sharpest pace in a year. Firms also reduced finished goods inventories and cleared backlogs, while employment rose at the fastest pace since December. Supply chain pressures remained evident, though input cost inflation eased to a four-month low. Business confidence improved for a second successive month, but the report still pointed to fragile demand, weak client sentiment and ongoing uncertainty for the manufacturing sector. CAC 40 +1.01% to 8596, EURUSD -0.035% to 1.1523, 10y OAT -6.4bp to 3.935%.
Italy’s manufacturing PMI for July came in at 51.3 points, down from 52.2 in June, signaling only a modest improvement in operating conditions as output growth softened. The survey showed the first fall in new orders in three months, with export orders also declining for the first time in five months, suggesting that the earlier boost from stockpiling had faded. Manufacturers responded by cutting purchasing and trimming payrolls slightly, while backlogs were reduced at the fastest pace this year. Cost and selling price inflation eased further, although both remained elevated, and confidence in future output weakened amid geopolitical uncertainty and persistent price pressures. FTSE MIB +0.75% to 52564, EURUSD -0.035% to 1.1523, 10y BTP -7.8bp to 3.942%.
Spain’s manufacturing PMI reading for July was 50.2 points, up from 49.7 in June, signaling only marginal growth as the sector remained subdued. Output and new orders both fell again, while employment declined for an eleventh straight month, reflecting weak demand, cautious hiring and continued uncertainty linked to the Middle East conflict. Supply disruptions persisted, with longer supplier delivery times, lower purchasing activity and reduced inventories. Inflation pressures eased sharply, however, as input costs and factory gate prices rose at their slowest pace in five months. Despite ongoing weakness, business sentiment improved to a five-month high on expectations of better market conditions. IBEX 35 +0.47% to 19904, EURUSD -0.035% to 1.1523, 10y Bono -6bp to 3.592%.
U.K. manufacturing PMI for July came in at 51.9 points, down from 52.5 in June, indicating continued expansion but at a slightly slower pace. The headline reading stayed above the 50-point neutral mark for a ninth straight month, supported by stronger output, new orders and export sales. Production rose for a fourth successive month and at the fastest rate in nearly two years, while new business increased for an eighth consecutive month. Input price inflation eased sharply to a five-month low and supplier delays improved, but hiring slowed to near-stagnation and business confidence remained subdued on worries about trade tensions, taxes and regulation. PMI FTSE 100 +0.11% to 10880, GBPUSD -0.193% to 1.3457, 10y gilt -7.5bp to 4.975%.
Swiss CPI came in at 0.4% y/y in July, while the index fell 0.1% m/m to 101.1 points. Core inflation also eased, rising 0.3% y/y and declining 0.1% m/m. The m/m drop was driven mainly by lower prices for air transport, diesel, petrol, and seasonal clothing and footwear. These decreases were partially offset by higher prices for parahotel accommodation, heating oil, car rental and car sharing, and restaurants and hotels. Imported prices fell 1.1% m/m, while domestic prices rose 0.1%. SMI +0.58% to 14429, EURCHF +0.147% to 0.93172, 10y Swiss GB -1.6bp to 0.421%.
Switzerland’s procure.ch PMI for July remained in expansion, with the manufacturing PMI holding above 50 points for a fifth straight month despite falling 1.1 points to 53.2. The production component eased by 2.8 points but remained solid at 54.2, while order backlogs held near 53, indicating a continued recovery in industrial order volumes. Employment remained the weak spot, falling 1.3 points to 47.7. Cost and supply pressures intensified, with purchasing prices rising to 74.2 and delivery times to 62.9, reflecting stress in global supply chains and higher prices for petroleum-based products. Services were much stronger, with the services PMI jumping 4.1 points to 63.9, the highest level since August 2017, driven by new orders, business activity and a recovery in employment.
Sweden’s industrial PMI for July was 55.8 points, down from 58.0 in June. This marks the first decline in five months, but the index was still above its historical average for a thirteenth straight month. The headline reading remained consistent with ongoing expansion, as new orders, output and employment continued to rise, although momentum softened after a strong second quarter. All sub-indexes fell, with the largest drag coming from production, followed by inventories, new orders, delivery times and staffing. Supplier raw material and input prices also eased sharply to 67.3 from 80.4, the lowest in five months, suggesting lower cost pressure and reduced near-term inflation risks, even if supply chain disruptions could revive price pressures. OMX +0.37% to 3259, EURSEK +0.115% to 10.9888, 10y Swedish GB -3.9bp to 3.002%
Polish manufacturing PMI improved to 49.0 points in July from 46.1 in June, but remained below the 50-point no-change mark for a fifteenth straight month, showing only a marginal deterioration in business conditions. S&P Global said output and new orders fell more slowly, while employment rose for the first time since April 2025, though job creation was still marginal. Export orders also declined at the slowest pace since January. Input buying fell again, inventories were reduced and delivery times lengthened less than before. Inflationary pressures eased further, with input cost growth slowing for a third successive month and output price inflation at its weakest since March. WIG +0.75% to 148510, EURPLN -0.144% to 4.3014, 10y PGB -8.2bp to 5.677%.
Czechia’s manufacturing PMI came in at 52.2 points in July, down from 53.9 in June, indicating a continued but slower expansion in the sector. Output and new orders still rose, but at softer rates, while export sales grew faster than at any time since August 2021. Employment returned to contraction as firms cut costs, and input buying and inventories were restrained. Inflationary pressures eased modestly, though input costs and output charges remained high by historical standards. Supplier delivery times continued to lengthen, but less severely than before. Business confidence slipped to a three-month low but remained above its long-run average, suggesting firms are still cautiously optimistic about the outlook. Prague SE +0.57% to 2721, EURCZK -0.005% to 24.214, 10y CZGB -3.5bp to 4.921%.
Turkish consumer price inflation for July was 31.75% y/y and 1.78% m/m. CPI was up 19.86% vs. end-2025 and 31.90% on a 12-month average basis. Food and non-alcoholic beverages remained the largest driver, climbing 37.53% y/y and contributing 8.94 percentage points to the headline rate. Housing and transport also added significant pressure, rising 40.32% and 30.83%, respectively. On a m/m basis, transport, housing and food were the main contributors, while clothing and footwear fell. Core measures also remained elevated, with CPI excluding unprocessed food, energy, alcohol, tobacco and gold up 30.98% y/y. BI 100 -0.26% to 13423, USDTRY +0.055% to 47.5377, 10y TGB -8bp to 34.85%.
Japanese manufacturing PMI for July came in at 54.5 points, little changed from 54.8 in June, signaling a further strong improvement in factory conditions at the start of Q3. Production rose at the fastest pace in more than 12 years, helped by the sharpest increase in new orders in well over four years and the strongest export demand in just over five years. Hiring and purchasing activity both increased solidly, while backlogs of work kept building. Cost pressures remained elevated, although they eased slightly vs. June, and selling prices continued to rise sharply. Nikkei -0.94% to 63755, USDJPY -0.426% to 156.73, 10y JGB +3bp to 2.835%.
Australia’s manufacturing PMI rose to 52.0 points in July from 51.5 in June, which marks a fourth straight month above the 50-point no-change threshold and a modest improvement in sector conditions. Output and new orders both returned to growth, with production expanding for the first time in six months and job creation picking up at the fastest pace since January. However, demand remained muted and price and supply pressures elevated, with input costs still rising sharply and delivery times lengthening, though both trends eased somewhat. New export orders fell again, while firms rebuilt inventories and remained more optimistic about the next 12 months. ASX +0.21% to 5849, AUDUSD -0.072% to 0.7014, 10y ACGB +0.1bp to 4.928%.
China’s manufacturing PMI for July came in at 50.9 points, down from 51.7 in June, but still above the 50-point no-change mark for an eighth straight month. This signals continued expansion in factory activity. New orders rose for a fourteenth consecutive month, although at a softer pace, while output also increased for the eighth month in a row. Employment edged higher for a second straight month and at the fastest rate since August 2023. Cost pressures eased further, with input inflation slowing to a six-month low and output prices broadly flat. Firms cut purchasing for the first time since November 2025 as input stocks kept building, while business confidence improved slightly. CSI 300 -0.98% to 4543, USDCNY +0.011% to 6.7538, 10y CGB -0.4bp to 1.711%.
India’s manufacturing PMI for July fell to 53.5 points from 54.2 in June, the weakest reading since August 2021 but still above the 50-point mark that signals expansion. The survey showed continued growth in output and new orders, though both slowed, while new export orders accelerated strongly. Firms reported better supply chain conditions, with delivery times improving sharply, and they increased input buying and inventories as a buffer against disruption. Employment growth eased to a 29-month low. Cost inflation softened to a five-month low, but selling prices still rose moderately. Business sentiment improved vs. June as companies cited resilient demand and stronger overseas orders. SENSEX +0.86% to 78763, USDINR -0.083% to 95.3138, 10y INGB +0.8bp to 6.846%.
Indonesian inflation came in at 2.88% y/y in July, with the consumer price index at 111.73 points. Price pressures were broad-based across expenditure groups, led by transport at 5.12% and personal care and other services at 9.04%, while food, beverages and tobacco rose 2.97% and restaurant services increased by 2.55%. By region, Papua Barat Province posted the highest inflation at 5.47%, while Papua Selatan Province recorded the lowest at 1.46%. Among regencies and municipalities, Aceh Tengah Regency saw the highest inflation at 6.91%. Prices fell 0.14% m/m, while YTD inflation reached 1.65% and core inflation was 2.76% y/y. JCI -0.23% to 6222, USDIDR -0.056% to 17990, 10y IDGB -0.9bp to 7.327%.