Market Movers: Convergence
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 6 minutes
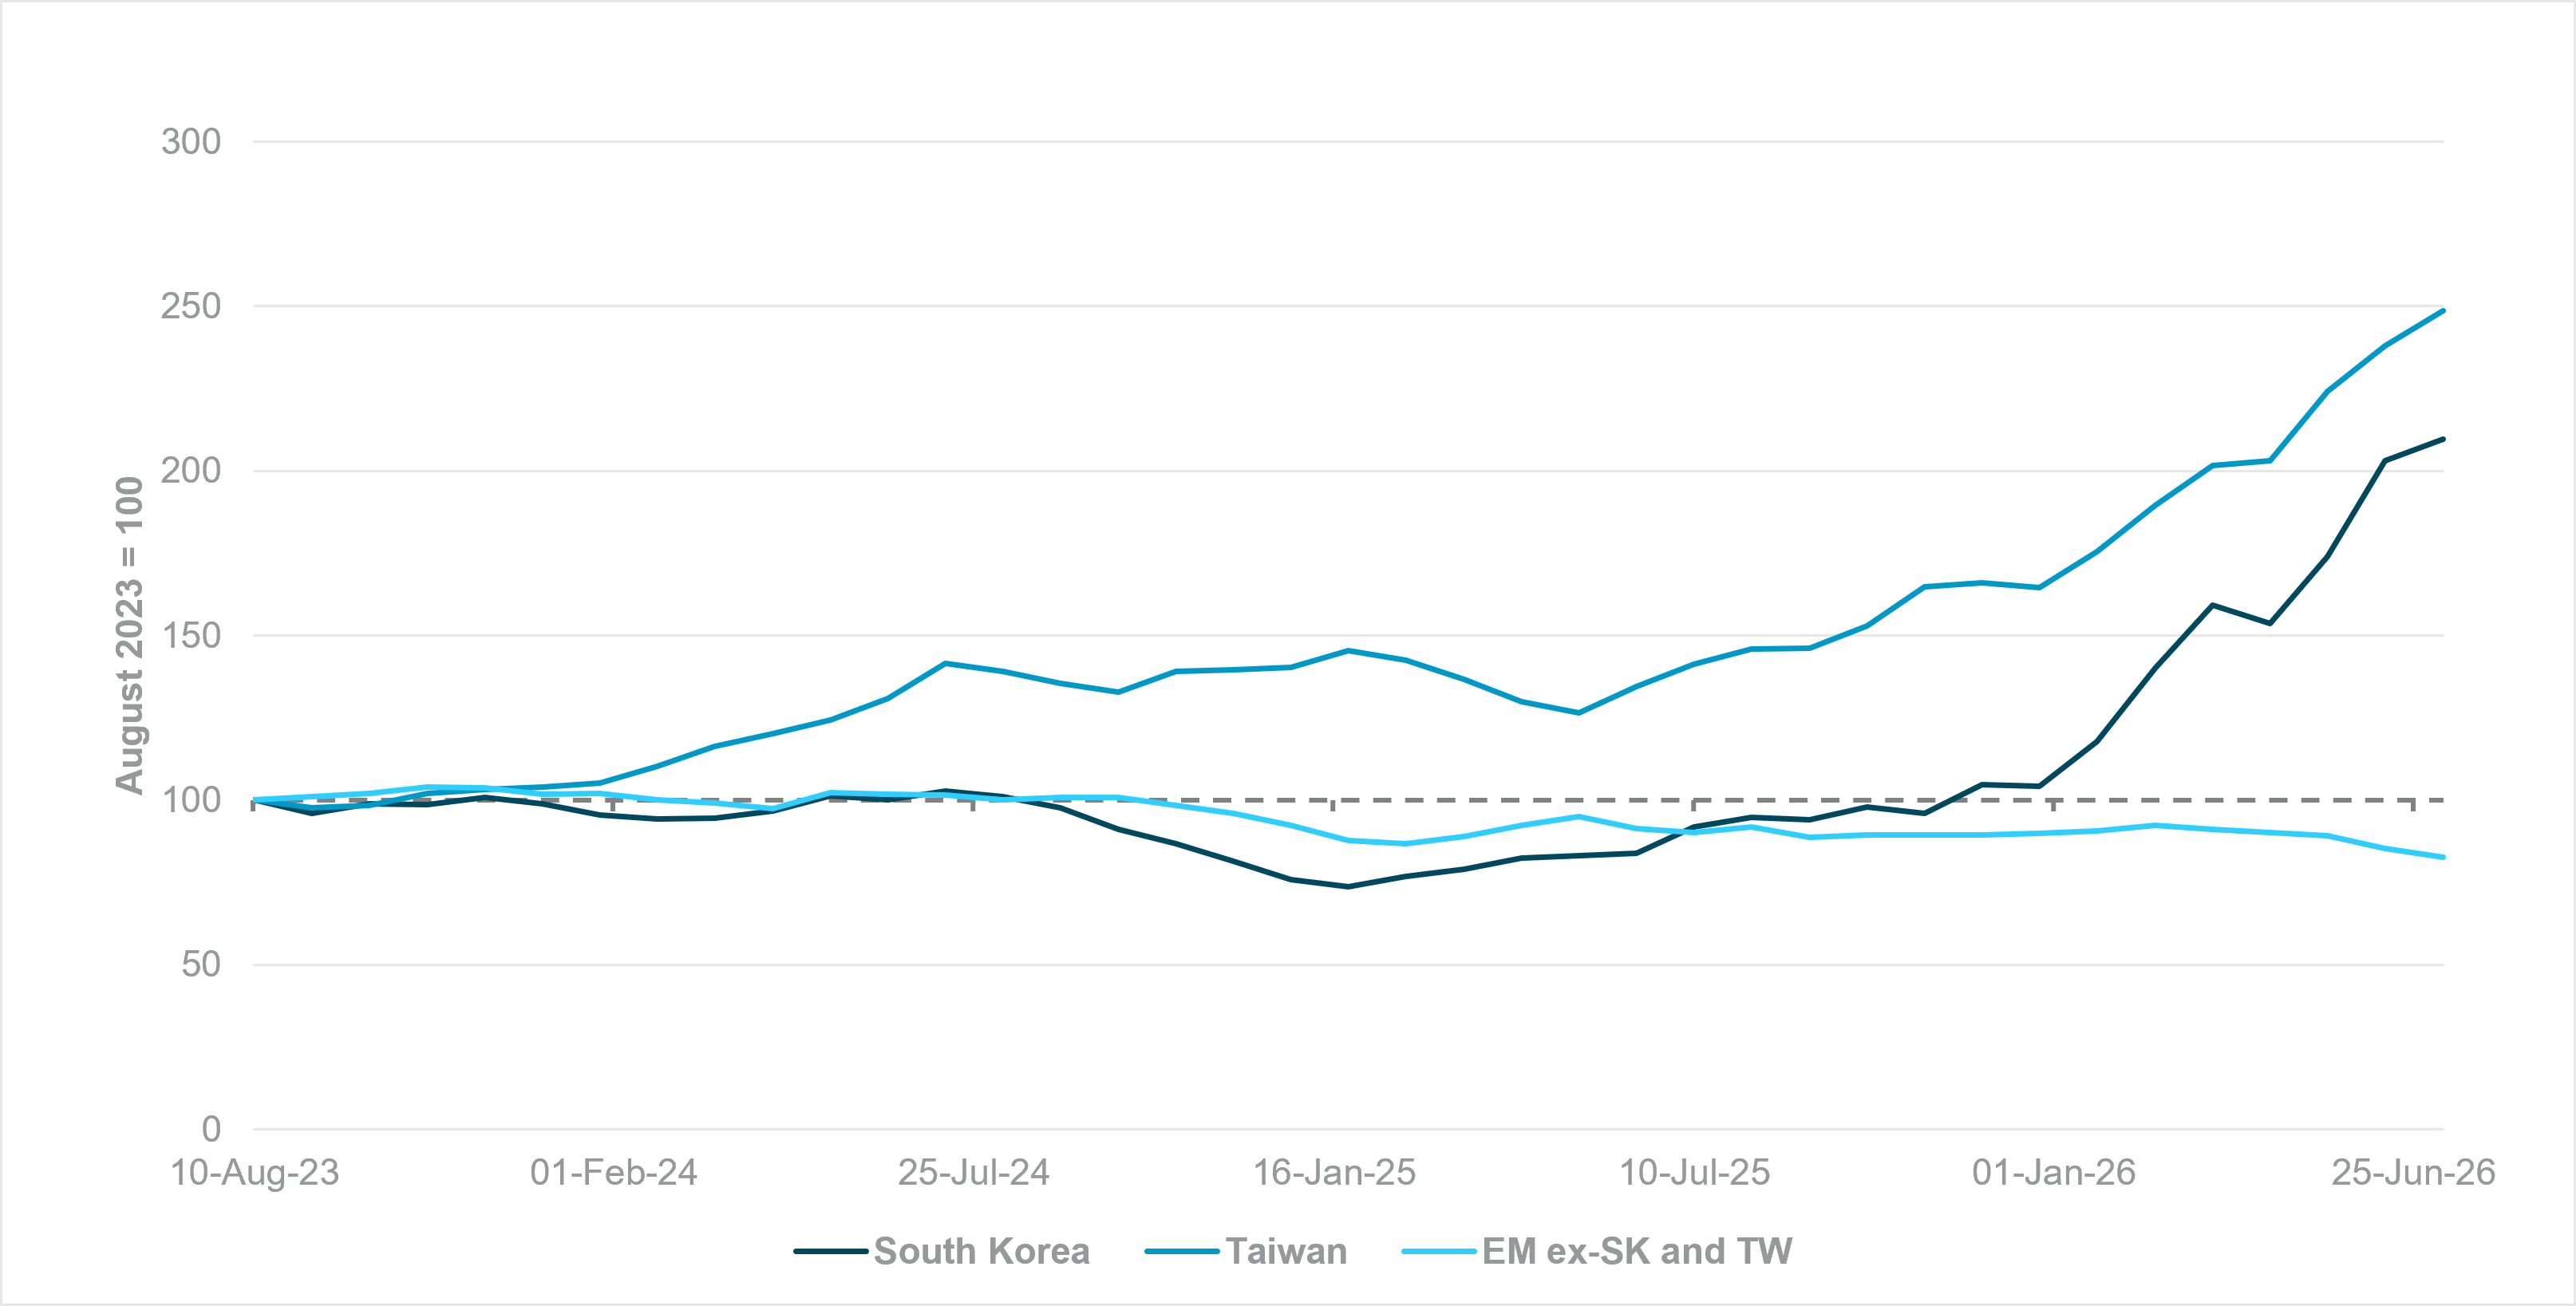
South Korean and Taiwanese equity positioning significantly outpacing EM aggregate
Source: BNY, GPIF
Rotation away from EM chip leaders is becoming a more powerful allocation theme. Semiconductor-related stocks in South Korea fell heavily again overnight, while Taiwanese peers also struggled to benefit from solid earnings. There is now significant scope for convergence in absolute positioning terms. Our positioning data, which measure asset holdings relative to total global equity holdings, show that EM equity allocations are being heavily skewed by South Korea and Taiwan. Excluding these two markets, the EM equity share of global positioning is barely above 4% – the lowest level in three years and down almost a fifth over that period.
China remains the biggest drag on overall EM equity positioning, but the weakness is now broad enough to create asymmetry. China’s better-performing sectors are also closely tied to its own AI efforts, implying that positioning across the rest of the market, including consumer and defensive sectors, is likely even weaker. Data in China and much of EM remain poor, but positioning and valuations already appear to reflect strong disinflation, weak growth and limited earnings momentum. Adding exposure ahead of recovery therefore offers a better risk-reward profile, whether the catalyst comes from cyclical improvement or stimulus. The bottom line is that market positioning implies there is no earnings growth in emerging markets outside chips. That looks too pessimistic if any recovery impetus emerges.
The risk is convergence: Familiar pressure points are now moving synchronously. Energy and geopolitical risks never disappeared, but they were manageable while barrels kept moving and the disinflation story held. AI valuation concerns were also well-known, but easier to ignore at a time of yield moderation and strong earnings momentum. The concern is that these risks are no longer sitting in separate buckets, but are converging into a single risk aversion impulse.
The Strait of Hormuz is the core macro channel: Renewed U.S.-Iran escalation has pushed oil higher, but the bigger issue is how sustained energy pressure will constrain central banks’ ability to react. We do not see a repeat of the March/April shock, but the move is still enough to challenge the benign rates backdrop. If oil pressure persists, the market will have to price in a less comfortable mix of sticky inflation, weaker consumption and reduced policy flexibility.
Japan remains a source of two-way FX volatility: The Reuters report that there is no immediate plan to overhaul GPIF allocations should cool the most aggressive repatriation narrative, but the debate still matters. Even within existing bands, a larger domestic allocation would reinforce the broader home bias question across North Asia’s savings base. The APAC FX status quo remains fragile, but convergence means adjustment is more likely to come through risk reduction than a clean valuation catch-up.
Convergence hedges will matter as the markets await insights into Fed Chair Kevin Warsh’s views and U.S. CPI: Investors may wish to rebuild energy positions selectively where exposure has been cut too far, but avoid chasing a full crisis premium. Duration can be kept light while oil is pushing inflation risk higher, and crowded AI/semiconductor beta can be trimmed where flow and positioning are carrying prices more than earnings. Risk can then be added back if the pressure points break, i.e., oil fades, yields stop rising or chip leadership stabilizes.
U.S.-Iranian tensions escalated after a fifth round of U.S. strikes on Iran triggered fresh retaliation from Tehran and raised fears of a return to full-scale war over the Strait of Hormuz. U.S. Central Command said it had hit dozens of targets to weaken attacks on international shipping, while Iran said it had struck U.S. bases and military facilities across the region. The confrontation has put a fragile ceasefire and a June 17 understanding at risk, while President Trump faces mounting political pressure. Markets reacted quickly, with Brent crude rising, U.S. equity futures falling and the dollar strengthening as concerns grew over energy supply and regional stability. Brent +3.553% to 78.71, WTI +3.515% to 73.92, Omani crude -0.474% to 69.34, Dubai crude -0.038% to 69.21.
JPY fell as Reuters reported that Japan’s state pension fund policy remained unchanged, with no immediate plans to alter the Government Pension Investment Fund’s target asset mix. Instead, officials are considering encouraging the fund to raise domestic investment within existing limits, especially in Japanese financial assets and possibly domestic bonds. The report followed Finance Minister Satsuki Katayama’s comments that helped lift the yen and bonds as markets speculated on large inflows into Japanese markets. After the report, Chief Cabinet Secretary Minoru Kihara stated that the GPIF would “conduct appropriate risk management each fiscal year based on market trends” and make amendments if required. Nikkei -1.92% to 67243, USDJPY +0.328% to 162.21, 10y JGB +4.8bp to 2.791%.
Andy Burnham’s emerging government is considering an expanded budget this autumn, likely in October, that would combine the fiscal statement with a departmental spending review. The move would let the new Labour leader, due to become prime minister on July 20, set tax and spending priorities for the rest of the parliament in one package. Treasury officials are examining the option after early talks in Whitehall, though no decision has been taken and the timetable is tight. Key issues include funding defense, protecting public services and deciding how to allocate already-stretched departmental budgets, especially for unprotected areas such as justice and home affairs. FTSE 100 -0.05% to 10492, GBPUSD -0.135% to 1.3386, 10y gilt +4.3bp to 4.915%.
The Bank of Korea has said the global semiconductor market remains undersupplied and the AI-driven chip super-cycle is likely to continue for some time, pushing back against investor fears that the cycle has already peaked. The BoK said semiconductor demand has surged on AI infrastructure investment, while supply expansion has been slower than in past cycles. It argued this cycle is different because it is being led by custom products such as high-bandwidth memory, and that the market should remain on an expansionary path for a considerable period. The bank also noted uncertainty over the pace, scope and profitability of AI adoption, though major investment banks still expect the semiconductor market to remain robust at least through next year. KOSPI -8.95% to 6807, USDKRW +0.104% to 1500.85, 10y KTB -2.6bp to 4.236%.
S&P Global Ratings has affirmed Indonesia’s BBB long-term foreign-currency issuer rating and kept the outlook stable, easing investor concerns after Moody’s and Fitch turned more cautious on the country earlier this year. S&P said the stable outlook reflects its view that recent deterioration in fiscal and external metrics is temporary, and that Indonesia’s 3% of GDP budget deficit ceiling will remain an important policy anchor. The decision offers some relief for President Prabowo Subianto’s administration as it seeks to rebuild confidence amid weak market sentiment, with Indonesian equities and the rupiah under pressure. The announcement did not provide new economic data, but it signals continued investment-grade status and policy credibility despite governance and reform concerns. JCI +1.916% to 6037.842, USDIDR -0.276% to 18105, 10y IDGB +1.8bp to 7.255%.
Central bank speakers: Fed Governor Christopher Waller speaks at the New York Association for Business Economics; the ECB’s Isabel Schnabel speaks; BoE Chief Economist Huw Pill speaks at the International Finance and Banking Society conference.
U.S. Treasury sells $92bn in 13-week bills and $79bn in 26-week bills.
Mood: Risk sentiment has improved as investors put cash to work, with stronger demand for core sovereign bonds and a further easing in global equity outflows. iFlow Mood improved to -0.121.
FX: Mixed and moderate flows overall. USD attracted the strongest inflows, and JPY the largest outflows. APAC and LatAm were biased toward inflows, while G10 and EMEA remained mixed.
FI: Strong buying in Eurozone government bonds and U.K. gilts, with additional demand for India and China. Selling was concentrated in Thai, Chilean and Polish government bonds, while U.S., Colombian and Mexican bonds also saw outflows.
Equities: India and Türkiye led equity inflows, followed by Thailand and Japan. Selling was concentrated in Colombia, Mexico and Singapore.
“Listen to the technology; find out what it’s telling you.” – Carver Mead, semiconductor pioneer
“Only the paranoid survive.” – Andy Grove, former Intel CEO
Dutch goods exports grew more strongly in May, at 5.5% y/y from 4.6% in April. The increase was driven mainly by higher shipments of petroleum products, while exports of electrical machinery were also up y/y. Goods imports also increased by 5.4% y/y in May, led by petroleum products, machinery and chemical products. Statistics Netherlands also said export conditions were less unfavorable in July than in May, helped by a smaller y/y contraction in German manufacturing output. The report points to a steady improvement in external demand conditions, even though the better export backdrop does not automatically translate into stronger export growth. AEX -0.23% to 1082, EURUSD +0.018% to 1.1418, 10y NGB +2.5bp to 3.179%.
Norwegian industrial production fell 1.0% m/m in May and 1.3% in March-May vs. the previous three months. It was, however, up 0.5% y/y after working-day adjustments. The headline decrease reflected a 2.6% drop in extraction and related services, which carries the largest weight in the index, partially offset by a 0.7% increase in manufacturing. Within manufacturing there were rises for food, beverage and tobacco, machinery and equipment, and basic metals, while shipbuilding fell. Electricity, gas and steam jumped 13.7% m/m, but this category performed weakly over three months and was still down y/y in May. OSE +0.34% to 1939, EURNOK -0.157% to 11.148, 10y NGB +0.6bp to 4.354%.
Türkiye’s balance of payments figures for May showed a current account deficit of $1.459bn, wider than the $1.105bn year-earlier deficit, while the current account excluding gold and energy posted a surplus of $3.626bn. The balance of payments-defined trade deficit narrowed slightly to $4.340bn, compared with $4.782bn in May 2025, as exports fell to $21.918bn and imports to $26.258bn. The services balance remained in surplus at $5.207bn, down from $5.545bn a year earlier, reflecting slightly lower services income and higher services expenses. BI 100 -1.35% to 14127, USDTRY +0.047% to 47.0026, 10y TGB +24bp to 33.9%.
New Zealand’s June services sector returned to expansion, with the BNZ-BusinessNZ Performance of Services Index rising to 50.6 points from 48.0 in May (48.9 in April). This took it back above the 50-point breakeven threshold for the first time since this January. BusinessNZ said the recovery remains tentative rather than broad-based, with growth still concentrated in new orders (53.0) and deliveries (51.2), while activity/sales (49.3), stocks/inventories (49.9) and employment (48.8) remained below 50. The parts of the sector most exposed to discretionary spending, including hospitality and personal services, continued to struggle as households prioritized essentials. BNZ said the improvement, alongside stronger manufacturing data, points to growth gradually normalizing, though cost-of-living pressures are still weighing on consumer confidence and the pace of recovery. NZX 50 -0.45% to 13723, NZDUSD +0.07% to 0.5767, 10y NZGB +2.7bp to 4.613%.
South Korean exports surged 53.9% y/y in the first ten days of July, lifted by strong semiconductor shipments. Outbound shipments totaled $29.8bn in July 1-10, up from $19.3bn a year earlier. This is the highest figure for any ten-day period on record. Imports rose 17.4% y/y to $23.5bn, leaving a trade surplus of $6.4bn. Semiconductor exports nearly tripled to $11.2bn, while automobile exports increased by 5.7% to $1.89bn. Petroleum product and ship exports rose 22.7% and 75.1%, respectively. By destination, shipments to China jumped 88.7% to $7bn and U.S.-bound exports climbed 43.2% to $4.91bn. Cumulative exports for 2026 reached $526.1bn, up 48.6% y/y. KOSPI -8.95% to 6807, USDKRW +0.104% to 1500.85, 10y KTB -2.6bp to 4.236%.
South Korea is planning a record 2027 budget of more than ₩800tn, alongside expected national tax revenue of more than ₩500tn, according to Budget Minister Park Hong-geun. The projected tax haul exceeds the government’s earlier estimate of ₩412tn, indicating stronger-than-expected fiscal room. The authorities said any excess tax revenue will be channeled into a Future Response Fund, which will support youth, future growth engines, regional development and talent. President Lee Jae-myung said earlier excess tax revenue would be boosted by the chip industry boom. The announcement points to a more expansionary fiscal stance in 2027, with spending set at a record level and additional revenue earmarked for strategic investment rather than broad-based tax relief.