Market Movers: Contemplation
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoff Yu
Time to Read: 5 minutes
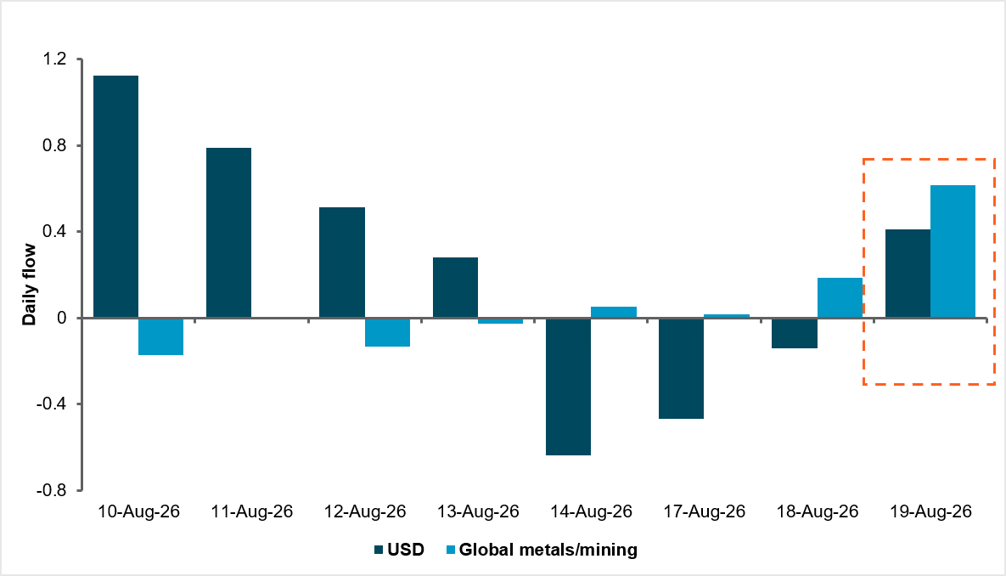
Dollar and metals/mining (gold proxy) better bid after Treasury announcement
Source: BNY
The U.S. Treasury buyback announcement gave the dollar its strongest session in a month, but the move looks more like stabilization than the start of a new bullish trend. Dollar selling had already been heavy, so mean-reversion pressure was building before the announcement. The net purchase score was only around 0.6, modest even by recent standards, and some of the buying may have reflected hedge unwinds as investors reduced underlying U.S. asset exposure. Even so, the improvement helped arrest the dollar’s decline since the July FOMC and leaves it in a better tactical position heading into Jackson Hole. Lower real yields remain the main constraint, however, limiting the case for a sustained recovery.
Gold-related assets delivered the clearer response. Metals and mining flows, used as a proxy for gold exposure, moved decisively back into net purchases after the announcement, matching gold’s rise through $4,500/oz. This follows an earlier post-FOMC surge that faded quickly, suggesting investors remain willing to use gold as protection but are still trading the theme tactically. The lack of follow-through in ZAR and other commodity currencies is telling: investors appear more comfortable owning companies with earnings leverage to higher commodity prices than taking direct FX exposure, where domestic and policy risks remain significant. The announcement therefore produced selective demand rather than a broad real-asset or carry trade, with gold-linked equities the clearest beneficiary and the dollar only partially stabilized.
Bond pause: Wednesday’s Treasury-driven bond rally has largely unwound, but risk appetite is holding rather than breaking. Markets appear content to wait for the next signal, with Jackson Hole next week now the obvious focal point. The buyback announcement bought time, not a new trend, and investors are contemplating whether long-end yields can stabilize without further official support.
Fiscal discomfort: The underlying debt arithmetic remains difficult. U.S. debt has crossed $40tn and lawmakers on both sides acknowledge that the current trajectory is unsustainable, even if there is little agreement on the remedy; “growing” out of the problem has not been successful anywhere in recent years. Such political impasse across the developed world explains why technical intervention can calm bonds without lowering underlying term premia.
Pressure campaign: Washington continues to intensify efforts to isolate Iran economically. Secondary sanctions could reach beyond Tehran; the measures could reopen tensions with allies just as Washington has been trying to stabilize trade and defense relationships elsewhere. The upcoming US-China summit may also prove more challenging.
European balance: Europe continues to offer a cautious recovery signal. Manufacturing was the brighter spot in the latest French and German PMIs, while services remain weaker, and parts of the region are still contracting. The ECB’s latest consumer survey also points to a modest easing in inflation expectations. Industrial improvement without a broad demand surge is close to a Goldilocks outcome for now – enough growth to improve confidence, but not enough to remove the ECB’s need for vigilance.
Ahead today: U.S. PMIs are the main release on an otherwise light calendar. Expect cautious optimism rather than conviction. Intervention is becoming more common, but markets will continue to contemplate the fundamentals and ultimately make up their own minds.
U.S. lawmakers renewed warnings over the country’s fiscal outlook after federal debt crossed $40tn, but the milestone highlighted continued political disagreement over how to respond. Republicans largely emphasized spending restraint, entitlement reform and fiscal commissions, while Democrats focused on tax policy, recent Republican legislation, and the fiscal costs of the Iran conflict. Despite bipartisan concern, Congress remains unable to agree on the mix of spending cuts and revenue increases needed to stabilize debt. Near-term risks are also rising as Republicans consider another reconciliation package worth about $95bn without offsets. Treasury Secretary Scott Bessent argued that stronger growth and tariff revenues can improve the trajectory, suggesting the administration still favors growth-led adjustment over immediate fiscal consolidation. S&P E-Mini +0.26% to 7,682, DXY -0.148% to 98.749, 10y UST 0bp to 4.704%.
The Trump administration is escalating economic pressure on Iran, urging allies and China to help isolate Tehran, while presenting sanctions as the main alternative to renewed large-scale military action. President Donald Trump pledged the “most crushing” economic operation ever imposed on a country, while Bessent said remaining economic ties with Iran could carry severe consequences and indicated more details will follow. Washington is also pressing Beijing, Iran’s largest oil customer, ahead of President Xi Jinping’s planned September visit. Tehran rejected the campaign as “economic terrorism” and said it would fail. The shift comes as military operations remain inconclusive, the Strait of Hormuz stays partially restricted, and Washington continues reinforcing its regional military presence.
ECB Governing Council member Martins Kazaks said the central bank remains well positioned to tighten policy further if needed, with euro area inflation still near 3% and therefore above target. He stressed that September’s decision remains data dependent, despite markets largely pricing another 25bp hike after June’s move. Kazaks pointed to stronger-than-expected economic resilience, solid Q2 growth and low unemployment as arguments supporting further tightening, while acknowledging downside growth risks and uncertainty around energy-driven second-round effects. He also noted that wage growth is gradually slowing and inflation expectations remain anchored around 2%, suggesting ECB credibility remains intact. Kazaks rejected forward guidance, arguing that high uncertainty makes firm policy signals counterproductive. Euro Stoxx 50 +0.42% to 6,449, EURUSD +0.129% to 1.1693, BBG AGG Euro Government High Grade EUR +1bp to 3.51%.
China’s Finance Ministry said it is studying additional fiscal and financial measures to support domestic demand and plans to roll them out in H2 this year. Revised policies took effect on August 1, widening interest-subsidy support for small and micro businesses and consumers, including newly issued working-capital loans and all new credit-card installment spending such as vehicle purchases and home renovations. The existing domestic-demand package supported more than ¥20tn in new lending in the first seven months of this year, up by over ¥880bn, or 4.5% y/y. Authorities said the credit expansion has supported both traditional sectors and emerging industries such as AI and high-end equipment manufacturing. The ministry also signaled a longer-term push for a stronger, more stable and sustainable fiscal system, with more consumption-oriented spending and further fiscal reform. CSI 300 +0.57% to 4,619, USDCNY +0.066% to 6.7206, 10y CGB +0.2bp to 1.696%.
U.S. August preliminary S&P Global Manufacturing PMI is forecast to hold at 53.9. S&P Global Services PMI is forecast to ease to 54.0 vs. 54.6. S&P Global Composite PMI is forecast to ease to 53.9 vs. 54.5.
Canada June Retail Sales is forecast to ease to 0.4% m/m vs. 1.0% m/m. Retail Sales ex Auto is forecast to ease to 0.3% m/m vs. 1.2% m/m.
Mood: iFlow Mood improved slightly to -0.109 as stronger global equity demand offset softer buying of core sovereign bonds.
FX: Global currencies saw moderate, broad-based selling, led by GBP, CNY and JPY. Selective inflows were seen in EUR, USD, COP and SGD.
FI: G10 sovereign bonds saw broad demand, led by Eurozone and Canadian government bonds, followed by U.S. Treasurys. Indonesian government bonds also attracted inflows, while LatAm and Chinese government bonds were sold.
Equities: APAC equities saw broad inflows, led by Taiwan. Flows across G10, EMEA and LatAm were mixed, with notable buying in Colombia vs. selling in Canada and Europe.
“Nowhere can man find a quieter or more untroubled retreat than in his own soul.” – Marcus Aurelius
“I love a broad margin to my life.” – Henry David Thoreau
Eurozone’s flash Composite PMI for August rose to 52.1 from 52.0 in July, marking a nine-month high and a second consecutive month of private sector expansion. Manufacturing strengthened further, with headline PMI rising to 52.8 from 51.9 and output reaching 53.4, its strongest level in 54 months. Services growth was unchanged at 51.7. New orders increased at the fastest pace in 40 months, while export orders expanded for the first time in four and a half years. Employment also rose for the first time in 2026, with manufacturing job losses ending after 38 months. Price pressures eased, although input costs remained elevated, while business confidence softened to a three-month low. Euro Stoxx 50 +0.42% to 6,449, EURUSD +0.129% to 1.1693, BBG AGG Euro Government High Grade EUR +1bp to 3.51%.
Germany’s flash Composite PMI for August edged down to 51.0 from 51.3 in July, signaling continued but modest private sector growth. Manufacturing remained the clear driver, with the headline PMI rising to 54.1 from 52.2 and the output index jumping to 56.7 from 54.7, its strongest level in more than four years. Services weakened further, with activity falling to 48.5 from 49.8. New business improved for a second month, led by manufacturing orders and exports, while employment stabilized after 26 consecutive months of decline. Business expectations also strengthened to their highest level since February. Price pressures eased slightly, with output charge inflation slowing to its weakest pace since March. DAX +0.22% to 26,041, EURUSD +0.129% to 1.1693, 10y Bund -0.6bp to 3.253%.
France’s flash Composite PMI for August fell to 48.8 from 49.4 in July, signaling a slightly faster contraction in private sector activity. The weakness was concentrated in services, where the activity index dropped to 48.4 from 49.6, while manufacturing improved materially, with headline PMI rising to 51.5 from 49.8 and output climbing to 50.7 from 48.5. New orders declined for a ninth consecutive month, and export demand weakened further, while employment fell for a fourth month. Backlogs were reduced at the fastest pace in 18 months. Cost pressures eased overall as manufacturing input inflation fell, although services costs accelerated. Business confidence also deteriorated, reaching its weakest level since May. CAC 40 +0.12% to 8,463, EURUSD +0.129% to 1.1693, 10y OAT -1.3bp to 4.11%.
U.K. retail sales volumes for July fell 0.5% m/m, reversing part of June’s revised 0.7% gain, but were still 1.6% higher y/y. The three-month trend remained firmer, with volumes up 1.1% vs. the three months to April and 3.0% y/y. July weakness was concentrated in non-food stores and non-store retailing, where earlier promotional activity brought demand forward into June, while hot weather also reduced clothing footfall and household goods demand. Food store volumes rose, supported by warm weather and the World Cup, while fuel sales also increased but remained below February levels. Online sales values fell 3.9% m/m, reducing the online share of total sales to 28.3%.FTSE 100 +0.31% to 10,782, GBPUSD +0.066% to 1.364, 10y gilt -0.3bp to 5.064%.
U.K. flash Composite PMI for August rose to 52.5 from 52.2 in July, marking a four-month high and the fastest private sector growth since April. Services led the improvement, with activity rising to 52.8 from 52.1, a six-month high, while manufacturing softened, with the headline PMI falling to 51.5 from 51.9 and output easing to 51.2. New business increased at the fastest pace since February, supported by stronger domestic spending, although export demand remained weak. Employment continued to fall, but at the slowest pace since October 2025. Inflation pressures intensified, with input costs and output prices both accelerating, driven by fuel, transport, wages and other operating expenses. Business confidence improved to its highest since February.
U.K. public sector finances for July 2026 showed borrowing of £1.8bn, up £0.7bn from a year earlier and above the Office for Budget Responsibility forecast by £2.3bn. The monthly current budget moved to a surplus of £3.1bn, but higher spending outpaced receipts overall, with self-assessed income tax supporting revenue. In the financial year to July 2026, borrowing totaled £56.7bn, down £6.0bn y/y but still above forecast. Public sector net debt stood at £2,984.9bn, or 94.1% of GDP, slightly lower than a year earlier, while net financial liabilities were 83.7% of GDP.
Japan’s July CPI rose 1.9% y/y, accelerating from 1.6% in June. The core index ex fresh food increased 1.8% y/y, up from 1.6%, while the core-core measure excluding fresh food and energy rose 1.9% y/y, up from 1.7%. On a seasonally adjusted basis, the headline index rose 0.4% m/m, after 0.3% in June; core CPI rose 0.3% m/m, and core-core also gained 0.3% m/m. Inflation was led by food, especially confectionery, prepared foods, seafood, fresh vegetables, meat, beverages and dining out. Transportation and communication also contributed, with higher vehicle-related costs and mobile phone fees. Education was a drag, driven by lower private high school tuition. Energy remained slightly negative y/y, with declines in electricity, gas and gasoline partly offset by higher LPG and kerosene. Nikkei -0.3% to 66,016, USDJPY -0.202% to 158.79, 10y JGB +2.9bp to 2.889%.
Japan’s August 2026 Flash PMI signaled the fastest expansion in private-sector activity in six months, with the composite output index rising to 53.4 from 52.7 in July. Services activity improved to 52.3 from 51.2, while manufacturing stayed strong at 55.1 from 54.5; manufacturing output eased slightly to 56.1 from 56.3. Growth was supported by a steeper rise in new orders, with manufacturing export orders accelerating to the strongest pace since early 2018, though services export business fell. Employment rose for a 35th straight month, helping ease capacity pressures. Cost inflation cooled from June’s peak but remained high, driven by raw materials, fuel, energy, staffing costs and a weak yen, keeping selling prices near record highs. Business confidence improved to its best since February.
Australia’s August 2026 Flash PMI signaled a slower but still expanding private sector, with the Composite Output Index at 52.5 (July: 53.2). Services remained the main growth engine, while manufacturing output slipped back into contraction at 49.7 (July: 50.3). New orders rose for a second month, with broad-based gains and the first improvement in export performance since March, helped by firmer demand for manufactured goods. Employment continued to rise, though at the slowest pace in three months. Business confidence improved to a six-month high but remained subdued. The cost environment worsened as input price inflation edged up, led by fuel, freight, commodities and raw materials; tariffs were also cited. However, firms eased selling-price increases, with charge inflation the slowest since early 2026. ASX +0.28% to 5,811, AUDUSD +0.38% to 0.715, 10y ACGB +5.1bp to 5.058%.
New Zealand’s overseas merchandise trade balance was a $1.9bn deficit in July 2026. Exports declined for the second straight month at -5.6% m/m. Goods exports rose 14% y/y to $7.4bn (up $881mn from July 2025), while goods imports jumped 28% y/y to $9.3bn (up $2.1bn). Export growth was led by milk powder, butter and cheese ($1.9bn, up 6.4%), with notable gains in cheese, fresh milk and cream, and milk powder. By destination, exports rose to the U.S. (29.5% y/y), China (14.4% y/y), Australia (6.7% y/y) and the EU (9.6% y/y), while Japan was broadly flat. Import strength was broad-based, with sizable increases from China (21.2% y/y), the EU (18.5% y/y), Australia (12.9% y/y) and South Korea, led by vehicles, parts and accessories, electrical and mechanical machinery, and petroleum products. NZX 50 +0.38% to 13,973, NZDUSD +0.202% to 0.5968, 10y NZGB +6.1bp to 4.745%.
South Korea’s exports jumped 56% y/y in the first 20 days of August, driven by record-high semiconductor shipments. Outbound shipments reached $55.2bn, the highest for any August 1–20 period, while imports rose 19% y/y to $41.2bn, leaving a trade surplus of $14bn. Daily average exports climbed 61.5% y/y to $3.94bn. Chip exports nearly tripled to $26bn and accounted for 47.2% of total exports, up 22.5 percentage points y/y. Petroleum product exports increased 56.4% to $4.23bn, and steel exports rose 9.7% to $2.39bn, while automobile exports fell 45.1% to $1.52bn. By destination, exports to China more than doubled to $15.26bn and shipments to the U.S. rose 59.4% to $7.97bn. KOSPI +0.88% to 6,913, USDKRW +0.676% to 1384.7, 10y KTB -1.3bp to 4.322%.
South Korea’s PPI signaled the peak of inflation pressure, with prices falling for the first time in 11 months. July 2026 PPI fell 0.4% m/m, easing from 0.0% in June, while still rising 7.7% y/y. Downward pressure came from manufacturing products (-0.5% m/m), electric power, gas, water and waste (-0.6%), and services (-0.4%). Agricultural, forestry and marine products rose 1.5% m/m, helped by marine foods and livestock products, though agricultural foods also increased. On a y/y basis, manufacturing remained the main source of inflation at 12.2%, with services at 4.0% and agricultural, forestry and marine products at 0.7%. The Domestic Supply Price Index also declined 1.8% m/m after 0.6% in June, but was still up 10.2% y/y. The Total Output Price Index slipped 0.2% m/m after 0.3% in June, while rising 16.6% y/y.
India’s August flash PMI signaled a modestly stronger expansion in the private sector, with the Composite Output Index rising to 54.6 from 54.3 in July. Services led the improvement, as the Services PMI Business Activity Index climbed to 54.5 from 53.3, offsetting a softer manufacturing backdrop; the Manufacturing Output Index eased to 54.9 from 56.4, and the Manufacturing PMI slipped to 52.9 from 53.5. New orders rose at a subdued pace, while export orders increased solidly, supported by demand from the U.S., Germany, China, Singapore and Japan. Employment growth strengthened to a pace tied for the fastest since June 2025, though manufacturing payrolls fell. Input cost inflation softened, but firms lifted selling prices at the fastest rate since April, reflecting efforts to pass through costs. Business confidence improved slightly for the year ahead. SENSEX +0.07% to 77,593, USDINR -0.029% to 95.74, 10y INGB -0.7bp to 6.864%.