Market Movers: Confrontation
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoff Yu
Time to Read: 5 minutes
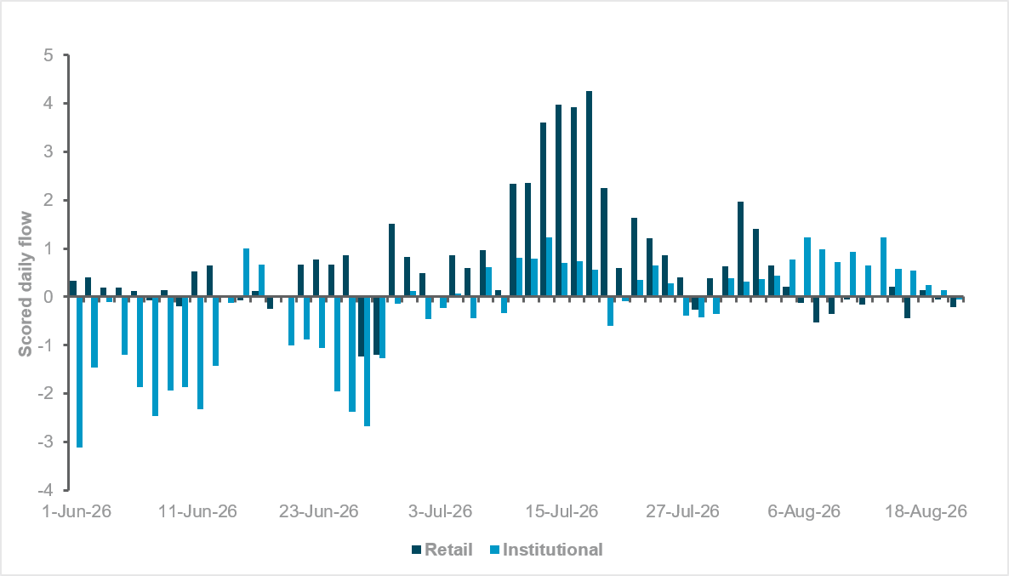
Institutional and retail interest in EM APAC faltering
Source: BNY
Asian equity markets had a very difficult session overnight amid escalating fears over financing costs of the AI buildout, with limited visibility on return profiles. Ongoing weakness in Chinese figures is not helping, especially given the lack of tangible measures to boost growth, while other tail risks such as the impact of secondary sanctions relating to trade with Iran could derail the U.S.–China trade détente.
iFlow also notes that there are some worrying changes taking place in the structure of flow. Throughout the summer months, as volatility in Asian semiconductor stocks surged, we highlighted that retail investors were still trying to add to exposures, while institutional investors were on the sidelines initially, before ramping up participation through August. Toward month-end, either due to rebalancing or other factors, both cohorts are showing signs of exhaustion and exercising caution with flows. The lack of interest by long-term funds will be a particular worry for the region. Poor performance, attractive valuations and clearer positioning compared to a quarter ago point to a more demanding case for returns.
Our data continue to suggest that overall Asia-Pacific exposures, especially outside the semiconductor space, are extremely light. Doubts over the region’s ability to grow independently of the U.S. remain an impediment to major improvement in weightings.
Economic isolation: The U.S. is widening its economic confrontation with Iran, and the spillovers could reach far beyond Tehran. Treasury Secretary Scott Bessent is expected to detail new measures today aimed at deepening Iran’s financial isolation. Depending on their scope, those steps could affect companies and trading partners across Europe and Asia. China is the clearest pressure point, but broader restrictions on finance, shipping and trade could also strain relations with allies.
Trade confrontation: Canada is choosing resistance rather than accommodation in its dispute with the U.S. Prime Minister Mark Carney has described the relationship as a trade war, raising the risk of disruption across one of the world’s most important bilateral economic relationships. The larger threat is not simply tariffs but damage to deeply integrated energy, manufacturing and investment flows.
AI reckoning: Asia is confronting the cost of staying competitive in AI. Alibaba’s record HK$80bn follow-on share sale to fund AI expansion sent its shares lower and sharpened questions about dilution, capital intensity and eventual returns. The challenge is global: as models commoditize and competitive advantages narrow, companies must justify ever-larger investment simply to remain in the race.
Markets push back: Official efforts to influence currency and bond-market conditions remain under scrutiny. Yen intervention and Treasury buybacks send signals of intent, but markets continue to test whether those measures are consistent with underlying fundamentals. Bond-market sentiment is somewhat steadier today even as equities struggle.
Ahead today: The calendar is light, leaving policy signals rather than data in control of sentiment. The Chicago Fed National Activity Index is the only notable U.S. release, while markets will focus on Bessent’s Iran announcement and positioning ahead of Jackson Hole. The immediate hope is that volatility remains contained until policymakers gather in Wyoming on Thursday.
Treasury Secretary Bessent will announce a new Iran sanctions package today, describing it as an unprecedented campaign of coordinated economic isolation. The Trump administration is pressing allies and other countries to halt business with Tehran and has threatened severe financial penalties against governments or firms that help Iran evade restrictions. Washington is framing economic pressure as the main tool for forcing Tehran to change course without immediately returning to large-scale military operations. Iran’s Islamic Revolutionary Guard Corps dismissed the threat, arguing that the country can continue building economic ties despite sanctions and portraying the U.S. strategy as evidence of military failure. The key uncertainty is whether additional sanctions can materially constrain Iran, which already operates under extensive restrictions and retains significant regional leverage. Brent -1.124% to 93.33, WTI -1.643% to 85.63, Omani Crude +1.379% to 100.76, Dubai Crude +0.845% to 90.274.
Piero Cipollone of the European Central Bank (ECB) said monetary policy should remain carefully calibrated, warning that excessive tightening in response to an energy-driven supply shock could unnecessarily weaken growth. He argued that higher rates designed to force inflation quickly back to target risk amplifying the economic damage already caused by elevated oil prices. The euro area has so far proved more resilient than expected, with Q2 2026 growth of 0.4%, while inflation remains elevated at 2.9%. Cipollone said current developments remain broadly consistent with the ECB’s June 2026 baseline projections and do not resemble the more adverse scenarios considered previously. He also rejected the idea that the euro area is moving into stagflation, suggesting caution over additional tightening despite persistent inflation. Euro Stoxx 50 -0.22% to 6,448, EURUSD -0.146% to 1.1662, BBG AGG Euro Government High Grade EUR 0bp to 3.503%.
Chinese technology stocks sold off sharply as large-scale equity fundraising plans revived concerns over dilution, capital supply and the rising cost of funding AI investment. The Hang Seng Tech Index fell as much as 4%, while the mainland STAR 50 dropped 3.8% to a three-week low after major internet and semiconductor groups moved to raise fresh capital. The weakness added to broader global tech pressure ahead of key U.S. earnings and renewed doubts about the durability of the AI trade. Investors are increasingly focused on whether heavy AI spending can generate sufficient returns before further equity or debt issuance is required. The broader concern is that repeated fundraising could weigh on valuations across China’s technology sector even if the long-term investment case remains intact. CSI 300 -1.21% to 4,563, USDCNY +0.035% to 6.7235, 10y CGB -1.8bp to 1.679%.
The U.S. and Canada failed to reach a trade deal after talks collapsed, prompting 50% U.S. tariffs on some Canadian products to take effect on Saturday. Prime Minister Mark Carney said Canada will retaliate “dollar for dollar,” with new tariffs starting September 8. Carney said the U.S. made last-minute changes that were “unfair” and “uneconomic,” and argued Canada had been prepared to drop its remaining retaliatory tariffs on steel, aluminum and autos if Washington lowered its own. The measures will hit sectors including steel, dairy, agricultural equipment, and pulp and paper. The escalation affects roughly $20bn of Canadian exports and risks higher costs, supply-chain disruption, and further strain on the bilateral relationship. There are no new planned talks, according to U.S. Trade Representative Jamieson Greer. TSX 60 Future +0.07% to 2,147, USDCAD +0.589% to 1.3841, 10y CGB +0.7bp to 3.763%.
The Chicago Fed National Activity Index for July is forecast to ease to -0.1 vs. -0.0.
U.S. Treasury sells $92bn in 13-week bills and $79bn in 26-week bills.
Mood: iFlow Mood remained negative as buying of both core sovereign bonds and global equities moderated.
FX: Flows were mixed and moderate. EUR, USD and COP attracted inflows, while AUD, JPY, MXN and CNY were sold. EUR-scored holdings rose to their highest overheld level since August 2023, while JPY positioning moved further into underheld territory.
Fixed Income: Demand focused on Eurozone, Canadian and Indonesian government bonds, alongside U.S. Treasurys. Outflows were broad elsewhere, led by Chinese and Mexican government bonds.
Equities: Flows were mixed, with selling in Canada and Europe against buying in Colombia and Turkey.
“Let us never negotiate out of fear. But let us never fear to negotiate.” – John F. Kennedy
“If you want to make peace with your enemy, you have to work with your enemy. Then he becomes your partner.” – Nelson Mandela
Poland’s retail sales for July rose 3.9% y/y at constant prices and 2.2% m/m, while January–July sales increased 3.7% y/y. Seasonally adjusted sales were 4.3% higher than a year earlier but fell 0.3% from June. Growth was led by pharmaceuticals, cosmetics and orthopedic equipment, up 10.8% y/y, followed by other retail sales at 9.2%, furniture and household appliances at 8.8%, and motor vehicles at 8.1%. Food, beverages and tobacco rose 1.5%, while clothing and footwear fell 1.7%. Online retail sales increased 9.0% y/y, lifting their share of total sales to 8.9% from 8.6% a year earlier. WIG -0.29% to 151,165, EURPLN +0.098% to 4.3166, 10y PGB -2.9bp to 5.894%.
New Zealand retail activity fell in the June 2026 quarter, with total retail sales volumes down 0.5% q/q, or $138mn, from the March 2026 quarter. Eight of the 15 retail industries recorded lower volumes. The biggest declines were in fuel retailing (-13.0%), motor vehicle and parts retailing (-2.3%), accommodation (-8.0%), and food and beverage services (-2.8%), while electrical and electronic goods retailing rose 9.2%. Stats NZ said higher fuel prices lifted fuel retailing sales values, but after stripping out price effects, fuel retailing had the sharpest volume decline. The release points to softer underlying consumer demand, despite nominal spending being supported by higher fuel prices. NZX 50 -0.65% to 13,882, NZDUSD -0.067% to 0.5974, 10y NZGB -1.9bp to 4.726%.
Singapore’s July CPI data showed headline inflation rising to 2.2% y/y from 1.9% in June, while core inflation rose to 2.0% y/y from 1.6%, the fastest since October 2024. On a monthly basis, consumer prices fell 0.2% m/m after being unchanged previously, while the MAS Core Inflation measure rose 0.3% m/m. The pickup in core inflation was driven mainly by transport, which accelerated to 7.9% y/y from 7.5%, and food, which rose 2.2% y/y from 2.1%. Excluding accommodation, prices increased 2.8% y/y, up from 2.4%. Overall, both MAS Core Inflation and CPI-All Items inflation are projected to average 1.5–2.5% for the whole of 2026. Core inflation is expected to remain elevated into 2027 before moderating more discernibly from around mid-2027, alongside the expected easing in global energy prices. At this juncture, the risks to the inflation outlook remain tilted to the upside. STI -0.15% to 5,680, USDSGD -0.024% to 1.2697, 10y SGB -0.6bp to 2.36%.