Market Movers: Bounces and shocks
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Bob Savage
Time to Read: 7 minutes
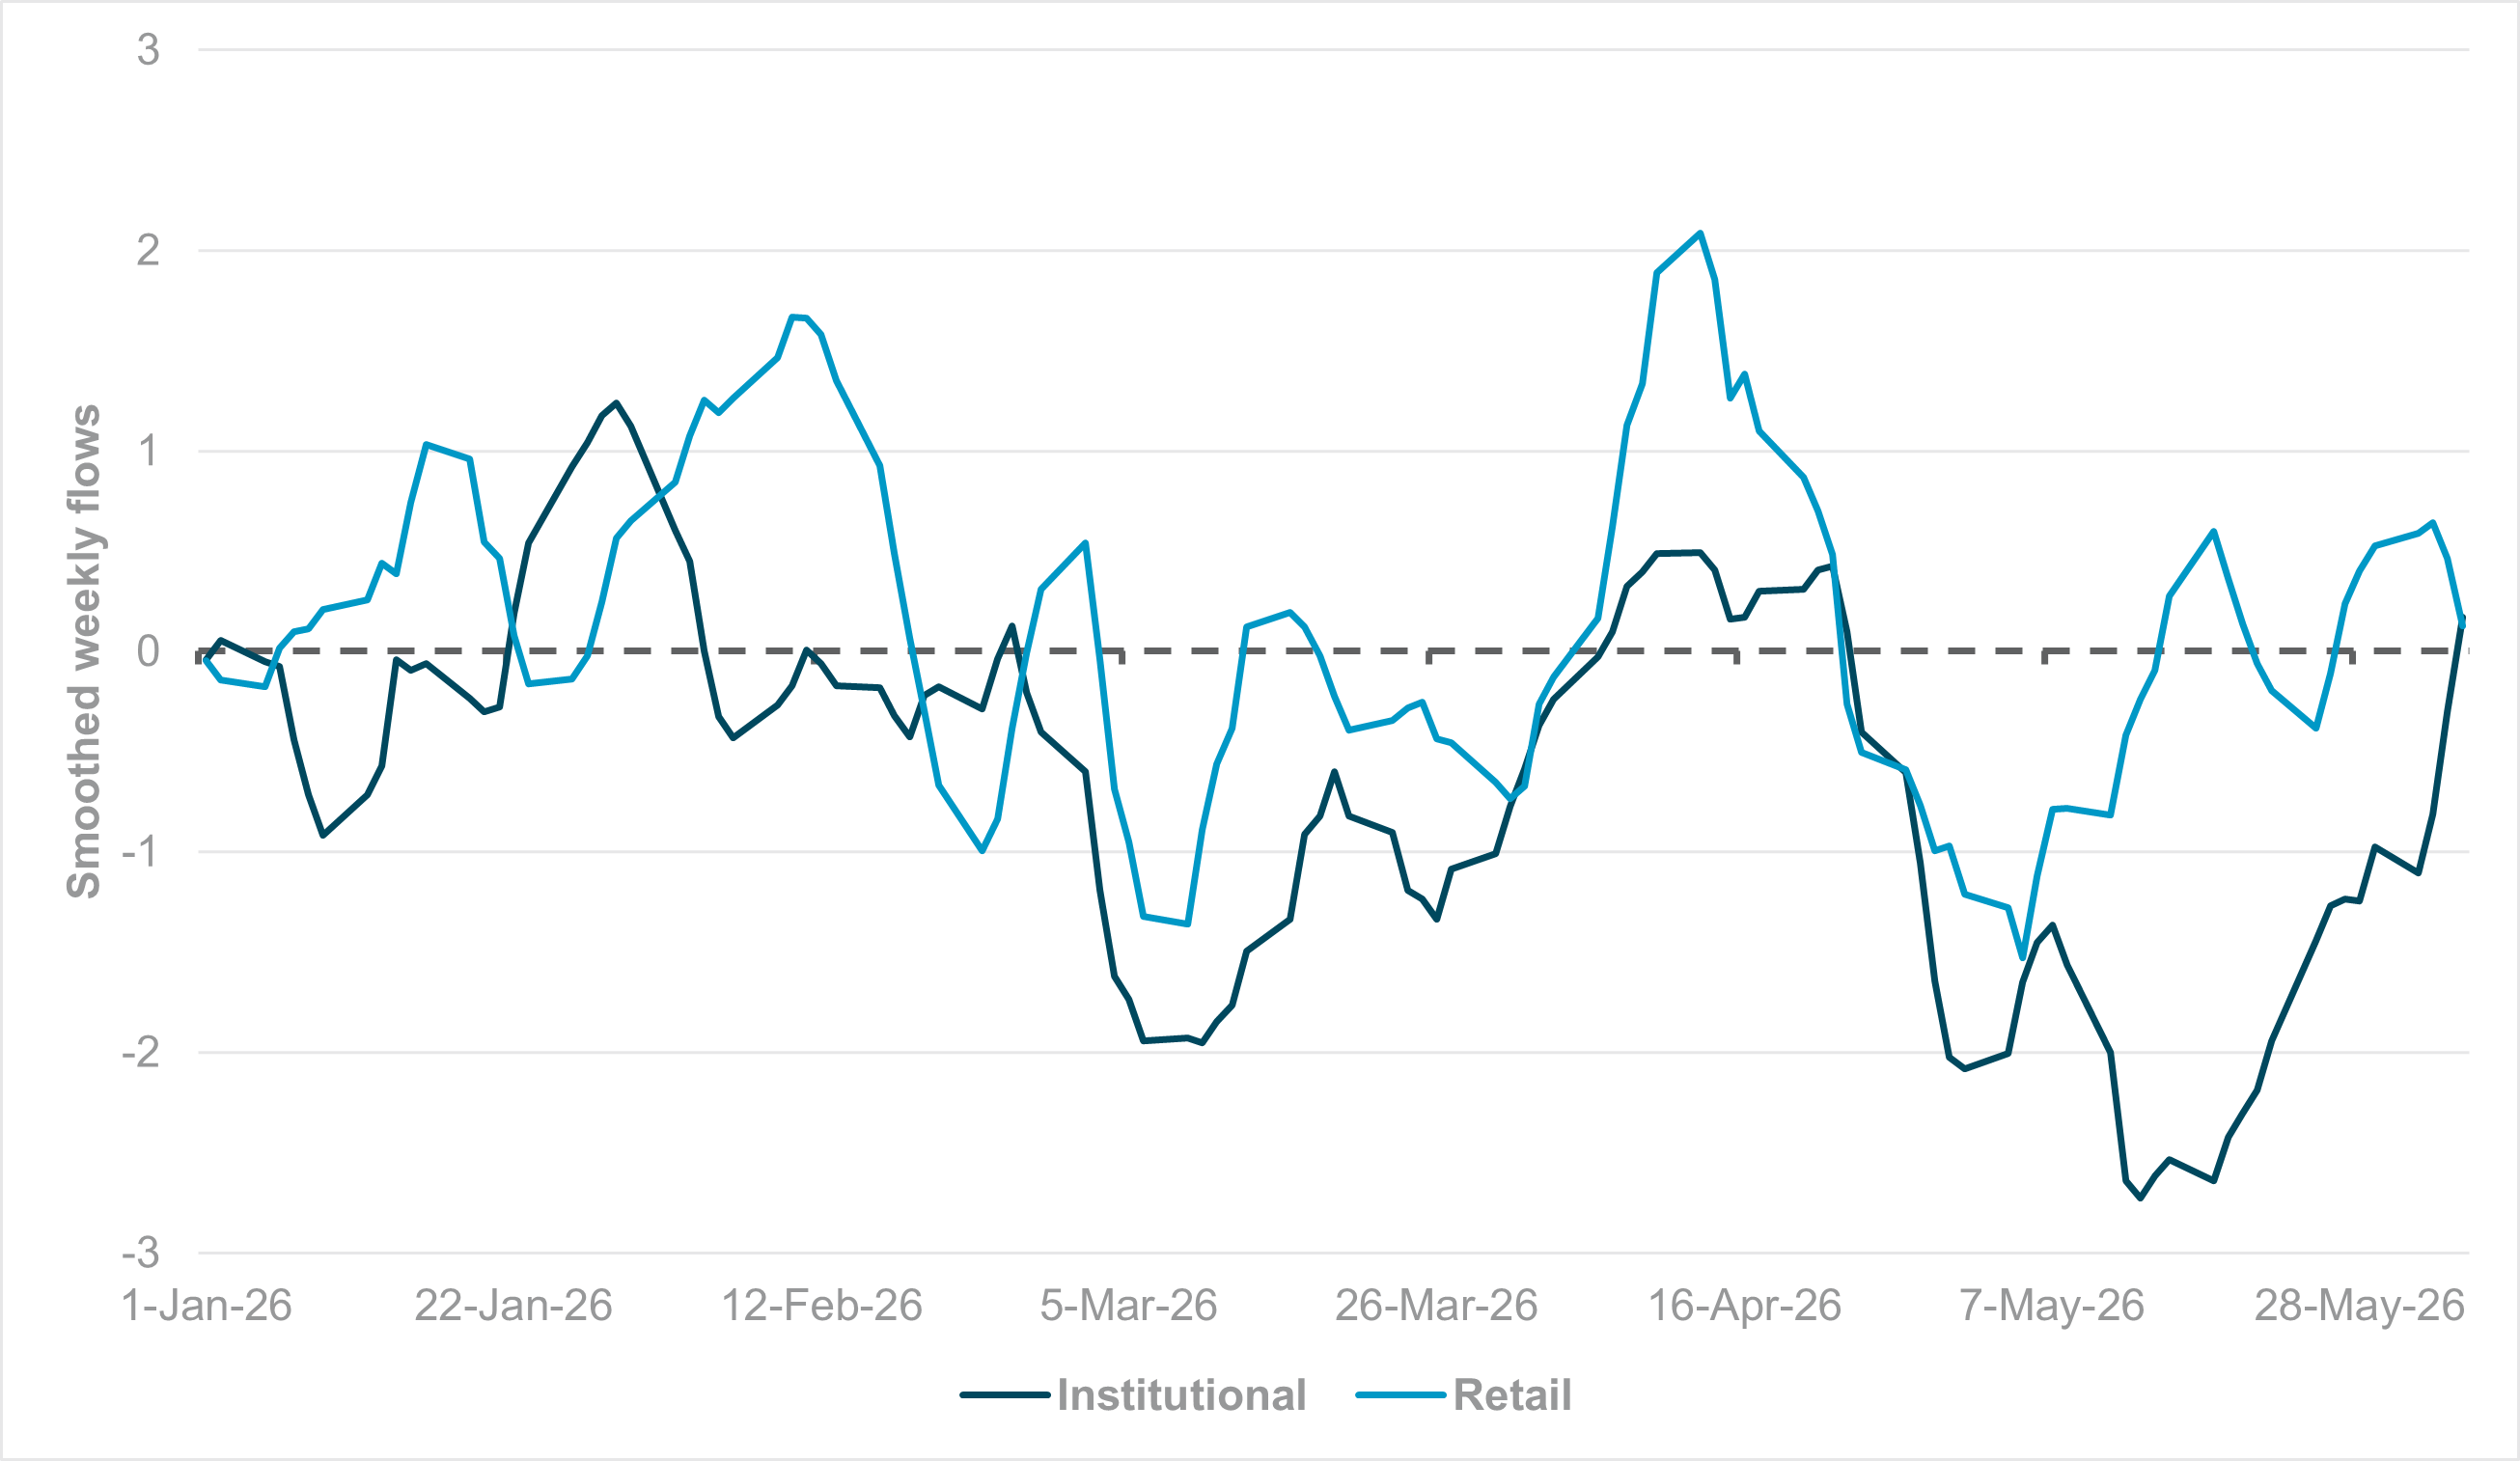
Retail vs. institutional flows into EM APAC semiconductor industry group
Source: BNY
The composition of the market’s reaction to Friday’s strong payrolls report is a stark reminder of the positioning risks associated with the AI/semiconductor theme and the broader tech sector. With conflict risks continuing to linger, adding to concerns over global inflation, we expect asset classes with high beta to these tech themes to face challenges in the near term. As overnight price action demonstrated, South Korea and Taiwan remain at the forefront of correction risks.
Equity flows remain the greatest challenge, and we continue to highlight the significant divergence between institutional and retail activity in South Korea. The picture is quite different in Taiwan, where institutional flows last week reached their strongest sessions of the year. Retail and institutional flows have been much better aligned, although retail momentum softened recently after the group played a dominant role in April. Combined flows into these two markets should account for the bulk of flows into EM APAC’s semiconductor industry group. At the aggregate level, the divergence between institutional and retail activity is somewhat more pronounced, though it still sits between the extremes seen in South Korea and Taiwan. On balance, retail flows have been stronger since May but appear to have turned earlier toward the end of last week, perhaps in anticipation of a more challenging performance environment. Even so, retail holdings are likely still well above recent averages and will be the primary driver of any liquidation.
The bellicose weekend headlines leave Monday markets searching for peace. Between higher bond yields and higher oil prices, APAC markets saw cross-asset volatility and risk-off trading, all of which continue into EMEA but not in U.S. futures, with tech shares up after Friday’s 4% drop. The key question is about the bounce and its sustainability. The FX markets saw KRW gain 1% after government plans to support the currency even as its KOSPI stock index fell 8%. While in other EM FX, MYR, IDR, HUF and INR all suffered, suggesting yields are not enough to offset risks. Overall, the USD is bid at two-month highs, holding steady with focus on JPY and intervention risk.
Bottom Line: The week ahead has U.S. CPI, ECB and other central bank decisions, along with bond supply. The risk of rates dominating over oil was the key driver for risk-off in the U.S. on Friday. The weekend escalation of the war with missiles exchanged between Iran and Israel won’t help settle markets for a larger “buy-the-dip” bounce back. Rather, the probability of a larger VAR shock should be watched. The ability for the U.S. markets to take solace in peace hopes isn’t sufficient. Investors will need to see signals of market resilience across the globe. The downside for today revolves around the breakout of more conflict and what it means for oil, the USD and the summer mood for U.S. consumers.
Israel and Iran exchanged fresh missile attacks despite U.S. efforts to revive diplomacy and secure a new 60-day truce. Iran launched additional strikes against Israel, which responded with attacks on military targets in western and central Iran and a petrochemical facility in Mahshahr. The escalation comes after Trump urged both sides to avoid retaliation and allow negotiations to proceed, warning that renewed fighting could undermine peace efforts. The flare up has raised concerns about broader regional instability, with Saudi Arabia briefly issuing a missile alert near a base hosting U.S. forces. Financial markets reacted sharply, with Brent crude oil rising above $97/bbl and the U.S. dollar strengthening as investors sought safe-haven assets. The renewed conflict has intensified concerns over energy supply disruptions and a potential increase in global inflation pressures. Brent +4.394% to 97.18, WTI +3.999% to 94.16, Omani Crude -3.212% to 90.4, Dubai Crude -2.876% to 90.464
South Korean top economic and financial policymakers held an emergency meeting, and vowed stern action against speculative and market-disruptive foreign exchange activities as the won weakens. Finance Minister Koo Yun-cheol, BOK Governor Shin Hyun-song, FSC Chairman Lee Eog-weon, and FSS Governor Lee Chan-jin said they would not tolerate excessive volatility or one-sided market concentration. Authorities plan joint inspections by the Bank of Korea and Financial Supervisory Service to check for speculative trading, price manipulation and abnormal order patterns. The warning comes as the won fell to its weakest level since March 2009, driven by heavy foreign investor selling and fading hopes for a diplomatic solution to the Middle East conflict. Officials said they will monitor the FX market around the clock and act swiftly if volatility worsens. KOSPI -8.23% to 7,489, USDKRW +1.53% to 1536.05, 10y KTB +2.5bp to 4.252%
Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria and Oman said they will implement a combined oil production hike of 188,000 b/d in July 2026. The group said the move reflects a cautious approach to supporting market stability amid evolving market conditions, while retaining full flexibility to increase, pause or reverse the phased withdrawal of cuts, including those announced in November 2023. They also reaffirmed commitment to full conformity with the Declaration of Cooperation and said any overproduction since January 2024 will be fully compensated. The compensation period has been extended to end-December 2026. The seven countries will continue holding monthly meetings to assess market conditions, conformity and compensation, with the next meeting scheduled for July 5. Brent +4.663% to 97.43, WTI +4.396% to 94.52, Omani Crude -3.212% to 90.4, Dubai Crude -2.876% to 90.464, HH Natural Gas -1.642% to 3.176, Dutch TTF Natural Gas +5.019% to 50.93.
Philippines financial regulators warned that major conglomerates face sizeable foreign exchange and refinancing risks as about ₱1.6tn, or $26bn, of debt matures over the next three years. The 2025 Financial Stability Report said these maturities are concentrated between 2027 and 2029 and amount to nearly a quarter of total conglomerate debt, with U.S. dollar debt averaging 37.6% of obligations over the next five years. The inter-agency report, prepared with the Bangko Sentral ng Pilipinas and the Department of Finance, said firms have met refinancing needs so far, but weak peso conditions, elevated oil prices, property risks, unsecured consumer lending, cyber threats and geopolitical tensions warrant close monitoring. PSEi -0.99% to 5,879, USDPHP +0.371% to 61.707, 10y PHGB -4.1bp to 7.4%.
Peru’s presidential runoff on Sunday was too close to call, with preliminary results showing a statistical tie between leftist candidate Roberto Sanchez and Keiko Fujimori. An Ipsos quick count gave Sanchez 50.3% and Fujimori 49.7%. The official tally later showed Fujimori ahead on partial results, though key Sanchez strongholds were still missing. Both camps moved to shape the narrative, with Sanchez urging supporters to defend the vote and Fujimori saying no winner should be declared yet. Election officials said the final audited count could take about a month, leaving Peru facing an extended period of political uncertainty amid concerns over isolated ballot irregularities and rising public anxiety. MSCI NUAM Peru General -4.9% to 50,929, USDPEN +1.82% to 3.47, 10y PGB +23bp to 6.24%.
U.S. New York Fed’s 1y inflation expectation is expected to rise to 3.7% vs. 3.6%.
Canada Bloomberg Nanos Confidence is expected at 50.9 vs. 50.7 prior.
Central bank speakers: Fed speakers are in external communications blackout. ECB is in its pre-rate decision quiet period.
U.S. Treasury sells $89bn in 13-week bills and $77bn in 26-week bills.
Mood: iFlow Mood remains entrenched in risk-off territory, with continued equity selling offset by demand for core government bonds.
FX: Broad-based but moderate demand was seen across currencies, led by CHF, SEK, MXN and ZAR, alongside inflows into EUR, GBP and JPY. USD recorded light outflows, while BRL, CLP and CAD faced the heaviest selling pressure.
FI: Government bond demand remained broad across G10 markets and LatAm. In contrast, EMEA and APAC sovereign debt saw net selling, led by Indonesia and South Africa.
Equities: Flows showed sharp regional divergence. EMEA and LatAm equities continued to experience broad outflows, while G10 markets attracted inflows, led by the U.S. and Australia. APAC flows were mixed, with buying concentrated in China, Thailand and Taiwan, while South Korea and Indonesia remained under significant selling pressure.
“Success is how high you bounce when you hit bottom.” – General George S. Patton
“Future shock is the shattering stress and disorientation that we induce in individuals by subjecting them to too much change in too short a time.” – Alvin Toffler
Germany’s Sentix investor confidence index for June 2026 showed that sentiment remained weak despite a second monthly improvement in the euro area. The euro area headline index rose 3.0 points to -13.4, while expectations improved by 4.8 points to -6.5 and the current conditions gauge edged up to -20.0. Sentix noted global easing signals were driven mainly by the U.S. and Asia, with the global aggregate climbing 4.4 points to 8.0. Germany remained the laggard, as the overall index improved only to -28.5 and current conditions fell to their lowest level since February 2025. The report still classed the euro area as in downturn and Germany in recession. Euro Stoxx 50 -0.8% to 6,014, EURUSD +0.009% to 1.1523, BBG AGG Euro Government High Grade EUR 0bp to 3.313%.
Germany’s manufacturing orders in April 2026 fell 3.8% m/m on a real, seasonally and calendar adjusted basis, while rising 1.6% from a year earlier, according to Destatis. The weak April outcome followed a revised 4.5% increase in March. Destatis said the drop was driven mainly by sharp declines in automobile orders, electrical equipment, and machinery, with foreign orders down 4.2% and domestic orders down 2.9%. By category, capital goods, intermediate goods, and consumer goods all weakened. In contrast, real manufacturing sales edged up 0.1% m/m and were 0.6% above April 2025, indicating some resilience despite softer demand. DAX -0.93% to 24,528, EURUSD +0.009% to 1.1523, 10y Bund +1.8bp to 3.056%.
Spain’s housing price index for Q1 2026 rose 12.9% y/y, unchanged from the previous quarter, according to the National Statistics Institute. New housing prices slowed to 9.1% from 11.2%, while secondhand homes accelerated to 13.5% from 13.1%. On a quarterly basis, the overall index increased 3.5%, with both new and existing homes rising by the same pace. Prices increased in every autonomous community and city, led by Aragon and Murcia at 15.6%, while Catalonia, Navarra and the Basque Country posted the smallest gains. The series was also rebased to 2025. IBEX 35 -0.43% to 18,278, EURUSD +0.009% to 1.1523, 10y Bono +2bp to 3.495%.
U.K. private sector jobs data for May showed a mixed labor market, with permanent placements falling at the fastest pace in ten months while temporary billings rose at the quickest rate in more than three years. The KPMG and REC survey suggested that heightened uncertainty around the business outlook, linked to the war in Iran and U.K. political turbulence, encouraged employers to delay permanent hiring and rely more on flexible staffing. Demand for workers weakened further, as overall vacancies fell and candidate availability rose sharply amid redundancies and weaker job security. Pay growth remained subdued, with both starting salaries and temp wages increasing only modestly and below historical averages. FTSE 100 -0.2% to 10,347, GBPUSD -0.023% to 1.3339, 10y gilt +3.6bp to 4.939%.
Czech industrial production for April 2026 increased 1.5% y/y and 1.4% m/m, while new orders rose 2.7% y/y. Output growth was driven mainly by motor vehicles and parts, as well as computers, electronic and optical products, with additional support from fabricated metals, chemicals, and non-metal mineral products. The main drags came from mining and quarrying, repair and installation of machinery, and weaker food and beverage production. New orders were lifted by computer and optical products, motor vehicles, and machinery, while fabricated metals, pharmaceuticals, textiles, and paper products declined. Employment in industry fell 1.0% y/y. Prague SE -0.34% to 2,519, EURCZK +0.05% to 24.208, 10y CZGB +3.2bp to 4.91%.
Czech unemployment fell to 4.8% in May 2026 from 4.9% in April, marking a third consecutive monthly decline and reflecting seasonal hiring and an improving economy. The number of registered unemployed stood at 358,852, although this was still around 42,800 higher than a year earlier. The number of vacancies was broadly unchanged at 94,380, leaving about 3.8 jobseekers per vacancy nationwide. During the month, 32,788 people found employment, with manufacturing, wholesale and retail trade, administrative services and construction among the main hiring sectors. A notable feature was the rise in self-employment, with 13,648 people – equivalent to almost 42% of those leaving unemployment for work – starting their own businesses.
Japan’s final Q1 2026 real GDP rose 0.5% q/q (Q4 25: 0.2% q/q). On a y/y basis, final real GDP is revised lower to 1.8% y/y vs. initial estimate of 2.1% y/y or 0.7% in Q4 2025. Growth was supported by domestic demand (0.1% q/q, 0.2% y/y) especially private consumption (0.3% q/q, 1.2% y/y), household spending (0.3% q/q, 1.1% y/y), residential investment (0.9% q/q, -2.6% y/y), and public demand (0.5% q/q, 1.2% y/y). Exports also contributed positively (1.8% q/q, 2.1% y/y), while non-residential investment (-0.7% q/q, 1.1% y/y) declined, and inventories were a drag. Nominal GDP rose 0.6% q/q and 3.6% y/y (Q4: 0.9% q/q, 3.7% y/y) The GDP deflator increased 3.2% y/y (Q4 25: 3.4% y/y), indicating continued price pressure. Overall, the final data suggest Japan’s economy maintained moderate expansion in Q1, with stronger-than-expected consumption offsetting weakness in business investment. Nikkei -4.24% to 63,762, USDJPY +0.032% to 160.24, 10y JGB +5.2bp to 2.724%.
Japan’s balance of payments for April 2026 showed a stronger current account surplus of ¥3.91tn, up sharply from a year earlier, as the primary income balance widened to ¥4.21tn. The trade and services balance narrowed its deficit to ¥20.3 bn, helped by a return to a trade surplus of ¥395.7bn as exports rose 13.9% and outpaced the 9.5% increase in imports. The services deficit also improved. On the financial account, net inflows were ¥4.46tn, supported by other investments and foreign purchases of domestic securities, while direct investment remained positive.
Japan’s April balance-of-payments data showed a larger financial account surplus, with net financial inflows of ¥4.46tn, up from ¥4.31tn in March. The improvement was driven mainly by a sharp increase in other investment, which recorded a net inflow of ¥14.2tn, while direct investment also remained positive at ¥2.77tn. In contrast, portfolio investment posted a net outflow of ¥13.29tn, reflecting heavy selling of equities and investment fund shares, partly offset by inflows into medium- and long-term bonds. Foreign investors increased purchases of Japanese equities and medium- and long-term debt, supporting inward investment. The statement also noted ongoing foreign direct investment activity by Japanese firms abroad and stronger inflows from non-residents into Japan.
Japan’s May 2026 Economy Watchers Survey showed the current conditions DI rose 2.8 points m/m to 43.6, indicating a modest improvement from April. Household-related sentiment improved, supported by gains in food and dining-related activity, while corporate sentiment also rose as manufacturing improved; employment-related conditions strengthened as well. The outlook DI increased 1.3 points m/m to 40.7, as higher household and corporate readings outweighed a decline in employment-related sentiment. On an unadjusted basis, the current conditions DI rose 1.5 points m/m to 43.1, while the outlook DI increased 1.9 points m/m to 40.9. Overall, the survey described the economy as showing signs of a weak recovery, with downside pressure on sentiment from tensions in the Middle East and continued uncertainty ahead.
Japan’s May 2026 bank lending data showed lending by banks, shinkin banks, and trusts rising 5.7% y/y to ¥670.8tn, up from 5.4% y/y in April. Lending by total banks increased 6.3% y/y to ¥591.5tn from 5.9% y/y in March, with major banks leading at 8.7% y/y (from 7.9% y/y). Regional banks rose 4.3% y/y (from 4.2% y/y), while shinkin banks slowed to 1.7% y/y (from 1.5% y/y). Foreign banks remained elevated at 24.6% y/y, though easing from 29.1% y/y. The data indicate broad-based credit growth across Japan’s banking system, with especially strong momentum at major banks.
South Korea’s National Pension Service has resumed selling forward FX contracts after pausing earlier this year, signaling active hedging as the won weakens and the market tests higher USDKRW levels. According to foreign exchange authorities, the pension fund has again been offering forward sales in the Seoul FX market, and such activity is expected to continue for the time being. The move follows its April “new framework,” which raised the baseline hedge ratio for overseas investments to 15%, up at least five percentage points from the previous setting. The NPS also continues to use FX swaps with Bank of Korea to fund dollar needs. KOSPI -8.23% to 7,489, USDKRW +1.587% to 1535.2, 10y KTB +2.5bp to 4.252%.
South Korea’s corporate lending accelerated sharply in Q1 2026, with outstanding loans to companies rising by ₩35.6tn q/q to ₩2061.8tn as of end-March, the fastest increase in 3.5 years and well above the ₩8.5tn gain in Q4 2025. Bank of Korea said the pickup was driven by stronger demand from the service sector as the economy showed signs of recovery. Loans to manufacturing firms increased by ₩11.1tn q/q, while service sector lending jumped by ₩24tn q/q, led by financial and retail borrowers. By purpose, operating funds rose by ₩26.2tn q/q, sharply faster than in the previous quarter, and facility investment loans grew by ₩9.4tn q/q, also improving from Q4.