Market Movers: Bounce not recovery?
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Bob Savage
Time to Read: 7 minutes
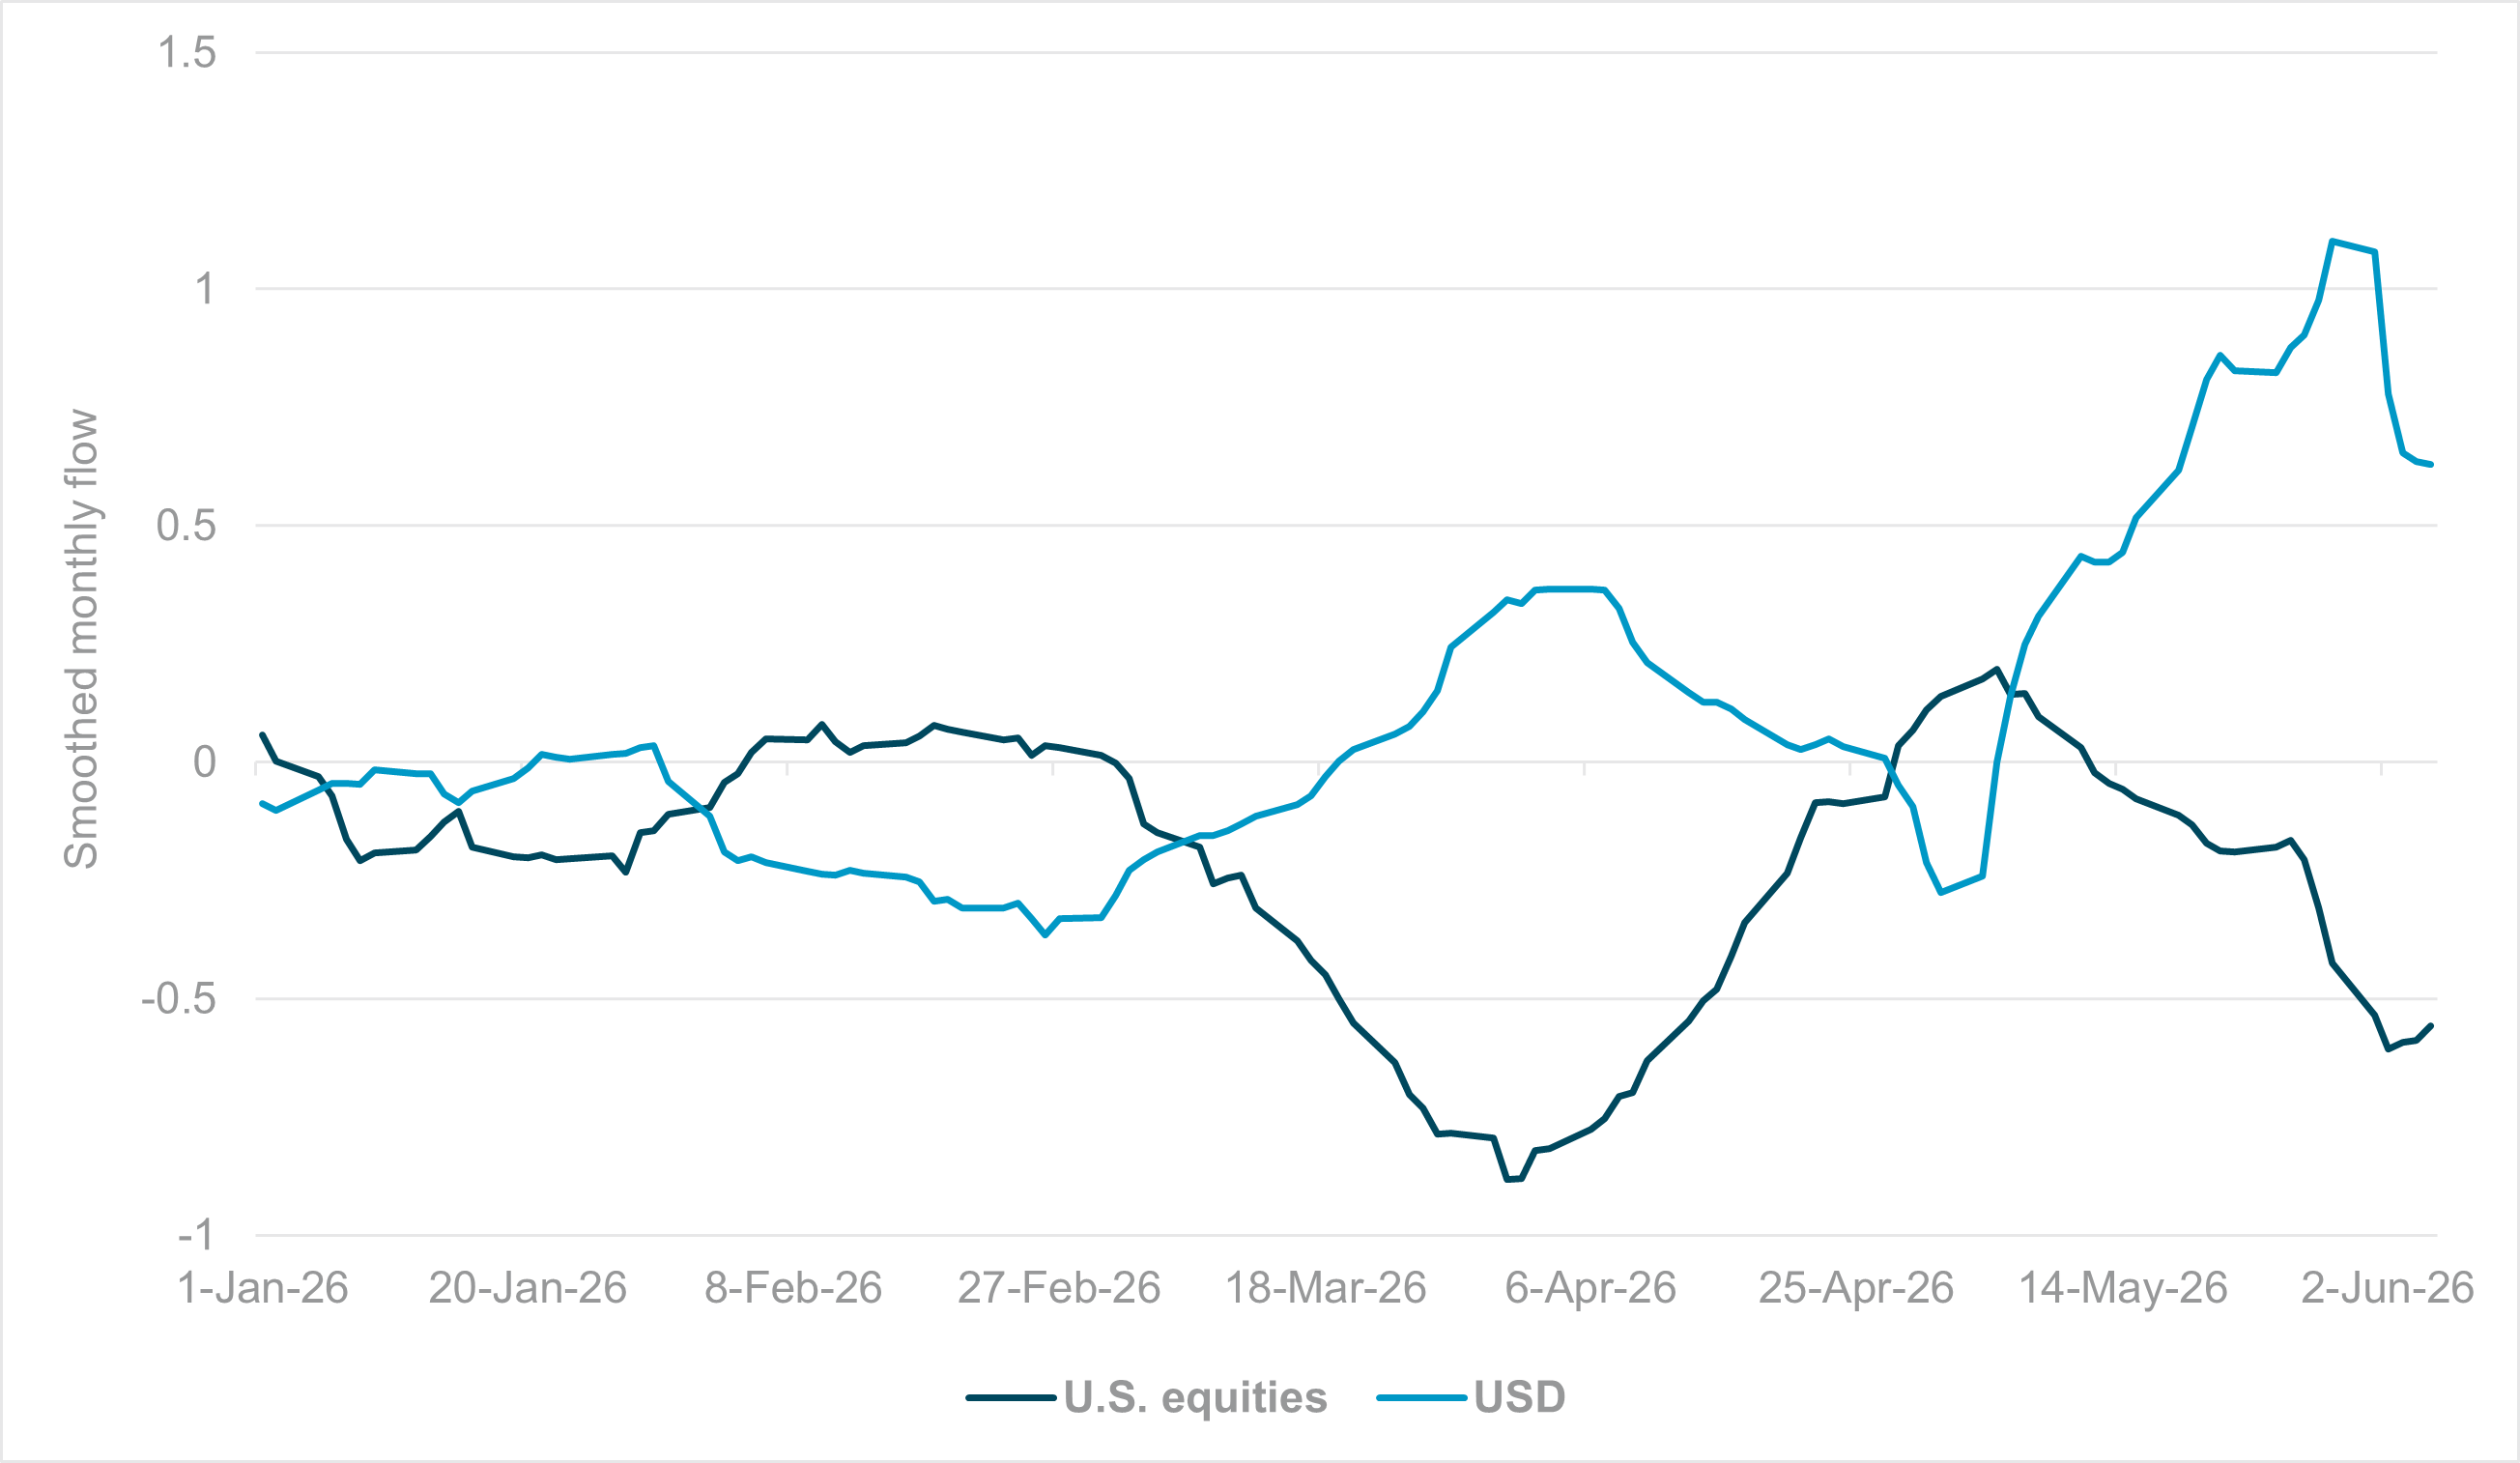
Cross-border U.S. asset flows largely match hedging behavior
Source: BNY
As expected, much of APAC and EM began the week with both currencies and equity markets under pressure. Yesterday generated some relief, but we expect a defensive posture until at least next week’s Fed meeting, as the Warsh Fed sets its agenda and the rest of the world can establish where they stand on policy differentials. On a tactical basis, however, we believe the FX and equity link should remain intact. In theory, currency moves should be more muted in response to equity or fixed income developments, since much of the flow would be hedged. However, our flows indicate this stance has not been uniform and really depends on the underlying asset and currency. For example, on an aggregate basis, our flows indicate that flows into APAC fixed income have largely been hedged, with periods of inflows into EM APAC sovereign debt accompanied by outflows in FX. However, these aggregate figures are compromised by high levels of flows into CGBs relative to CNY and mask the situation going on in the likes of INR, IDR and PHP, which are under the greatest scrutiny at present for balance-of-payments stress. Meanwhile, cross-border FX and U.S. equity flows have mirrored each other extremely well year for much of the year, and even turning points have matched well. The large selloff during the conflict was accompanied by hedge unwinding, while the recent surge in FX flows appears to reflect a decline in equity interest. The past week has generated the first meaningful change this year, as USD sales accompanied USD equity sales. But our flows suggest that hedges are now below average levels seen last year, so some renewed forward USD sales are understandable on remaining assets, especially if carry (and hedging costs) begin to rise later this year.
The second day for AI technology shares bouncing back has not yet won over doubters about a full recovery. Fear of missing out isn’t driving positioning as much as holding steady into rate decisions, inflation data and IPOs liquidity tests. Easing tensions in Iran allow oil to pull back, but the key driver for markets beyond momentum is intervention from Indonesia to South Korea to cap USD gains. The dollar is marginally lower, with GBP, NZD and IDR posting gains, while JPY and CAD await central bank decisions. Similarly, bonds are slightly bid globally.
Bottom Line. The U.S. CBO May budget review showed a federal deficit of $1.2tn for the first eight months of FY 2026. This is better than 2025, but some of this is due to calendar effects. The U.S. debt level, the 3y bond auction, IG issuance and the setup for IPO-related liquidity all matter. The music for the dance continues as long as there is money to put to work in equities. The bounce may not be a recovery if renewed doubt about rising rates shifts the burden back onto FX markets and intervention, especially with CPI and central bank decisions still ahead. Today may be one of those fizzles where Tuesday turnarounds do 180- rather than 360-degree moves.
President Donald Trump said progress was being made toward a deal with Iran after Israel and Iran agreed to halt strikes following a renewed flare up that sent ballistic missiles across the region. Trump said the sides were in the final throes of a very good deal and suggested an outline could emerge within one or two days. Israel and Iran both signaled a pause, though each warned of retaliation if attacked again. The brief easing helped push Brent crude down 1.9%, as markets watched whether shipping through the Strait of Hormuz would normalize and whether the fragile ceasefire could hold. Brent -1.91% to 92.45, WTI -2.344% to 89.16, Omani Crude -3.311% to 89.38, Dubai Crude +0.781% to 91.17.
Bank of Japan (BOJ) officials are increasingly leaning toward pausing further reductions in bond purchases after March 2027, reflecting growing concern about market stability as the central bank unwinds years of quantitative easing. Sources indicate policymakers may maintain monthly bond purchases at around ¥2.1tn rather than continue tapering, arguing that the BOJ’s balance sheet will shrink substantially through the natural runoff of maturing bonds. However, opinion within the policy board remains divided, with some members favoring a steadier reduction in bond holdings to advance policy normalization. The debate comes ahead of the June 15–16 meeting, where the BOJ is also widely expected to raise its policy rate to 1.0% from 0.75%. The discussion highlights the tension between reducing the BOJ’s dominant presence in the government bond market and avoiding excessive volatility in yields as Japan continues its monetary policy normalization. Nikkei +2.17% to 65,417, USDJPY -0.119% to 160.2, 10y JGB -4.5bp to 2.682%.
Bank Indonesia (BI) delivered an off-cycle rate hike, raising the BI-Rate by 25bp to 5.50%, alongside increases in the Deposit Facility to 4.50% and Lending Facility to 6.25%. The move is intended to strengthen rupiah stability amid heightened global volatility from Middle East tensions and weaker-than-expected rupiah performance since the May policy meeting. BI said the tightening is also pre-emptive to keep 2026–2027 inflation within the 2.5% ±1% target and to support foreign portfolio inflows. It will also lift SRBI yields across tenors, lower hedging swap costs for foreign investors, reopen repo windows for banks, and intensify rupiah and FX operations, while coordinating closely with fiscal policy to safeguard external resilience. JCI +3.56% to 5,532, USDIDR +0.387% to 18108, 10y IDGB +22.3bp to 7.502%.
China is preparing a major nationwide AI infrastructure push, with key agencies including the National Development and Reform Commission drafting a five-year plan to spend about ¥2tn on data centers and related computing networks. The initiative aims to link fragmented regional facilities into a unified system by 2028, strengthen domestic AI capacity, and reduce reliance on foreign chipmakers such as Nvidia and AMD by prioritizing local suppliers like Huawei. Funding is expected to come mainly from sovereign debt, special government bonds and state investment funds, with bank loans and private capital as supplements. The broader plan could eventually lift total investment above ¥5tn, including power grid integration, and support wider AI adoption across public services and industry. CSI 300 +1.87% to 4,802, USDCNY -0.194% to 6.7702, 10y CGB +1bp to 1.735%.
U.S. May NFIB Small Business Optimism is expected to rise to 96.0 vs. 95.9.
U.S. ADP Weekly Employment Change is due; expected flat at 35.75k which was the prior week’s level.
U.S. April Exports forecast to rise to 2.6% m/m vs. 2.0% m/m. Imports are expected to ease to 1.2% m/m vs. 2.3% m/m. U.S. April Trade Balance is expected to narrow to -$56.5bn vs. -$60.3bn.
U.S. May Existing Home Sales is forecast to rise to 4.06mn, 1.0% vs. 4.02mn, 0.2% in April.
U.S. April Wholesale Trade Sales is forecast at 2% vs. 2.8% m/m prior. Final Wholesale Inventories is expected to rise to 0.6% m/m vs. flash 0.5% m/m or 1.3% in March.
Canada April International Merchandise Trade is expected to widen to $2.6bn vs. $1.8bn in March.
Central bank speakers: Banque de France Governor Emmanuel Moulin speaks at Europlace finance forum in Paris.
U.S. Treasury sells $65bn in 6-week bills, $50bn in 52-week bills and $58bn of 3y notes.
Mood: iFlow Mood deteriorated marginally, driven by increased equity selling alongside continued inflows into core government bonds.
FX: BRL and CAD led outflows, followed by CLP, USD, AUD, HUF and TRY. In contrast, CHF, EUR and MXN attracted the strongest inflows. Elsewhere, GBP and JPY saw modest demand, while APAC FX flows remained light and mixed.
FI: Government bond demand was concentrated in LatAm, Canada and Sweden, while APAC and South African sovereign bonds faced broad selling pressure.
Equities: G10 equity flows were mixed, with buying in the U.S., Eurozone and Australia offset by selling in the U.K. and Japan. EMEA and LatAm equities experienced net outflows, while APAC flows diverged sharply, with strong buying in China and Thailand contrasting with heavy selling in Indonesia and South Korea.
“Our greatest glory is not in never falling, but in rising every time we fall.” – Oliver Goldsmith
“Resilience isn’t just about bouncing back; it’s about bouncing forward. Use setbacks as stepping stones to propel you toward your goals.” – David Goggins
German industrial production in April 2026 rose 0.4% m/m, according to Destatis, after a revised 0.1% decline in March, while output was 0.5% below a year earlier. The improvement was driven mainly by construction, which climbed 2.4%, alongside gains in chemicals and fabricated metal products, although motor vehicle production fell 4.7%. Manufacturing excluding energy and construction was flat on the month, as higher output of intermediate and consumer goods was offset by lower investment goods production. Energy output increased 0.2%. In energy intensive industries, production rose 1.0% on the month and was 0.9% higher than a year earlier. DAX +0.42% to 24,721, EURUSD +0.104% to 1.1546, 10y Bund -0.6bp to 3.054%.
U.K. retail sales strengthened in May 2026, with the heatwave driving a broad-based rise in summer-related spending, up 3.4% y/y from -3.4% y/y in April. Outdoor and seasonal goods led the gains, including fans, lighter bedding, paddling pools, summer footwear and clothing, while food sales also benefited from bank holiday barbecues. The report noted that many shoppers shifted purchases online to avoid the heat, boosting e-commerce at the expense of stores. Overall, May was described as a month of “extremes,” with unusually warm weather lifting both food and non-food demand. FTSE 100 -0.24% to 10,349, GBPUSD +0.27% to 1.3376, 10y gilt -2.1bp to 4.922%.
Norway’s producer price data for May showed that manufacturing prices received by domestic producers rose 9.4% y/y, with export goods again recording the strongest price growth. Export prices increased 2.2% from April, after a 7.2% rise the month before, while domestic market prices were unchanged on the month. On a y/y basis, exported industrial goods were up 12.9%, led by refined petroleum products, chemicals and metals. Food export prices fell for a second month but remained about 12% above a year earlier. Oil and gas extraction prices dropped 4.9% on the month, while power supply prices rose 6.0%. OSE -0.06% to 1,992, EURNOK +0.179% to 10.9467, 10y NGB -1.4bp to 4.367%.
Hungary’s consumer prices for May 2026 were flat on the month, after a 0.5% rise in food prices and a 2.1% decline in food and beverage serving services. Food was mixed, with higher prices for potatoes, fresh fruit and some bakery items offset by cheaper vegetables, eggs, cheese, coffee, sugar, bread, pork and milk products. Services increased 0.2%, led by domestic recreation, while electricity, gas and other fuels fell 0.8% and motor fuel prices were unchanged. On an annual basis, food prices rose 0.5%, services climbed 4.3% and tobacco increased 3.3%, while energy costs declined 2.0%, keeping overall inflation contained. Budapest SI +0.83% to 134,821, EURHUF -0.161% to 355.38, 10y HGB +8bp to 5.52%.
South Africa’s gross domestic product in the first quarter of 2026 increased by 0.5% q/q, after a 0.4% rise in Q4 2025. On the production side, finance, real estate and business services grew 0.9%, agriculture, forestry and fishing rose 3.9%, trade, catering and accommodation advanced 0.7%, and transport, storage and communication gained 0.7%, while manufacturing fell 0.8%. On the expenditure side, real GDP also rose 0.5%, supported by government consumption and net exports, while household spending was nearly flat and gross fixed capital formation declined 1.1%. Inventories were drawn down by R22.4bn. JSE TOP 40 +0.57% to 103,710, USDZAR -0.367% to 16.4607, 10y SAGB -10.1bp to 8.801%.
Japan’s money supply growth firmed in May. M2 rose 2.5% y/y in May, up from 2.3% y/y in April, while M3 increased 1.7% y/y, unchanged from April. Broader liquidity also strengthened, with M1 edging up to 0.3% y/y from 0.2% y/y previously. Among components, quasi-money remained solid at 5.0% y/y (vs. 5.1% in April), while currency in circulation stayed subdued at -1.1% y/y. The data suggest continued, modest expansion in monetary aggregates, supported by deposit money growth, though cash in circulation remained weak. The Bank of Japan’s table also showed stronger growth in broader measures such as L, reflecting firmer financial asset balances. Nikkei +2.17% to 65,417, USDJPY -0.119% to 160.2, 10y JGB -4.5bp to 2.682%.
Australia’s NAB Monthly Business Survey for May 2026 showed business confidence rose 10 points to -14 index points (from a very low base), while business conditions were unchanged at 3 index points, still below the long-run average. Capacity utilization eased to 81.9%, the first sub-82% reading in 12 months, suggesting some slowing in activity. Forward orders and capex improved, indicating some resilience in demand and investment intentions. Cost and price pressures moderated, with purchase costs, labor costs, product prices and retail prices all easing, though margins remain under pressure. NAB said the economy appears to have cooled somewhat in 2026, while confidence remains weak across industries and is likely to stay a key concern for investment and hiring decisions. ASX -0.33% to 5,557, AUDUSD -0.071% to 0.7053, 10y ACGB +1.2bp to 4.92%.
Australia’s Westpac–Melbourne Institute Consumer Sentiment Index fell 2.9% m/m to 80.6 in June from 83.0 in May, signaling persistent deep pessimism among consumers. The report said households are feeling renewed pressure on finances and remain fearful about the year ahead, with cost-of-living concerns still dominant. Near-term concern about the economy eased somewhat, but the medium-term outlook slipped to a three-year low. Unemployment expectations were broadly steady at still-elevated levels. Views on buying a home became less bleak, though house price expectations dropped sharply, suggesting some unease around recently announced tax changes. Overall, the survey indicates Australian consumers remain highly cautious, with pessimists continuing to outnumber optimists by a wide margin and expectations for family finances deteriorating sharply again in June.
New Zealand’s March 2026 quarter business financial data showed broad-based improvement across market industries. Total sales rose to $200bn, up $10bn q/q, while purchases increased to $140bn and salaries and wages to $32bn; operating profit climbed to $29bn. Seasonally adjusted sales increased in 11 of 14 industries, led by wholesale trade, manufacturing, and retail trade and accommodation. Manufacturing sales rose 2.8% q/q to $35.6bn, after a 0.8% rise in the December 2025 quarter, while volumes increased 3.6% q/q (Q4 25: -0.4% q/q). Wholesale trade sales grew 3.8% q/q to $42.3bn, following a previous 1.4% gain, and stocks stood at $19bn. Annual comparisons were also firmer in most sectors, with especially strong gains in operating profit and wholesale trade. NZX 50 +1.27% to 13,204, NZDUSD +0.276% to 0.5832, 10y NZGB -3.7bp to 4.56%.
New Zealand’s business employment data for the March 2026 quarter showed total actual filled jobs at 2.26mn. Seasonally adjusted filled jobs rose 0.1% q/q, or 2,452 jobs, versus the December 2025 quarter. By industry, gains were led by transport, postal and warehousing (0.9% q/q), education and training (0.3% q/q), and public administration and safety (0.4% q/q), while professional, scientific and technical services (-0.3% q/q) and manufacturing (-0.3% q/q) declined. Regionally, Canterbury and Waikato recorded the largest increases, while Northland and Bay of Plenty fell. For the year ended March 2026, total gross earnings increased 2.7% y/y, or $4.8bn, compared with the year ended March 2025. Annual earnings rose most in health care and social assistance, education and training, and public administration and safety. Men’s filled jobs fell 0.3% y/y, while women’s rose 0.1% y/y.
China’s trade data for May showed a sharp acceleration, with exports rising 19.4% y/y in U.S. dollar terms, up from 14.1% y/y in April, while imports increased 27.4% y/y after 25.3% y/y previously. The rebound was driven by strong overseas demand for chips, autos, and other high-tech goods, helped by the global AI investment boom. Exports of automated data processing equipment surged 66.1% y/y, high-tech products rose 50.9% y/y, and cars climbed 39% y/y. The trade surplus widened to $105.43bn in May from $84.8bn in April. Reuters also noted that factory data for May showed a sharp drop in new export orders from April’s peak, suggesting some cooling ahead. CSI 300 +1.87% to 4,802, USDCNY +0.17% to 6.7718, 10y CGB +0.8bp to 1.733%.
South Korea’s Q1 Real GDP rose 1.8% q/q, 3.8% y/y vs. -0.1% q/q, 2.0% y/y in Q4 2025. On the production side, growth was led by manufacturing (+3.9% q/q, 7.2% y/y), supported by computers, electronics and optical products, with construction up 2.2% q/q, -3.9% y/y and services up 0.6% q/q. On expenditure, private consumption increased 0.6% q/q, facilities investment surged 6.6% q/q, and exports rose 5.9% q/q on stronger IT shipments, especially semiconductors. Nominal GDP expanded 10.5% q/q, while the GDP deflator rose 12.9% y/y. Real personal gross disposable income (PGDI) edged up 0.3% q/q. The gross saving ratio increased to 41.7% (Q4 25: 36%), while the household net saving ratio fell slightly to 8.8% (Q4 25: 9.1%). KOSPI +8.18% to 8,097, USDKRW +0.616% to 1518.75, 10y KTB +9.3bp to 4.345%.
Singapore’s Prime Minister Lawrence Wong said the government will shift away from relying mainly on baby incentives and instead focus on improving conditions for families, as the country faces a record-low resident total fertility rate of 0.87 in 2025. He said prior measures such as baby bonus cash gifts, expanded paternity leave, and eased egg-freezing rules have not brought lasting gains. Wong acknowledged that financial costs, parenting stress and work-family balance remain key deterrents. He also said Singapore will stay open to immigration, while using more technology and AI to support productivity and economic growth, given that fertility is unlikely to rebound sharply. The government has already launched a ministerial task force and nearly S$7bn in marriage and parenthood initiatives. STI +1.11% to 5,019, USDSGD +0.171% to 1.2865, 10y SGB +8.8bp to 2.176%.