Market Movers: Anxiety
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Geoffrey Yu
Time to Read: 5 minutes
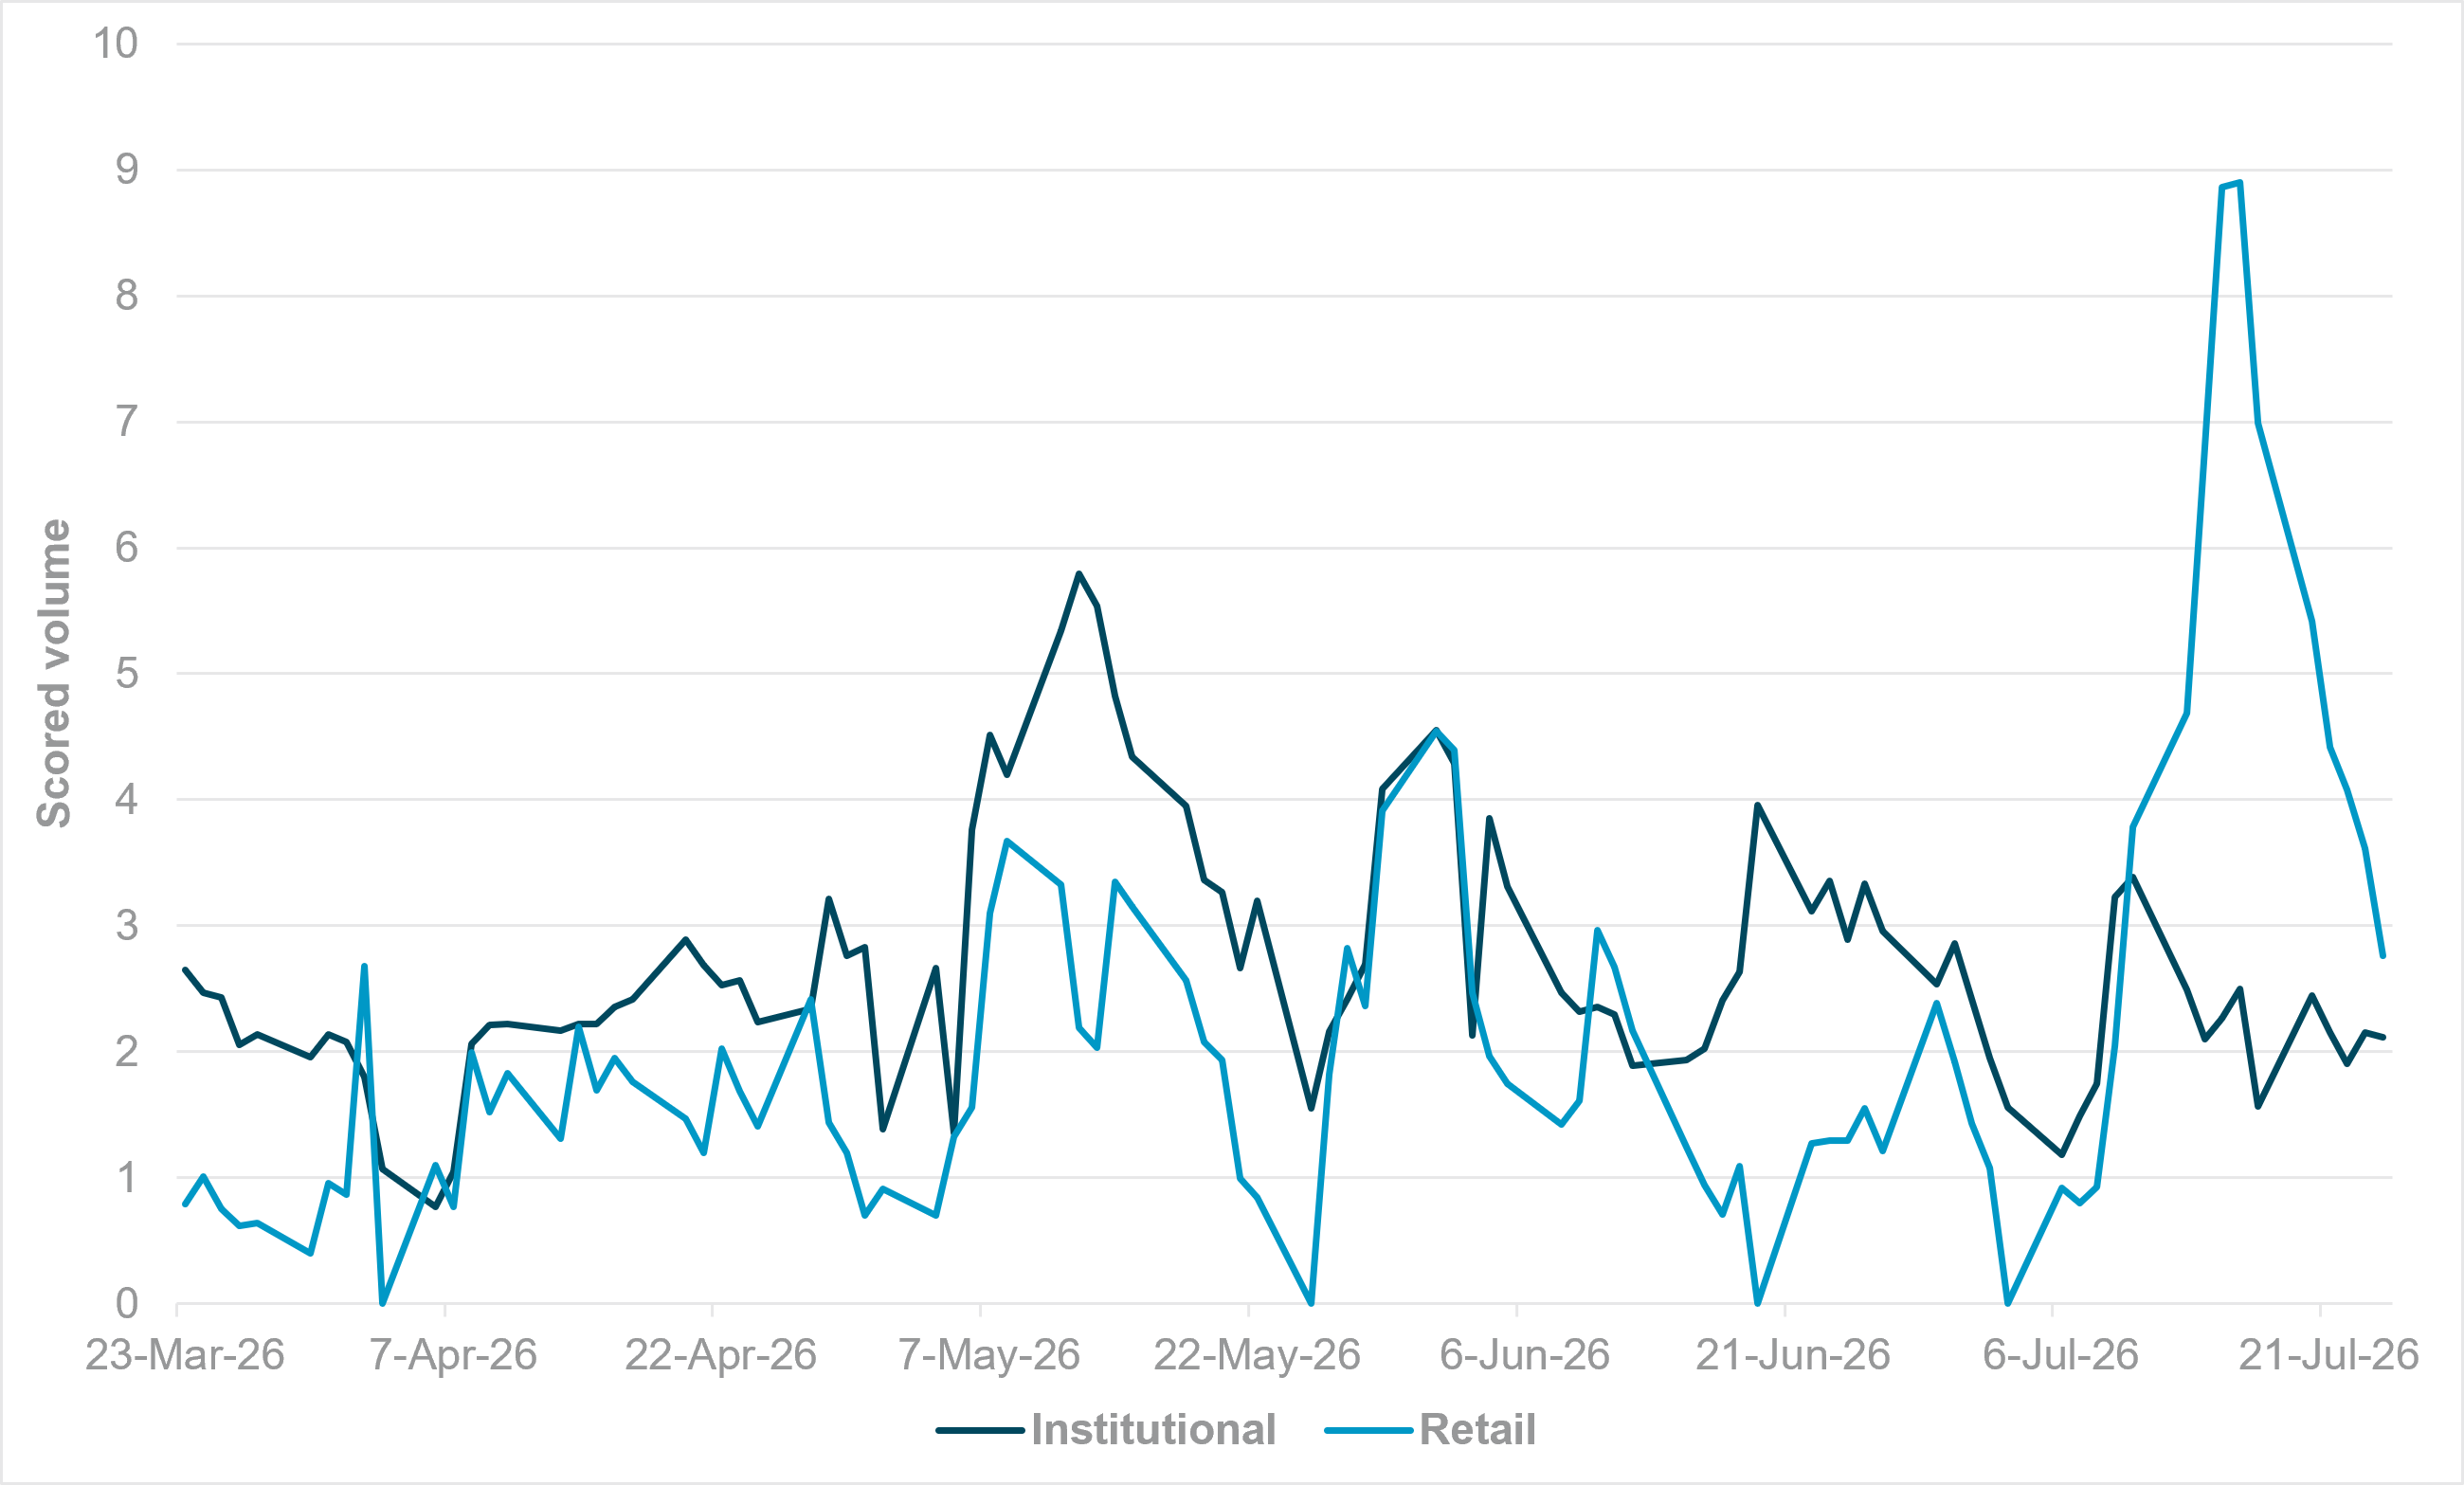
Retail volumes collapse in KOSPI
Source: BNY
Retail deleveraging is emerging as a key amplifier of South Korea’s sell-off. Retail investors dominate domestic turnover, and they entered this correction with elevated margin balances and heavy exposure to leveraged products tied to Samsung Electronics and SK Hynix. An 11% decline in the KOSPI is therefore likely to have triggered widespread margin calls and forced liquidations, accelerating what began as a fundamental reassessment into a broader liquidity event. The risk is no longer confined to Seoul. SK Hynix’s recent U.S. ADR listing has materially expanded retail access, while leveraged products in Hong Kong have created additional momentum-driven positioning. The result is a more globally connected retail investor base, increasing the scope for cross-market feedback loops as selling pressure transmits across time zones.
Our flow data reinforce this shift in market composition. Retail participation has significantly outpaced institutional activity since SK Hynix’s July 10 ADR listing. Daily retail scored volume jumped from 2.05 on July 9 to 3.78 on July 10, before accelerating to 4.69 (July 13), 6.81 (July 14) and peaking at 8.86–8.90 (July 15–16). Elevated retail activity persisted through the following week, while institutional scored volume remained broadly stable in the 2–3 range. The timing strongly suggests a surge in speculative retail participation across South Korean equities. Against that backdrop, today’s sharp decline was always likely to generate a disproportionately aggressive deleveraging response, amplifying downside momentum well beyond what fundamentals alone would imply.
AI unwind: Anxiety is replacing relief. South Korea’s KOSPI fell around 11%, led by sharp declines in Samsung Electronics and SK Hynix, while weakness spread across Japan and Taiwan. Concerns over hyperscaler capital spending, stronger Chinese competition, and the sustainability of AI valuations are converging. The speed and breadth of the decline suggest that a fundamental reassessment is now interacting with crowded positioning and tighter liquidity.
Rates and geopolitics: Tomorrow’s Fed decision adds a second source of stress. A hike is still not the base case, but the perceived risk is rising, and tighter financial conditions are clearly unhelpful while equities are already under pressure. Continued U.S.–Iran diplomacy is helping contain oil prices, yet the relief is doing little for sentiment. Markets have moved on from geopolitics to valuations, leverage and positioning as the dominant drivers.
Europe holds: Europe is weathering the anxiety relatively well. Lower oil is supportive, while the market has limited direct exposure to the AI trade outside a handful of names. That makes the region a temporary haven for now, although hawkish pricing for both the ECB and BOE remains a constraint.
Ahead today: Expect nervous trading ahead of hyperscaler earnings and tomorrow’s Fed decision. The U.S. advance goods trade balance, retail and wholesale inventories, and Conference Board consumer confidence are today’s main releases. Weak data would deepen growth concerns, while stronger data could reinforce hike risk and keep pressure on front-end yields.
Bottom line: Lower oil and continued diplomacy have removed one source of pressure, but haven’t restored confidence. Until earnings validate AI spending and the Fed resolves the rate risk, anxiety will remain the dominant market signal.
U.S. officials say sanctions and a naval blockade may ultimately inflict more damage on Iran than bombs, though over a longer timeline. The maximum-pressure campaign is already deepening economic strain, with intelligence and open-source reports pointing to gasoline shortages, pressure on banks, and difficulty paying fighters. Officials say Iran’s main priority in talks is access to money, including unfrozen assets and relief from U.S. sanctions, alongside assurances against further U.S. strikes. Washington has imposed sanctions on more than 1,000 people, vessels and aircraft, targeting Iran’s oil trade, shadow banking, weapons procurement and shipping networks. White House officials say Trump prefers a diplomatic deal but retains all options if Iran continues hostile activity in the Strait of Hormuz or against allies. Brent -1.913% to 86.67, WTI -1.514% to 81.36, Omani Crude -6.834% to 82.21, Dubai Crude -2.555% to 76.913.
German officials are privately assessing China economic vulnerabilities as Berlin prepares for a possible trade confrontation between the EU and Beijing. According to people familiar with the matter, the government is mapping dependencies through trade flows, supply chains and company data to identify where China still relies on German and European technology, specialized components and industrial know-how. Semiconductor-related suppliers, including firms tied to ASML’s production chain, are among the sectors being reviewed, alongside advanced medical products. Chancellor Friedrich Merz has taken a tougher line on China, saying Europe must defend itself against unfair competition while preserving reciprocity and resilience. DAX +0.74% to 25,548, EURUSD 0% to 1.1369, 10y Bund -2.1bp to 3.112%.
Japan’s government is reported to plan a cut in the food and beverages sales tax to 1% for two years starting next April, fulfilling a key election pledge by Prime Minister Sanae Takaichi. She is expected to direct the ruling Liberal Democratic Party to begin drafting legislation soon. The proposal follows a cross-party panel’s failure to reach consensus on financing or whether the cut should be permanent. The move would lower the current 8% rate, but the government has yet to explain how it will cover the annual cost of more than ¥4tn. Investors are likely to focus on the fiscal implications, which may keep pressure on Japanese government bond yields. Nikkei -3.95% to 62,365, USDJPY -0.086% to 163.73, 10y JGB +0.4bp to 2.79%.
Reserve Bank of Australia Governor Michele Bullock signaled that an interest rate hike will be on the table at the RBA’s August 10–11 meeting. She said inflation remains too high, with the board focused on preventing elevated cost pressures from becoming entrenched. Bullock said domestic demand has eased and labor market conditions have softened, but weak productivity is limiting the economy’s ability to grow without reigniting inflation. She warned that without stronger productivity, Australians will struggle to see meaningful real wage growth. Bullock also noted the full effect of the RBA’s three rate rises this year has yet to filter through the economy. On financial stability, she said risks from housing weakness and negative equity appear contained. The bank is prepared to tighten further if needed to meet its mandate. ASX -0.03% to 5,792, AUDUSD -0.386% to 0.6975, 10y ACGB -3.7bp to 4.961%.
U.S. ADP Weekly Employment Change, 16.5k prior.
U.S. June Advance Goods Trade Balance is forecast to narrow to -$100bn vs. -$105.9bn.
U.S. June Retail Inventories is forecast at 0.4% vs. 0.6% m/m prior. Wholesale Inventories is forecast at 0.5% vs. 0.1% m/m prior.
U.S. May FHFA House Price Index is forecast at 0.1% vs. -0.1% m/m prior.
U.S. May S&P Cotality Case-Shiller 20-City Index is forecast at 0% m/m, 1.3% y/y vs. -0.04% m/m, 1.14% y/y in April.
U.S. July Richmond Fed Manufacturing Index is forecast at 6.0 vs. 4.0 prior.
U.S. July Conference Board Consumer Confidence is forecast to rise to 92.0 vs. 91.2.
U.S. Treasury sells $95bn 6-week bills and $44bn 7y notes.
Mood: Risk sentiment continued to improve as investors added to global equities while maintaining steady demand for core sovereign bonds. iFlow Mood improved further to -0.096, suggesting risk appetite is strengthening without a full unwind of defensive positioning.
FX: Defensive currency demand remained intact, with continued inflows into CHF and USD, alongside PEN. Selling was concentrated in GBP, CAD, and COP, while flows across APAC and EMEA currencies were generally light and mixed.
FI: Demand remained firm for major sovereign bonds and Chinese government bonds, reinforcing the ongoing preference for high-quality duration. Selling was selective, concentrated in Peruvian and South African government bonds.
Equities: Buying was strongest across Latin American equities, while flows elsewhere were mixed. Overall, equity allocations continue to rotate from developed markets toward emerging markets, pointing to a gradual improvement in global risk appetite without a broad exit from defensive assets.
“Markets are never wrong; opinions often are.” – Jesse Livermore
“When everybody thinks alike, everybody is likely to be wrong.” – Humphrey B. Neill
French household confidence for July 2026 came in at 86, up two points from June, according to INSEE, but still below its long-term average of 100. The savings climate improved more strongly, rising five points to 123 and remaining above average. Households also reported a better personal financial situation, with both past and expected balances up two points, while views on major purchases improved slightly but stayed weak. Saving intentions increased and saving capacity rose further. Expectations for future living standards improved sharply, unemployment fears fell, and inflation expectations dropped markedly, suggesting a more favorable consumer backdrop despite confidence still being subdued overall. CAC 40 +0.74% to 8,469, EURUSD 0% to 1.1369, 10y OAT -2.6bp to 3.898%.
Spain’s retail sales for June 2026 came in at 0.5% y/y in the seasonally and calendar adjusted series, down 0.8 percentage points from May, while the unadjusted series rose 2.4%. On a monthly basis, retail sales increased 0.3% after seasonal adjustment, easing from the prior month. By distribution channel, online retail posted the strongest monthly gain at 0.5%, while service stations rose 1.6%. Excluding service stations, sales increased 0.2%. By product, food was unchanged and non-food edged up 0.2%. Retail employment was flat year on year, and sales rose in 15 regions but fell in two. IBEX 35 +0.32% to 19,897, EURUSD 0% to 1.1369, 10y Bono -2.3bp to 3.567%.
U.K. shop price inflation eased further in July 2026, with overall shop prices rising 0.9% y/y after 1.2% y/y in June. The BRC said retailers kept prices low through heavy summer promotions, especially in food, snacks, alcohol, clothing and footwear, as they cleared stock. Non-food inflation slowed to 0.2% y/y from 0.6% y/y, while food inflation moderated to 2.2% y/y from 2.4% y/y. Fresh food inflation picked up to 3.1% y/y from 2.8% y/y, but ambient food inflation eased to 1.1% y/y from 1.9% y/y. The report warned that cost pressures are building from higher employment costs, packaging taxes, global instability and climate-related disruption, even as promotions remain key to supporting demand through the summer. FTSE 100 +0.27% to 10,811, GBPUSD +0.076% to 1.3299, 10y gilt -4.2bp to 4.955%.
Australia’s federal and Western Australian (WA) governments will investigate building the country’s first new oil refinery in decades, aimed at strengthening energy security and fuel sovereignty. Prime Minister Anthony Albanese and WA Premier Roger Cook are set to announce an A$4mn pre-feasibility study for a large-scale facility proposed by Perth-based Perdaman. The study is part of a broader A$15bn federal package to secure fuel supply. Australia currently has only two refineries left, in Brisbane and Geelong, after BP shut Kwinana in 2021. The move follows rising concern over supply resilience amid the Middle East conflict, with the Commonwealth saying Australia has 42 days of petrol, 38 days of diesel and 32 days of jet fuel. WA has already appointed a Fuel Supply State Controller and used emergency powers to manage supply information. ASX -0.03% to 5,792, AUDUSD -0.386% to 0.6975, 10y ACGB -3.7bp to 4.961%.
New Zealand’s June 2026 employment indicators showed a modest labor market gain. Seasonally adjusted filled jobs rose 0.1% m/m in June (up 2,728 jobs) to 2.35mn, following May 2026, with primary industries up 0.7%, service industries up 0.1%, and goods-producing industries broadly flat. On a y/y basis, filled jobs increased 0.6% in June 2026 (up 14,327 jobs) versus June 2025. Gains were led by public administration and safety, health care and social assistance, and education and training, while professional, scientific and technical services declined. Regionally, Canterbury, Auckland and Waikato posted the largest increases, while Northland fell. Gross earnings rose 2.4% y/y to $15.8bn, up $368mn from June 2025. NZX 50 +0.08% to 13,862, NZDUSD -0.38% to 0.5774, 10y NZGB +1.3bp to 4.714%.
South Korea’s July 2026 Consumer Sentiment Index stood at 106.8, up 0.2 points from June. Views on current living standards weakened to 93 (-1), while expectations for future living standards improved to 98 (+1). Household income expectations edged up to 101 (+1), with spending unchanged at 110. Sentiment on current domestic economic conditions fell to 84 (-2), while views on future domestic conditions were flat at 92. Prospective housing prices surge +7 points to 127, the highest since September 2021. Inflation expectations eased slightly: the one-year ahead rate fell to 2.7% from 2.8% in June, while the three-year and five-year ahead expectations were 2.6% and 2.6%. KOSPI -10.84% to 6,024, USDKRW +0.452% to 1460.95, 10y KTB -11.5bp to 4.33%.
Singapore’s HDB said the 15-month wait-out period for private residential property owners and ex-owners buying non-subsidized HDB resale flats without an HDB loan is removed immediately. The policy had been introduced in September 2022 to curb demand and support affordability. HDB said the resale market has stabilized, citing two straight quarters of price declines in 2026: -0.1% q/q in Q1 2026 and -0.3% q/q in Q2 2026, after five quarters of subdued growth in Q4 2024–Q4 2025. The move aims to better support buyers while keeping public housing accessible. Existing exemptions for Singaporeans aged 55 and above buying smaller flats remain relevant, while the 30-month wait-out period still applies for subsidized flats, Executive Condominiums, or purchases with an HDB loan. STI -0.14% to 5,613, USDSGD -0.186% to 1.2925, 10y SGB -4.5bp to 2.416%.
Hong Kong’s CSOP Asset Management said it will adopt a flexible leverage framework for 12 single-stock leveraged and inverse ETFs, including products tracking Samsung Electronics and SK Hynix, effective August 3. The change follows updated guidance from the Hong Kong Securities and Futures Commission aimed at reducing tracking difference risk and smoothing volatility in turbulent markets. Under the new structure, leverage will no longer be fixed and can be adjusted daily up to 2x, or as low as 1.1x in extreme conditions. CSOP will rename all 12 products to reflect the new framework and reiterated that they are designed for short-term trading, not for holding longer than one day. The move comes amid heightened scrutiny of leveraged ETFs, which have drawn heavy retail inflows and concerns over their role in amplifying volatility in South Korean chip stocks. Hang Seng +0.11% to 25,234, USDHKD -0.002% to 7.842, 10y HKGB -1.2bp to 1.417%.