Market Movers: Anticipation
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Geoffrey Yu
Time to Read: 6 minutes
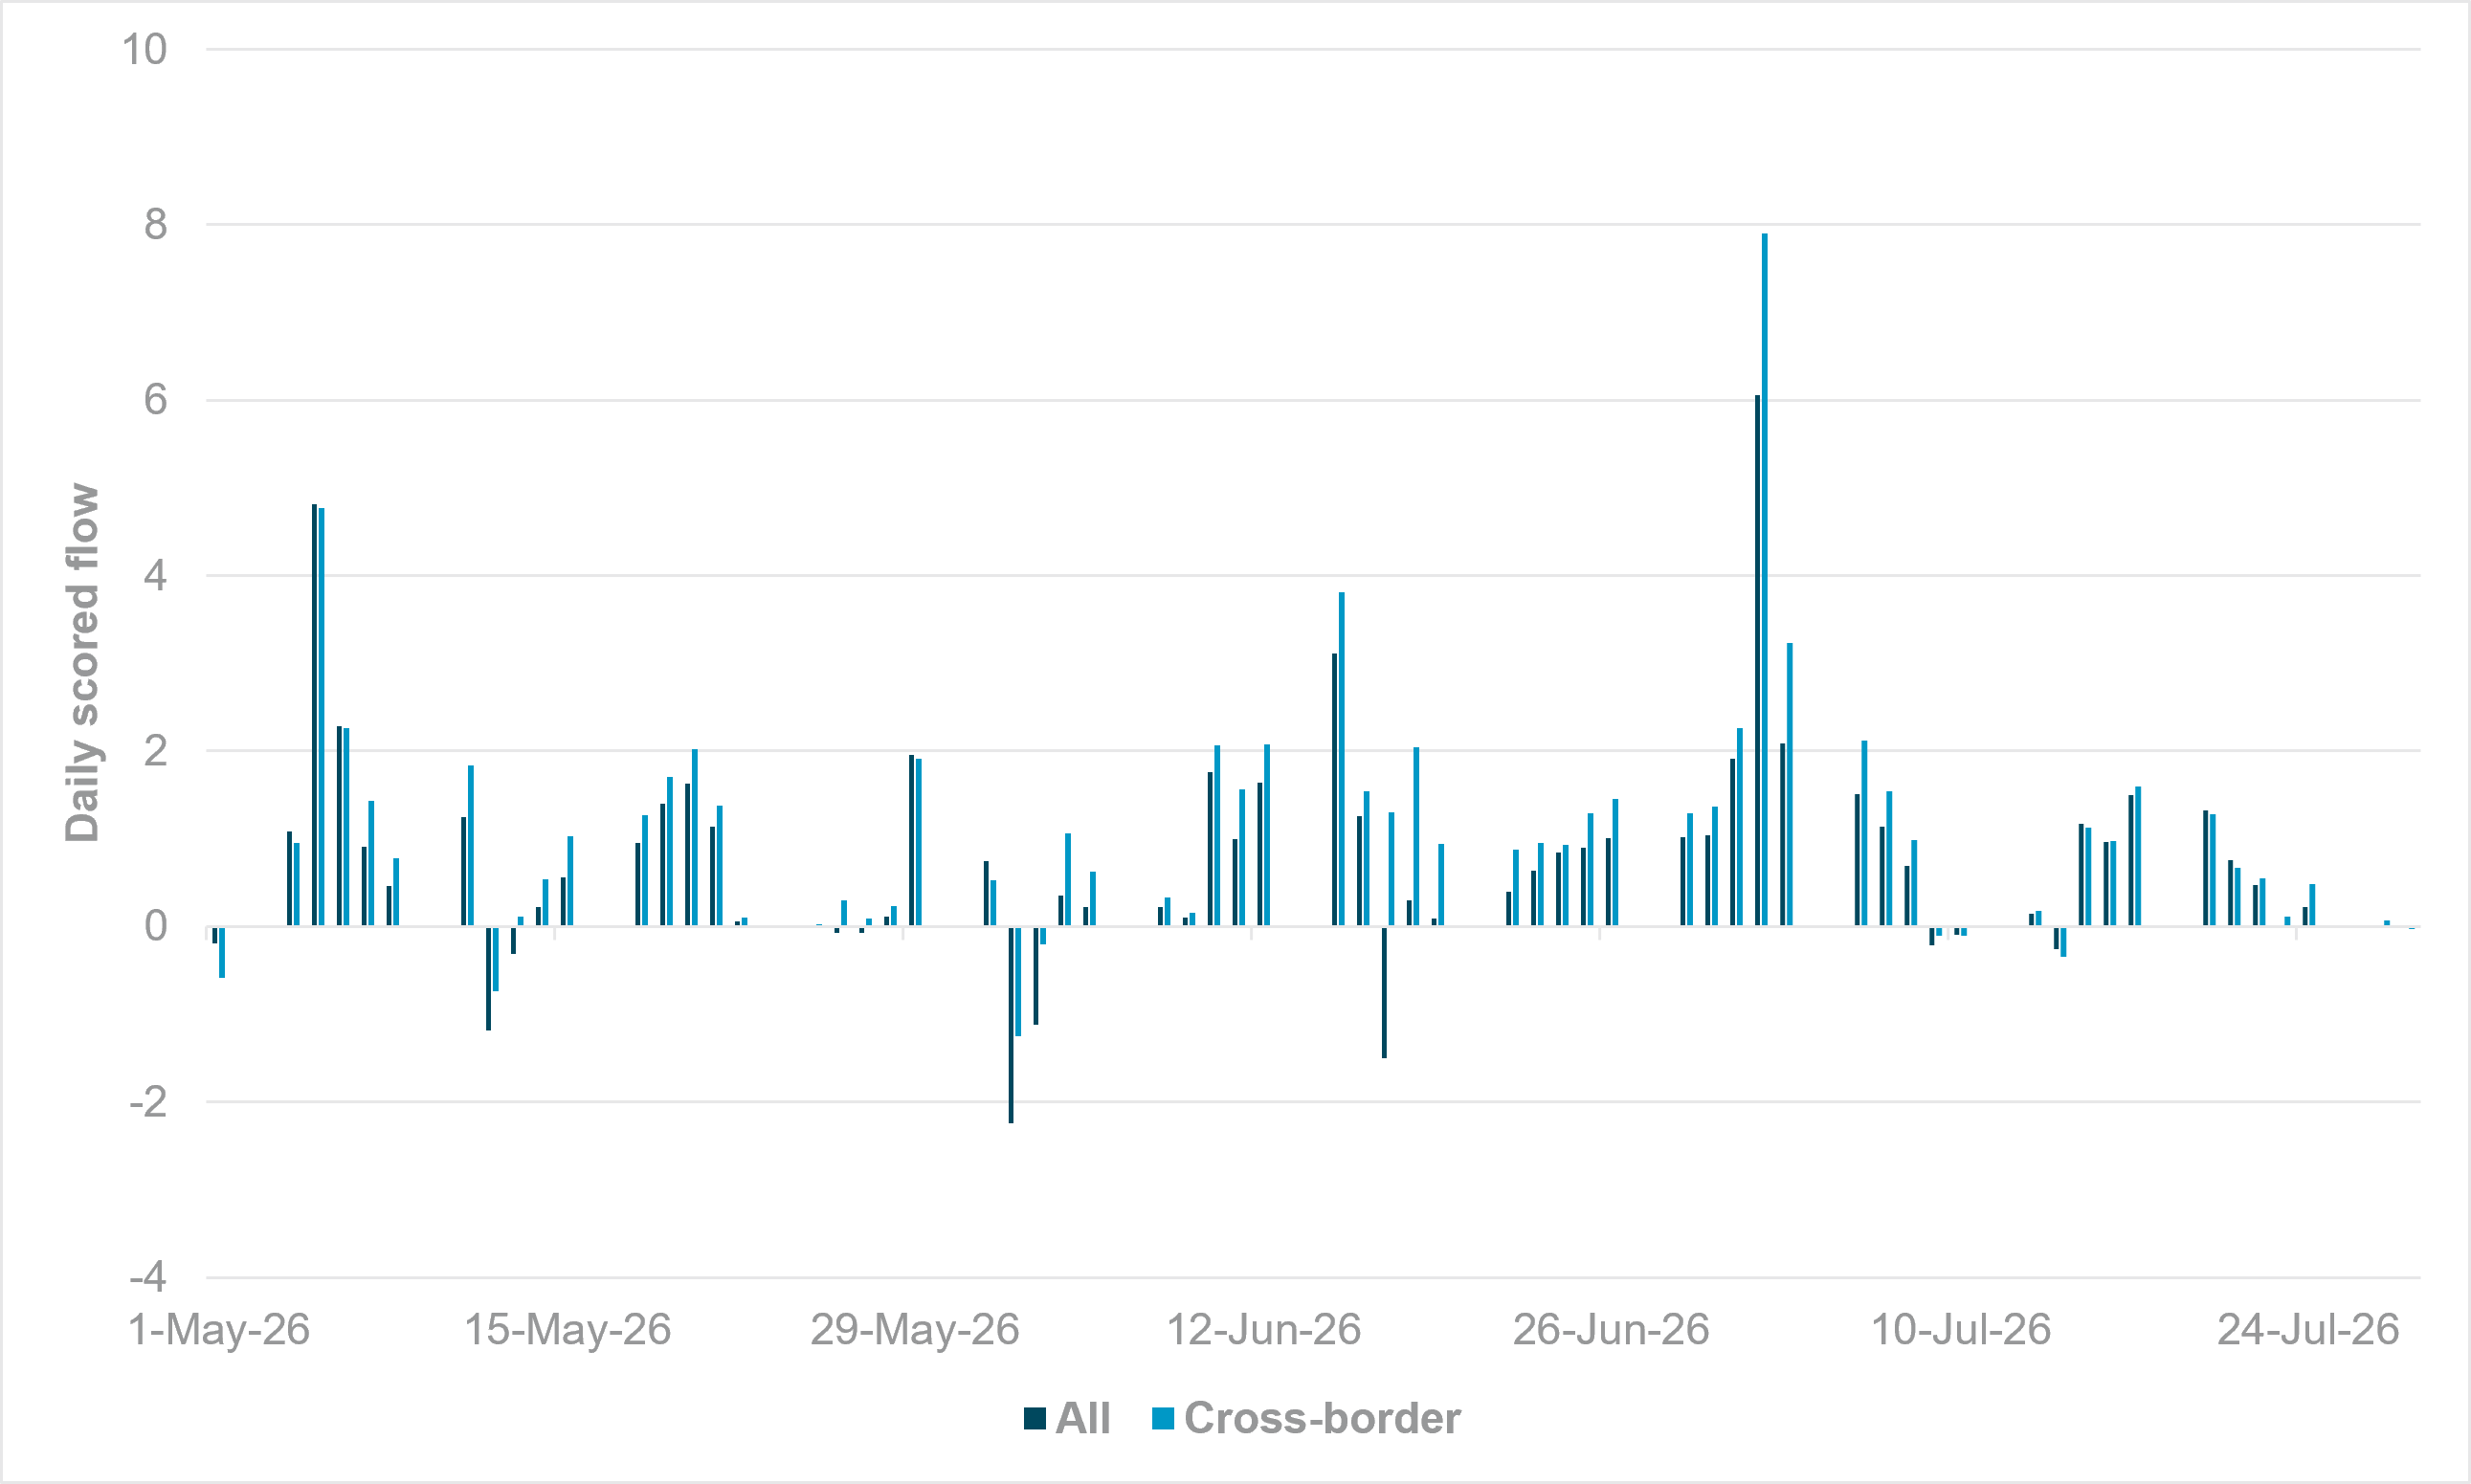
USD flow momentum softens ahead of FOMC
Source: BNY
The dollar enters the FOMC with strong recent demand but increasingly stretched positioning. Cross-border buying and late-July spot demand remain supportive, but month-end rebalancing, light hedge ratios, and softer cash demand raise the bar for another leg higher. A clearly hawkish Fed surprise is now needed to restart broad USD purchases.
Recent dollar flows have seen the strongest buying phases on record, but they end the month under heavy rebalancing pressure, especially through equities. Price action is already struggling ahead of the Fed, and dollar purchases are fading even as markets price some risk of a hike. The EUR offers a useful warning: even a notably hawkish central bank may not support its currency when positioning is stretched. The bar for the Fed to restart broad USD buying is therefore very high. The recent buying phase has already absorbed much of the available positive policy signal.
Cross-border flows continue to anchor overall USD demand, and their lead in average flow scores remains clear. Dollar hedge removal and fresh longs were strongest in June, when the gap between cross-border and local demand was also widest. Even so, interest is softening into month end. For foreign investors, the lack of hedging on U.S. assets is beginning to look excessive. Month-end rebalancing should generate more hedge demand, although weaker equities and fixed income may already be reducing exposures and mechanically lifting hedge ratios. The adjustment may therefore come through both active hedging and passive exposure reduction.
Decision risk: Markets are waiting on a genuinely live Fed decision. A hold remains the base case, with futures implying roughly a 35% probability of a hike. That’s still an unusually wide distribution for decision day. A surprise increase would likely be cross-asset bearish, pushing front-end yields and the dollar higher while adding pressure to equities and credit. Even a hold may not provide full relief if dissents or Fed Chair Kevin Warsh’s guidance keep September firmly in play.
No room for error: Semiconductor sentiment remains weak, with further capitulation in South Korea and continued pressure across the regional chip complex. Tightening is already being delivered through equity losses, higher volatility and leveraged-position unwinds, leaving markets with limited capacity to absorb an additional policy shock. Microsoft and Meta report today, followed by Amazon tomorrow; the focus will be on AI capital expenditure, monetization trends, and whether management guidance can arrest the broader semiconductor selloff.
Gulf interruption: The brief pause in hostilities has ended. Iran launched missiles toward U.S. forces in Jordan, while U.S. and Saudi forces struck Iran-backed militias in Iraq. Brent rose more than 3%, reviving the inflation channel. The move is unhelpful but remains secondary for sentiment: the dominant drivers are now the Fed, AI valuations, and positioning rather than geopolitics alone.
Burden of proof: Bulls are anticipating several forms of good news at once: a Fed hold, reassuring guidance, and strong Microsoft and Meta earnings that justify elevated AI spending. The risk is that none arrives decisively. SK Hynix has already shown that strong growth is no longer enough when expectations and positioning are stretched.
Bottom line: A hold remains most likely, but it may not resolve the uncertainty. Confirmation of a September hike would probably generate only a muted rise in yields, while limited guidance could prolong volatility. Anticipation is supporting patience, not confidence; disappointment from the Fed or earnings could quickly extend the de-risking.
The Fed is expected to hold rates today, but the decision is finely balanced, and the market reaction will depend less on the hold itself than on how much Warsh signals about September. Markets already price a strong chance of at least one hike by then, so a clearly hawkish hold may lift yields only modestly because expectations are partly embedded. The bigger risk is ambiguity: if the Fed gives little guidance, rates and FX volatility could rise as investors wait for the next CPI and PCE releases to determine whether energy-driven inflation is broadening. A surprise hike would be more disruptive, likely triggering a bearish cross-asset reaction as markets reassess the policy path. S&P Mini +0.18% to 7,479, DXY -0.065% to 101.352, 10y UST +0.5bp to 4.61%.
The U.S. said it intercepted an Iranian ballistic missile attack on military bases in the Middle East, ending a brief lull and heightening the risk of renewed escalation. Oil prices have reacted, but we don’t see the moves materially affecting today’s Fed decision. U.S. Central Command said IRGC forces launched multiple missiles from Iran in a surprise attack, all of which were intercepted, while U.S. and Saudi forces also struck Iran-backed militants in Iraq after 30 drone attacks in the prior 72 hours. Iran’s state media said the IRGC fired missiles at a U.S. airbase and command center in response to U.S. actions. President Trump said diplomacy with Tehran may still progress, but reiterated threats of force. Israel said it backs Trump’s chosen path, while Omani–Iranian talks reportedly seek a shipping deal to reopen formal U.S.–Iran negotiations. Brent +3.604% to 87.12, WTI +3.483% to 82.02, Omani Crude -6.703% to 76.7, Dubai Crude -0.816% to 76.286.
South Korean stocks saw a brutal selloff on Wednesday as the KOSPI plunged almost 13% to an intraday low below 5,300, triggering a circuit breaker for a second straight session and marking the first back-to-back halt on the benchmark and Kosdaq markets. Heavy selling by retail and foreign investors hit semiconductor shares hardest, with Samsung Electronics and SK Hynix both dropping sharply. SK Hynix’s earnings beat did little to ease worries over AI valuations and spending. The decline followed Tuesday’s global chip rout and was intensified by concerns over Chinese competition and weaker sentiment, leaving the KOSPI far below its June peak. KRW has strengthened materially due to hedge unwinding, but a near-term floor may emerge. KOSPI -5.98% to 5,663, USDKRW -0.19% to 1450.45, 10y KTB -3.8bp to 4.292%.
Japan’s Government Pension Investment Fund (GPIF) hired active domestic bond funds for the first time in five years, appointing three firms in May – Asset Management One, Mitsubishi UFJ Trust & Banking, and Sumitomo Mitsui Trust Asset Management – to manage Japanese bonds. The move aims to improve expertise amid heightened volatility in Japan’s debt market; GPIF is seeking benchmark-beating returns and better diversification of risk assets. GPIF’s domestic bond portfolio has been under pressure from falling bond prices and market swings, losing 5.1% in the year ended March 31, even as total assets returned 16.5%. The decision comes as investors face inflation, higher government spending, and a BOJ tightening cycle viewed by some as too slow. Officials have also urged GPIF to invest more in domestic assets, which in time will support the JPY. Nikkei -1.49% to 61,434, USDJPY +0.245% to 163.54, 10y JGB -2.7bp to 2.758%.
The FOMC is expected to keep rates on hold at 3.50%–3.75%, but uncertainty remains elevated, with markets pricing in about a one-third chance of a hike. Warsh speaks at 2:30 p.m. ET.
U.S. Treasury sells 17-week bills and $30bn 2y FRNs.
Mood: iFlow Mood declined slightly to -0.102, indicating a shift back to defensive positioning after several consecutive days of more risk-on sentiment.
FX: Flows were balanced with demand for safe-haven currencies like CHF and USD. EUR and PEN also saw inflows. CAD, COP, and NOK faced selling pressure.
FI: Demand was strong for G10 fixed income with inflows into European, Chinese, and Japanese sovereign bonds. Investor sentiment was negative toward EM bonds with Czech, Peruvian, and South African bonds seeing outflows.
Equities: Investor demand for LatAm equities continued most notably with Colombian stocks, while flows in the rest of the world were mixed. U.K. and European equities both faced selling pressure.
“The Federal Reserve … is in the position of the chaperone who has ordered the punch bowl removed just when the party was really warming up.” – William McChesney Martin Jr, Fed Chair 1951–1970
“Monetary and fiscal restraints are never easy – they are only essential.” – Paul Volcker, Fed Chair 1979–1987
U.K. lending and money data for June showed a firmer pick up in household borrowing and broad money growth. Net borrowing of mortgage debt by individuals rose to £7.7bn from £3.3bn in May, while net mortgage approvals for house purchases increased to 58,200, though still below the recent six-month average. Consumer credit edged up to £1.8bn, led by higher credit card borrowing. Private nonfinancial corporations repaid £2.5bn on net after borrowing in May, even as bank loans rose. The M4ex money stock increased to £14.6bn, and M4Lex jumped to £39.1bn, driven mainly by strong borrowing from nonintermediate other financial corporations and continued household and corporate lending. FTSE 100 +0.36% to 10,910, GBPUSD +0.083% to 1.33, 10y gilt +3bp to 4.974%.
Australia’s headline CPI rose 3.8% y/y in June 2026, unchanged from May. Underlying inflation, measured by the trimmed mean, was steady at 3.6% y/y, also flat on the previous month. Housing was the largest annual contributor, up 6.8%, reflecting higher electricity costs and new dwelling prices. Food and nonalcoholic beverages, and recreation and culture were the next biggest contributors, both up 3.3%. Transport inflation eased sharply to 0.1% y/y from 3.3% in May, as automotive fuel prices fell for a third straight month amid lower global oil prices and earlier fuel excise relief. June quarter CPI rose 0.6% q/q, while the trimmed mean increased 0.8% q/q. ASX +0.78% to 5,839, AUDUSD -0.173% to 0.6953, 10y ACGB -4.4bp to 4.918%.
South Korea’s major retailers reported solid growth in H1 2026 and June. In H1 2026, total sales rose 7.3% y/y, with offline sales up 6.2% and online sales up 8.1%. The retail sector benefited from improved consumer sentiment, higher foreign tourist spending, and strong department store performance, while hypermarkets and SSMs remained weak. Department stores surged 20.1%, rebounding from 0.5% growth in H1 2025, and convenience stores returned to growth at 3.7% after a 1.0% decline. In contrast, hypermarkets fell 7.3% and SSMs dropped 6.6%. In June, total sales increased 9.5% y/y, led by online growth of 11.7% and offline growth of 6.4%. Department stores rose 22.2% and convenience stores 5.1%, while hypermarkets (-10.5%) and SSMs (-10.8%) stayed under pressure. Gaining categories included appliances/culture and overseas luxury brands. KOSPI -5.98% to 5,663, USDKRW +0.332% to 1448.4, 10y KTB -3.8bp to 4.292%.
Singapore announced a new S$900mn support package to help households and firms manage cash flow pressures amid the Middle East conflict, adding to April’s S$1bn package. The measures are more targeted at companies facing supply chain disruptions, energy costs and weaker buffers. For SMEs with at least one local employee, the government will provide a one-off cash grant of S$500 per local employee, capped at S$2,500 per company; eligible sole proprietorships, partnerships and LLPs with a local owner but no local employees will get S$500. The grant will be disbursed in November, with no application required. Separately, the Enterprise Financing Scheme will be enhanced from September to March next year, lifting the government’s risk share on SME Working Capital Loans and Project Loans to 70% from 50%, and expanding Project Loans to domestic projects for local construction firms. STI +1.11% to 5,678, USDSGD +0.124% to 1.2919, 10y SGB -1.4bp to 2.403%.