Market Movers: Anticipation
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 6 minutes
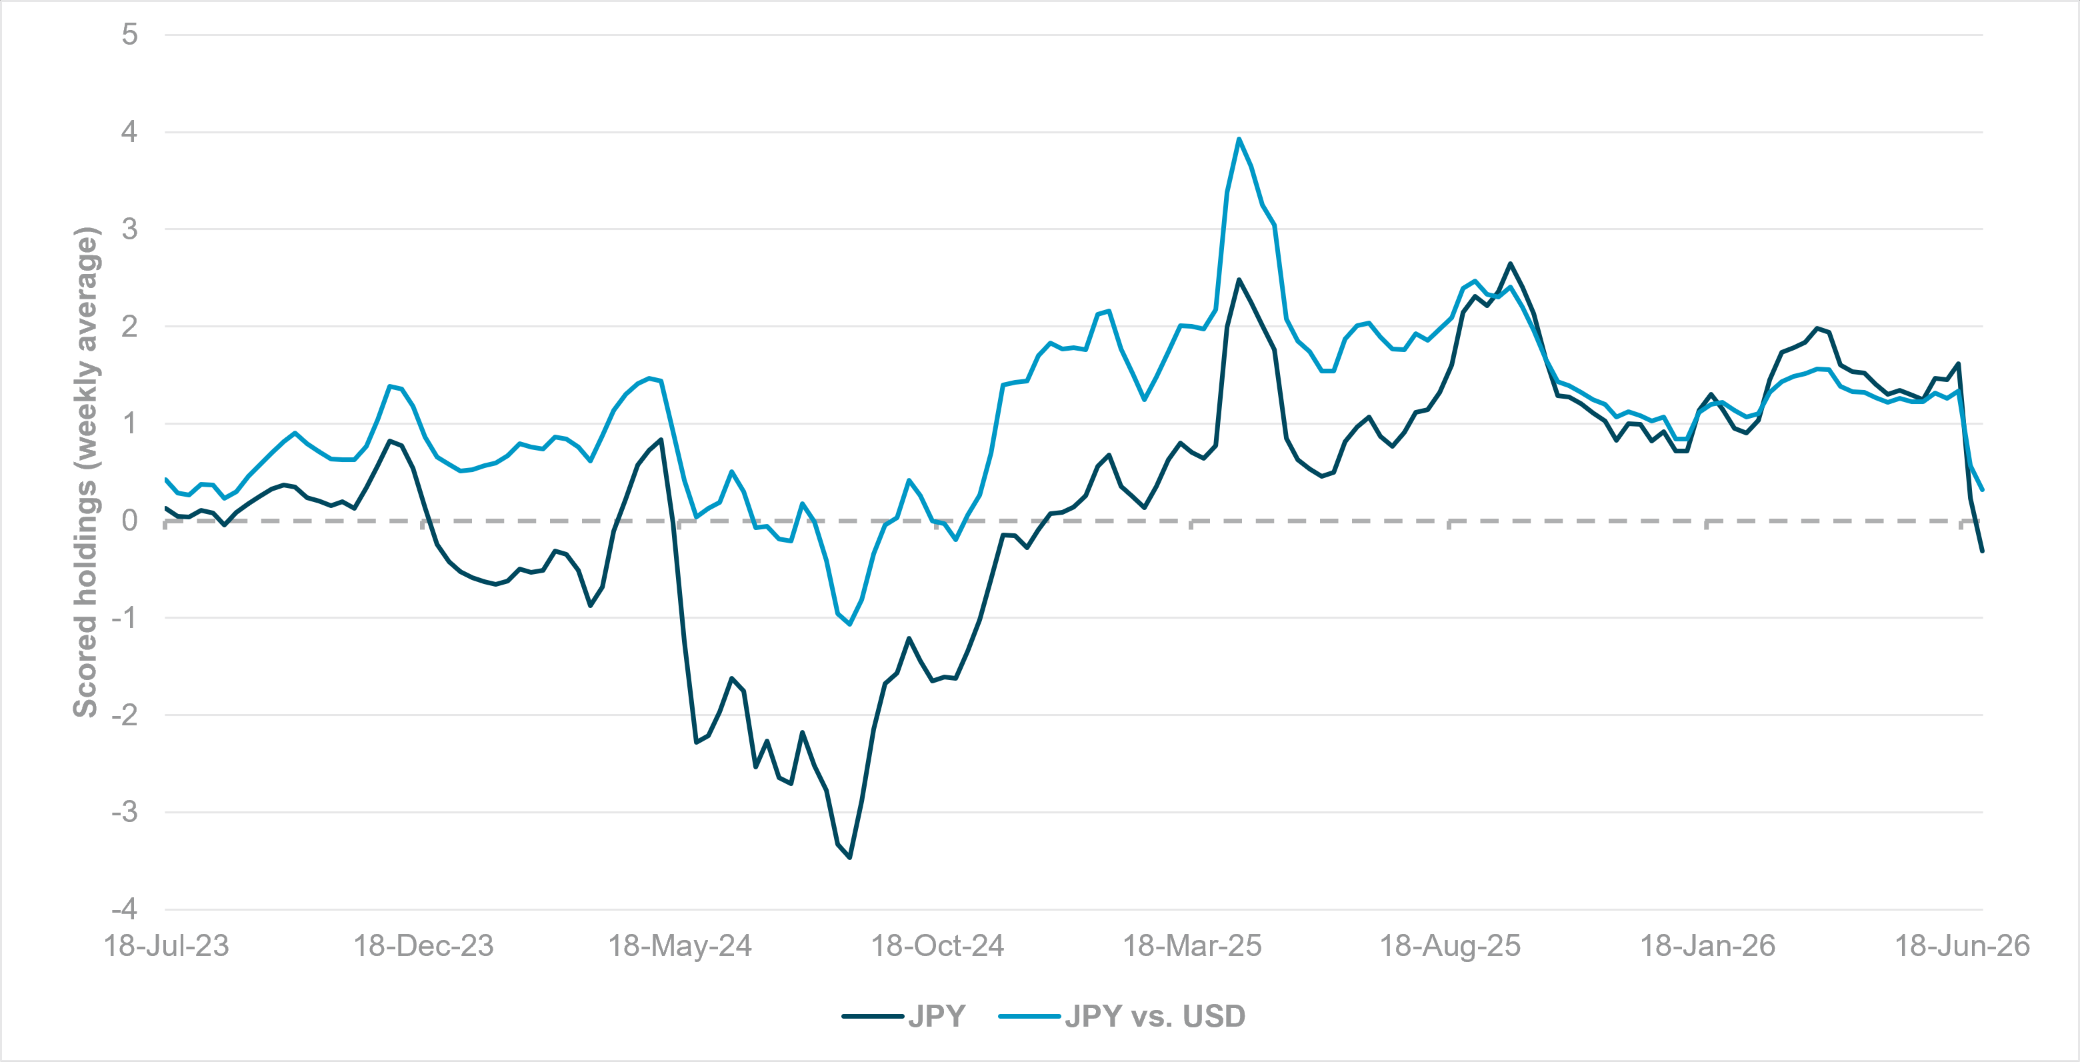
JPY turns underheld, led by cross-JPY selling
Source: BNY
iFlow data show that cross-border clients are now underweighting JPY on an aggregate basis for the first time since Q4 2024. As USDJPY climbed, fears of official intervention kept hedge ratios unusually low, with many investors willing to absorb carry costs given the yen’s perceived undervaluation and expectations of Fed easing. That backdrop has now changed. Despite repeated intervention, markets are increasingly questioning the Ministry of Finance’s willingness and ability to defend the currency. At the same time, expectations of further BoJ tightening have faded just as markets have repriced the Fed toward a more hawkish path.
While underweight USDJPY positions are beginning to normalize, our data suggest the pair remains modestly underheld. The broader decline in aggregate JPY positioning has instead been driven by renewed demand for JPY-funded crosses, signaling that investors are once again rebuilding carry exposure. This supports our view that the near-term environment favors higher-yielding currencies after a difficult quarter. However, we expect the carry recovery to be more selective than in 2024, when aggressive Fed easing fueled a much larger expansion in JPY-funded cross-positions. Today’s policy backdrop is fundamentally different.
Fed Chair Kevin Warsh’s comments in Sintra yesterday provided further reassurance to markets concerned about an overly hawkish Fed, but overnight trading was a reminder that valuations and positioning remain the more immediate source of volatility. Heavy selling in semiconductor stocks hit markets across South Korea, Japan and Taiwan as investors questioned whether the scale of AI-related capital spending can continue to justify recent gains, while Chinese tech indices also suffered sharp losses. The move came as the OECD warned that South Korea’s growing dependence on semiconductor exports is increasing the economy’s exposure to swings in the global technology cycle, reinforcing concerns around concentration risk. Meanwhile, USD/JPY fell sharply after Reuters reported that Japanese authorities are adopting a more unpredictable approach to yen intervention, leaving investors reluctant to test policymakers in thin liquidity.
Sintra is unlikely to have left markets much wiser on Europe’s growth outlook, but the increasingly visible split within the ECB over the path of further tightening points to an easing in financial conditions. Any reduction in borrowing costs must now be matched by faster structural reform, and Germany has finally delivered some positive news by agreeing a long-delayed package of tax cuts and economic reforms. Europe’s productivity and competitiveness challenges remain structural, but the bar is now so low that even incremental policy progress could support rotation back into European assets.
Attention now turns to today’s non-farm payrolls ahead of the long U.S. holiday weekend. Labor market resilience is largely priced in, but markets remain wary of upside surprises that could revive expectations of a stronger Fed response. For all the focus on supply-side risks stemming from the Gulf conflict, the future of the USMCA and the global semiconductor race, labor remains the variable to which central banks react most strongly. The euro area has delivered resilient labor markets alongside improving inflation dynamics throughout much of Q2; today’s U.S. data will determine whether that narrative can extend across the Atlantic.
Germany’s ruling coalition has reached an agreement on a reform package after seven and a half hours of talks, with Chancellor Friedrich Merz’s conservative bloc and the Social Democrats expected to unveil the details at a news conference on Thursday. The deal is intended to strengthen the social security system, reduce taxes for low and middle-income households and support efforts to revive the economy after a long period of weak growth. Income tax reform was the main sticking point, with financing still unresolved, while bureaucracy reduction reportedly advanced more smoothly. The package is politically significant after an earlier attempt failed and comes as coalition support has weakened in opinion polls. DAX +0.37% to 25133, EURUSD +0.361% to 1.1418, 10y Bund +3.6bp to 2.914%
JPY jumped overnight on reports that Japanese authorities are shifting their yen defense strategy, reported Reuters, with the Ministry of Finance moving away from explicit warning signals and toward a more unpredictable approach aimed at catching speculators off guard. Instead of highlighting a clear intervention threshold, officials are said to be using silence and targeted action to raise the cost of betting against the currency, while the BoJ continues to stress the inflationary risks of a weak yen. The move follows Japan’s record ¥11.7tn intervention earlier this year, which only briefly lifted the currency before it resumed falling toward four-decade lows. Market attention now centers on U.S. jobs data, Fed expectations and whether Washington would support renewed intervention. Nikkei -2.47% to 68733, USDJPY -0.929% to 161.07, 10y JGB +7.4bp to 2.785%.
The RBNZ has said it will not add an extra member to its Monetary Policy Committee before the November election, leaving the panel with three internal and three external members. The central bank said MPC appointments are made by the Minister of Finance, and the governor, as chair, is not seeking an additional internal appointment ahead of the election period. The move follows the appointment of Angus McGregor as assistant governor for financial stability, a role that in the past was part of the MPC’s remit. The committee next meets on July 8, after a split 3-3 vote in May, when external members backed a rate hike and the hold decision was decided by the governor’s tiebreak. NZX 50 -0.21% to 13582, NZDUSD +0.388% to 0.5694, 10y NZGB +4bp to 4.448%.
The OECD’s 2026 Economic Survey of Korea has warned that South Korea’s heavy reliance on semiconductor exports, while a key growth driver, is increasing exposure to external shocks, output volatility and tax revenue swings. It noted that export and investment growth accelerated in early 2026, supported by the AI boom, but said this dependence is also creating strategic vulnerabilities. The report urged the government to use fiscal policy to support domestic demand in the near term, while consolidating over the medium term to preserve fiscal health amid rapidly rising aging-related spending pressures. It also called for a stronger fiscal framework, later pension eligibility, labor market reform and broader tax reform, especially in property taxation. The OECD said domestic demand inflation remains subdued, though South Korea should remain alert to energy-price volatility and keep inflation expectations anchored. KOSPI -7.89% to 7648, USDKRW -0.133% to 1548.65, 10y KTB +13.5bp to 4.205%.
U.S. June change in non-farm payrolls is forecast to ease to 115k vs. 172k. The change in private payrolls is forecast to ease to 115k vs. 120k, and the change in manufacturing payrolls to ease to 3k vs. 7k.
U.S. June average hourly earnings are forecast at 0.3% m/m, 3.5% y/y vs. 0.3% m/m, 3.4% y/y in May; average weekly hours are forecast to hold at 34.3 vs. 34.3.
U.S. June unemployment rate is forecast to hold at 4.3% vs. 4.3%, with the labor force participation rate expected to hold at 61.8% vs. 61.8%.
U.S. initial jobless claims are forecast to rise to 218k vs. 215k.
U.S. May factory orders are forecast to fall to -2.0% m/m vs. 4.8% m/m; factory orders ex transportation are forecast at 1.0% vs. 1.3% m/m.
U.S. May final durable goods orders are forecast to hold at -4.5% m/m vs. an estimate of -4.5% m/m and 8.5% in April, while final durable goods ex transportation are forecast to hold at 1.3% m/m vs. an estimate of 1.3% m/m and 1.4% in April.
U.S. May final capital goods orders non-defense ex-air are forecast to hold at 1.6% m/m vs. 1.6% m/m; final capital goods shipments non-defense ex-air are also out, after an April reading of 0.3% m/m.
Canada June S&P Global Manufacturing PMI is out; the May reading was 52.9.
Central bank speakers: the Fed’s Mary Daly speaks in a moderated conversation, BoE rate-setter Catherine Mann speaks in London, the ECB’s Piero Cipollone speaks in Milan.
U.S. Treasury sells 4-week bills and 8-week bills.
Mood: iFlow Mood narrowed further to -0.10, driven by slower global equity selling, partly offset by a modest increase in selling of core government bonds.
FX: There were substantial outflows from CAD, JPY and MYR, while flows across the rest of the iFlow universe remained light. APAC and EMEA were biased toward outflows, while LatAm flows were mixed.
FI: Strong demand for Hungarian, Canadian and Eurozone government bonds, along with U.K. gilts, offset by heavier selling in LatAm, Philippine and Japanese government bonds.
Equities: Broad selling across major G10 equity markets, led by South Korea and South Africa, with additional outflows from Taiwan. Selective buying was concentrated in India, Switzerland, Colombia and Hungary.
“The American worker is as good and productive as any in the world.” – Ronald Reagan
“The best customer of American industry is the well-paid worker.” – Franklin D. Roosevelt
Euro area unemployment came in at 6.2% in May, which was unchanged m/m and down slightly vs. 6.3% a year earlier. The EU rate was 5.9%, also stable m/m and down from 6.0% in May 2025. Eurostat estimated an unemployment count of 10.986 million in the euro area and 13.163 million in the EU. Compared with April, unemployment fell by 55k in the euro area and 40k in the EU, while y/y it decreased by 158k and 82k, respectively. Youth unemployment remained elevated, with the euro area rate at 14.7% and the EU rate at 15.2%. Euro Stoxx 50 +0.24% to 6298, EURUSD +0.361% to 1.1418, BBG AGG Euro Government High Grade EUR +0.3bp to 3.163%.
Italian labor market data for May showed a slight m/m weakening as employment, unemployment and activity moved in different directions. The number of employed people fell by 0.1%, or 22,000, to 24.336 million, driven by a drop in fixed-term employees, while permanent employees and self-employed workers increased. The employment rate edged down to 63.0%. Unemployment also decreased by 1.7%, or 22,000, pulling the jobless rate down to 5.0% and the youth rate to 15.1%. In contrast, inactivity rose by 59,000 to 33.6%. On a y/y basis, employment was up 0.9% and unemployment was sharply lower. FTSE MIB +0.85% to 52044, EURUSD +0.361% to 1.1418, 10y BTP +4.4bp to 3.709%.
Spanish unemployment figures for June showed registered joblessness falling by 28,739 m/m to 2,291,982, the first time it has been below 23 million since January 2008. On a y/y basis, unemployment decreased by 113,981, or 4.74%. The drop was driven mainly by services, with falls also registered in industry, construction and agriculture, while the “no previous employment” group increased. Unemployment fell faster among women than men, and the number of unemployed people under 25 dropped to a record low of 159,800. Joblessness decreased in 11 autonomous communities, led by Andalusia, Galicia, and Castile and Leon. IBEX 35 +0.66% to 19487, EURUSD +0.361% to 1.1418, 10y Bono +3.9bp to 3.413%.
Swiss inflation slowed to 0.5% y/y in June, from 0.6% in May, marking the first decline in eight months. The reading matched the Bloomberg survey expectations and showed that lower oil-related costs are continuing to feed through to the domestic economy. Rising prices for vegetables, hotels and car rentals were offset by cheaper flights, heating oil and diesel, while core inflation, excluding volatile items such as energy, remained unchanged at 0.3%. The measure remains within the SNB target range of 0-2%, and officials still expect a mild acceleration later this year with no material shift in medium-term inflation pressures. SMI +0.9% to 14241, EURCHF -0.277% to 0.91859, 10y Swiss GB +1.9bp to 0.322%.
Australia recorded a seasonally adjusted international trade in goods deficit of AU$3.018bn in May, reversing the April surplus and marking a m/m fall of AU$4.401bn. Exports dropped by AU$3.224bn, or 6.9%, led by a sharp fall in non-monetary gold and weaker metal ores and minerals. Imports rose by AU$1.177bn, or 2.6%, as higher purchases of non-industrial transport equipment, civil aircraft and confidentialized items pushed debits up. Rural goods exports rose modestly, but this was outweighed by broad weakness in non-rural shipments. The result was the second seasonally adjusted trade in goods deficit of 2026 and the first original-basis deficit since January 2018. ASX +0.36% to 5655, AUDUSD +0.233% to 0.6909, 10y ACGB +3.5bp to 4.821%.
New Zealand’s building consent data for May showed a mixed picture. The seasonally adjusted number of new dwellings granted consent fell 4.0% m/m in May, after rising 11% m/m in April. On a y/y basis, the actual number of new dwellings granted consent rose 19% y/y to 39,737 in the year ended May 2026. The monthly total was 3,801 new consented dwellings, led by stand-alone houses and townhouses/flats/units. By region, consent issuance was strongest in Canterbury and Auckland over the year. The annual value of non-residential building consents declined by 4.0% y/y to NZ$8.7bn, with offices, education and storage buildings the largest categories. Overall, the data suggest residential approvals remained elevated versus a year earlier despite a softer monthly outcome. NZX 50 -0.21% to 13582, NZDUSD +0.388% to 0.5694, 10y NZGB +4bp to 4.448%.
South Korea’s consumer price index rose 0.1% m/m and 3.2% y/y in June, accelerating from 0.5% m/m and 3.1% y/y in May. The core index excluding food and energy was unchanged m/m and up 2.5% y/y, in line with the previous month. Price pressures were led by furnishings, household equipment and routine maintenance (+1.2% m/m), food and non-alcoholic beverages (+0.4%), alcoholic beverages and tobacco (+0.3%) and health (+0.2%). Upward moves were partly offset by declines in transport (-0.6% m/m), recreation and culture (-0.2% m/m) and communication (-0.1% m/m). Housing, water, electricity, gas and other fuels were flat, suggesting subdued utility costs. Overall, inflation firmed up modestly in June, with broad-based but mixed sector dynamics and stable core inflation. KOSPI -7.89% to 7648, USDKRW -0.133% to 1548.65, 10y KTB +13.5bp to 4.205%.