Market Movers: Acceleration
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 5 minutes
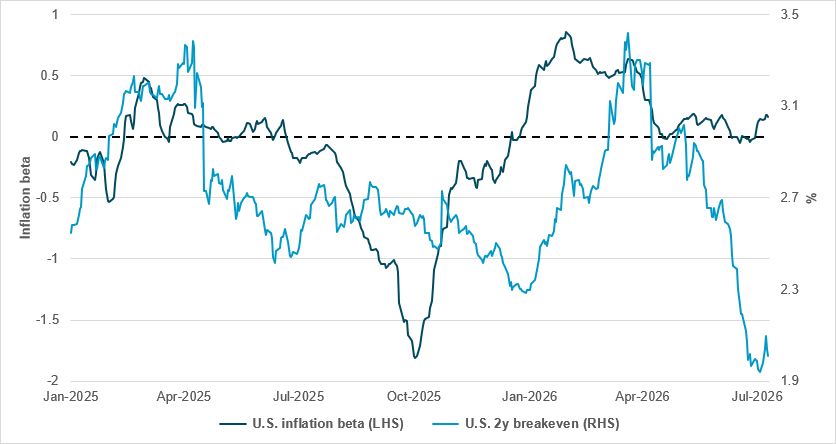
Inflation hedging continues in U.S. equity flows
Source: BNY, GPIF
Despite the softness in U.S. equities, our flow data suggest that U.S. investors remain cautious on the inflation outlook, and yesterday’s comments by Fed Governor Christopher Waller underscored the risks ahead. Our iFlow equity inflation style indicator captures this by estimating the correlation between industry group returns and changes in the two-year breakeven inflation rate, then comparing that relationship with accelerated flows into the same sectors. A higher regression beta signals stronger surge flows into industries with the greatest breakeven sensitivity. The inflation beta was highest in U.S. equities in Q1 this year, when markets were focused on “debasement” risk and real rates looked too low, highlighting the importance of policy stance in driving equity allocations. Supply shocks also matter, but unless there is clear evidence that they will force a sustained shift in policy, the asset allocation response will likely be less forceful.
Inflation protection flows are too strong for where breakevens are trading. Alignment between equity flows and inflation-defensive strategies is back near the highs seen in April, even as two-year breakeven inflation is close to its lows. Either the market is materially underpricing inflation risk or equity allocations will need to rotate away from inflation protection. That said, current flows and positioning remain well below the highs seen during the first weeks of the conflict.
Risk convergence is becoming risk acceleration. Oil is rising again, and Hormuz remains the route through which military risk becomes an inflation problem as the U.S. CPI announcement looms. We are not yet dealing with a confirmed supply break, but the direction of travel matters: each fresh escalation raises the probability that energy risk will migrate from headlines into breakevens, yields and multiples. Soft equity sentiment is hoping for a lift from U.S. bank earnings; the next test is whether weakness will spill into less-concentrated sectors in the U.S. and APAC.
China adds another acceleration point, with exports surging. While that supports parts of Asia’s industrial complex, it also reinforces the surplus problem. Strong exports without a convincing domestic demand recovery mean more pressure on trading partners, more trade friction risk and less relief for economies facing import competition. Europe is feeling the pain: German Chancellor Friedrich Merz called for “currency dialogue” with China yesterday, and pressure on Brussels to respond will likely keep building.
Central bankers are getting harder to disregard, from ECB hawks to the Fed’s Christopher Waller. This is not a sudden hawkish turn: inflation risks are becoming more visible. Higher oil, resilient goods supply and sticky services inflation make aggressive easing expectations harder to justify. Duration needs cleaner evidence of disinflation, not just weaker sentiment.
Bottom line: Kevin Warsh’s testimony is the immediate test. We still do not see a hike, but the bar for dovish reassurance is rising as oil, trade pressure and sticky inflation risks build. Markets should remain protected against hawkish central bank communication and inflation surprises, even if the policy destination remains delayed easing rather than renewed tightening.
Brent crude rose above $85/barrel after renewed U.S.-Iran tensions revived supply risk concerns around the Strait of Hormuz, a route that historically carries about a fifth of global oil flows. President Trump escalated pressure on Tehran on Monday by reinstating a U.S. blockade on Iranian ships transiting the strait and proposing a 20% reimbursement charge on other cargo moving through the waterway. The move follows recent U.S. military strikes on Iranian naval and coastal targets, which Central Command said were aimed at degrading Tehran’s ability to attack commercial shipping. Iran said its agreement with Washington has entered a crisis phase and warned that the blockade could trigger further attacks. Brent +4.274% to 86.86, WTI +3.264% to 80.69, Omani crude +6.584% to 82.57, Dubai crude +6.091% to 73.425.
Japan Finance Minister Satsuki Katayama has said the government is considering changes to the tax-free NISA savings program that could include Japanese government bonds, while also signaling that the GPIF public pension fund may revise its portfolio if needed. The comments come as authorities seek to draw more household savings into domestic assets and support the yen, which remains near a 40-year low. Katayama also noted the debate over easing inheritance tax treatment for bonds. The market reaction was supportive for JGBs, with 20y bond demand improving and yields falling, while the yen briefly firmed up before ceding gains. Nikkei +0.74% to 67744, USDJPY -0.136% to 162.21, 10y JGB -7.1bp to 2.719%.
Reserve managers are starting to trim their dollar exposure, but only cautiously. OMFIF’s 2026 Global Public Investor survey shows a marginal net 3% intention to reduce U.S. dollar holdings over the next one to two years, rising to 8% over ten years, while the dollar still makes up about 58% of reserves. Gold is the clearest beneficiary, with geopolitical risk and diversification driving demand: 82% of central banks now hold physical gold. The renminbi and euro are the main partial alternatives, with modest near-term interest and stronger ten-year intentions, especially where China’s financial links are deeper or where Europe could solve its safe asset gap. Digital assets remain marginal despite growing stablecoin volumes. Overall, de-dollarization looks more gradual than decisive: “reluctant alternatives” are emerging, but a true “good alternative” is still not here. Gold +0.32% to 4015.19, silver +0.606% to 58.0062, platinum +0.231% to 1607.9.
Chinese trade data for June showed a sharp acceleration, with exports rising 27% y/y (19.4% in May), the fastest pace since October 2021, while imports jumped 36% y/y (27.4% in May), in the biggest increase since June 2021. The stronger-than-expected showing was driven by booming global demand for AI hardware and a rush by U.S. retailers to frontload shipments ahead of potential tariff hikes. China’s trade surplus widened to $125.6bn. Exports to the U.S., Southeast Asia and the EU grew by about 14%, 35% and 18.5%, respectively, underscoring resilient external demand. The data suggest exports remain a key growth cushion even as domestic consumption and private investment remain weak amid the property downturn. CSI 300 +2.1% to 4794, USDCNY +0.006% to 6.7798, 10y CGB -0.4bp to 1.734%.
U.S. June CPI is forecast at -0.1% m/m, 3.8% y/y vs. 0.5% m/m, 4.2% y/y in May; core CPI is forecast at 0.2% m/m, 2.9% y/y vs. 0.2% m/m, 2.9% y/y in May.
U.S. June federal budget balance is forecast to narrow to -$128.3bn vs. -$292.6bn.
U.S. ADP weekly employment change, last at 21.0k.
U.S. real average weekly earnings, last at -0.5% y/y, real average hourly earnings, last at -0.8% y/y.
Central bank speakers: Fed Chair Kevin Warsh testifies before the House Financial Services Committee; the Fed’s Michael Barr speaks on artificial intelligence; the Fed’s Austan Goolsbee gives a fireside chat; the Fed’s Lisa Cook and Michelle Bowman speak at the Financial Inclusion Conference.
U.S. Treasury sells $95bn in 6-week bills.
Mood: iFlow Mood slipped deeper into negative territory at -0.148, driven by continued rotation into core sovereign bonds and persistent selling of global equities.
FX: Flows remained mixed and subdued. Safe haven demand continued to favor USD, CNY, JPY and CHF, while KRW, SGD, GBP, CAD and EUR saw the largest outflows.
FI: Demand was again concentrated in U.S. Treasurys, U.K. gilts and Eurozone and Indian government bonds. Selling was selective, focused on Thai and Chinese government bonds.
Equities: G10 flows were mixed, with buying in U.S. and Japanese equities offset by selling in Europe and the U.K.. In EM, Colombia recorded the largest outflows, while Türkiye, India and Thailand attracted fresh inflows.
“The future is already here – it’s just not very evenly distributed.” – William Gibson
“It happens slowly at first and then all at once.” – Ernest Hemingway
U.S. small business optimism rose to 97.4 points in June, up 2.1 vs. May and close to the 52-year average of 98.0. The NFIB said improved expectations for business conditions and real sales drove the gain, while the uncertainty index slipped to 89 but remained elevated. Hiring indicators also improved, with 32% of owners reporting unfilled job openings and a net 11% planning new jobs. Inflation remained the top concern, and price increases accelerated, though fewer firms plan to raise prices in the near future. Capital spending intentions, borrowing costs and expected sales all improved modestly, pointing to a better but still cautious outlook. S&P Mini -0.09% to 7557, DXY -0.148% to 101.086, 10y UST -0.4bp to 4.62%.
The British Retail Consortium Retail Sales Monitor showed U.K. retail sales value growth slowing in June. Total sales rose 1.9% y/y, down from 3.7% in May. Food sales increased by 2.8% y/y, easing from 3.9% previously, while non-food sales grew 1.2% y/y after 3.5% in May. Same-store sales rose 1.7% y/y, compared with 3.4% in May. Food same-store sales were up 2.2% y/y versus 3.3%, and non-food same-store sales rose 1.2% y/y, down from 3.5%. The report measures actual sales value and is not adjusted for price changes, so it reflects both spending and price effects. Same-store sales are a closer gauge of underlying spending patterns, though they may understate overall retail growth. FTSE 100 -0.54% to 10441, GBPUSD +0.233% to 1.3379, 10y gilt +5.5bp to 5.025%.
Swiss producer and import prices fell 0.3% m/m in June, leaving the combined index at 99.8 (on a base where December 2025 equals 100 points). On a y/y basis, the total supply price level for domestic and imported goods was down 2.1%. The producer price index eased 0.1% m/m and 2.7% y/y, while the import price index declined by 0.7% m/m and 0.8% y/y. The main downward drivers were mineral oil products, crude oil and natural gas, while higher prices were seen in metals and metal semi-finished goods and some computer-related items. SMI -0.83% to 14148, EURCHF -0.163% to 0.92574, 10y Swiss GB +2.3bp to 0.451%.
Japanese output data for May showed the manufacturing production capacity index falling 0.4% m/m to 94.5 points, while the manufacturing operating rate index rose 0.1% to 103.0. Within capacity, declines were led by production machinery, iron and nonferrous metals, and other industries, partly offset by gains in electronic parts, and petroleum and coal products. In the broader industrial statistics, seasonally adjusted production increased by 0.1%, shipments rose 0.5%, inventories fell 1.1% and the inventory ratio climbed 0.7%. Production, shipments, inventories and the inventory ratio were all revised down from the preliminary release. Nikkei +0.74% to 67744, USDJPY -0.173% to 162.35, 10y JGB -7.3bp to 2.717%.
Australia’s Westpac-Melbourne Institute Consumer Sentiment Index rose 4.1% to 83.9 points in July from 80.6 in June but remains deeply pessimistic and still in the bottom 10% of the survey’s history. The improvement was driven by easing fears around fuel, interest rates and jobs. Family finances versus a year ago improved to 71.1 (+5.6%), helped by lower fuel prices, while family finances over the next 12 months jumped to 96.5 (+13.4%). Mortgage rate expectations fell to 162.6 (-5.8%), and unemployment expectations eased to 129.9 (-7.1%), back near average. Views on the economy and major purchases were little-changed and remained weak. House price expectations fell to a three-year low of 118 (-8.0%). Westpac said sentiment is still subdued, with the RBA’s August meeting and the June quarter CPI announcement on July 29 representing key near-term risks. ASX +0.03% to 5646, AUDUSD -0.173% to 0.6934, 10y ACGB +5.1bp to 4.91%.
Australia’s June NAB Monthly Business Survey showed business confidence continued to recover, rising 9 points to -5, although it remained negative. Business conditions were steady at +3 for a third consecutive month, suggesting activity has slowed but not deteriorated sharply. The survey pointed to easing cost and price pressures, with purchase cost growth well down from its March peak, final prices moderating and retail prices falling for the first time in seven years. Capacity utilization held at 82.0%, while employment was slightly softer, profitability improved and trading conditions were broadly unchanged. NAB said concerns around Middle East tensions and the associated fuel cost shock had eased, reducing the expected inflation impact. Overall, the report indicates a slower economy, but one proving more resilient than feared, with inflation pressures cooling across most industries.
RBNZ Chief Economist Paul Conway said the Middle East conflict has complicated the inflation outlook and created upside risks to the September quarter forecast. The RBNZ now sees inflation at 3.9% in the June quarter and 3.3% in the current quarter, with near-term pressures having eased but global events having delivered another significant inflation shock. Conway said medium-term inflation expectations remain well-anchored and spare capacity in the economy should help limit passthrough. Still, after prolonged above-target inflation, expectations cannot be taken for granted. He reiterated that, with inflation still above target and activity expected to strengthen, further removal of monetary stimulus is likely needed. The key uncertainty is how price-setting behavior will evolve, and the RBNZ said it will respond if conflict-driven inflation proves more persistent. NZX 50 -0.52% to 13651, NZDUSD +0.122% to 0.5789, 10y NZGB +4.8bp to 4.662%.
Indian wholesale price index inflation rose to 9.87% y/y in June, from 9.68% in May, with the all commodities index increasing to 110.2 from 109.9. Price pressures were led by fuel and power, which remained the strongest contributor at 27.41%, while primary articles accelerated to 7.0% and manufactured products held steady at 7.48%. The food index also firmed up: it rose 6.14% vs. 4.49% in May, reflecting higher food article and food product prices. Key drivers included mineral oils, food articles, basic metals and chemicals, pointing to broad-based inflationary pressure across commodity groups. SENSEX -0.66% to 77107, USDINR -0.58% to 96.1812, 10y INGB +6.1bp to 6.792%.
Singapore’s Q2 GDP came in at 5.7% y/y, softening from 6.3% in Q1, while q/q seasonally adjusted growth was 1.1% after 1.3% in Q1. The Ministry of Trade and Industry said growth was led by a strong manufacturing rebound, with the sector rising 12.2% y/y on robust electronics and precision engineering output tied to AI-related semiconductor demand. Construction slowed to 6.2%, while services grew more moderately, with wholesale and retail trade and transportation, and finance and professional services, remaining positive. The release noted that the figures are advance estimates based mainly on April and May data and may be revised. STI +0.48% to 5497, USDSGD -0.14% to 1.2937, 10y SGB +2.4bp to 2.153%.
South Korea’s government has upgraded its 2026 growth forecast to 3% from 2%, citing a semiconductor supercycle, stronger exports and easing Middle East tensions. The Ministry of Finance and Economy said the outlook now exceeds the 2.6% forecasts from the IMF, OECD and ADB. It expects the export boom to continue, with shipments supported by AI demand and robust non-IT goods, while facility investment should rise 5% on semiconductor equipment strength. The government also highlighted policy support, including an extra budget and industrial programs for semiconductors, AI data centers and physical AI. Inflation was lifted to 2.6% from 2.1%, reflecting higher petroleum prices from the Middle East conflict, though the ministry expects price pressures to ease in H2. Core inflation is seen around 2%. The current account surplus is projected at a record $290bn. KOSPI +0.73% to 6857, USDKRW +0.071% to 1495.85, 10y KTB +3.1bp to 4.267%.