Value in USD and U.S. tech; Treasurys hold firm
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.

Geoff Yu
Time to Read: 4 minutes
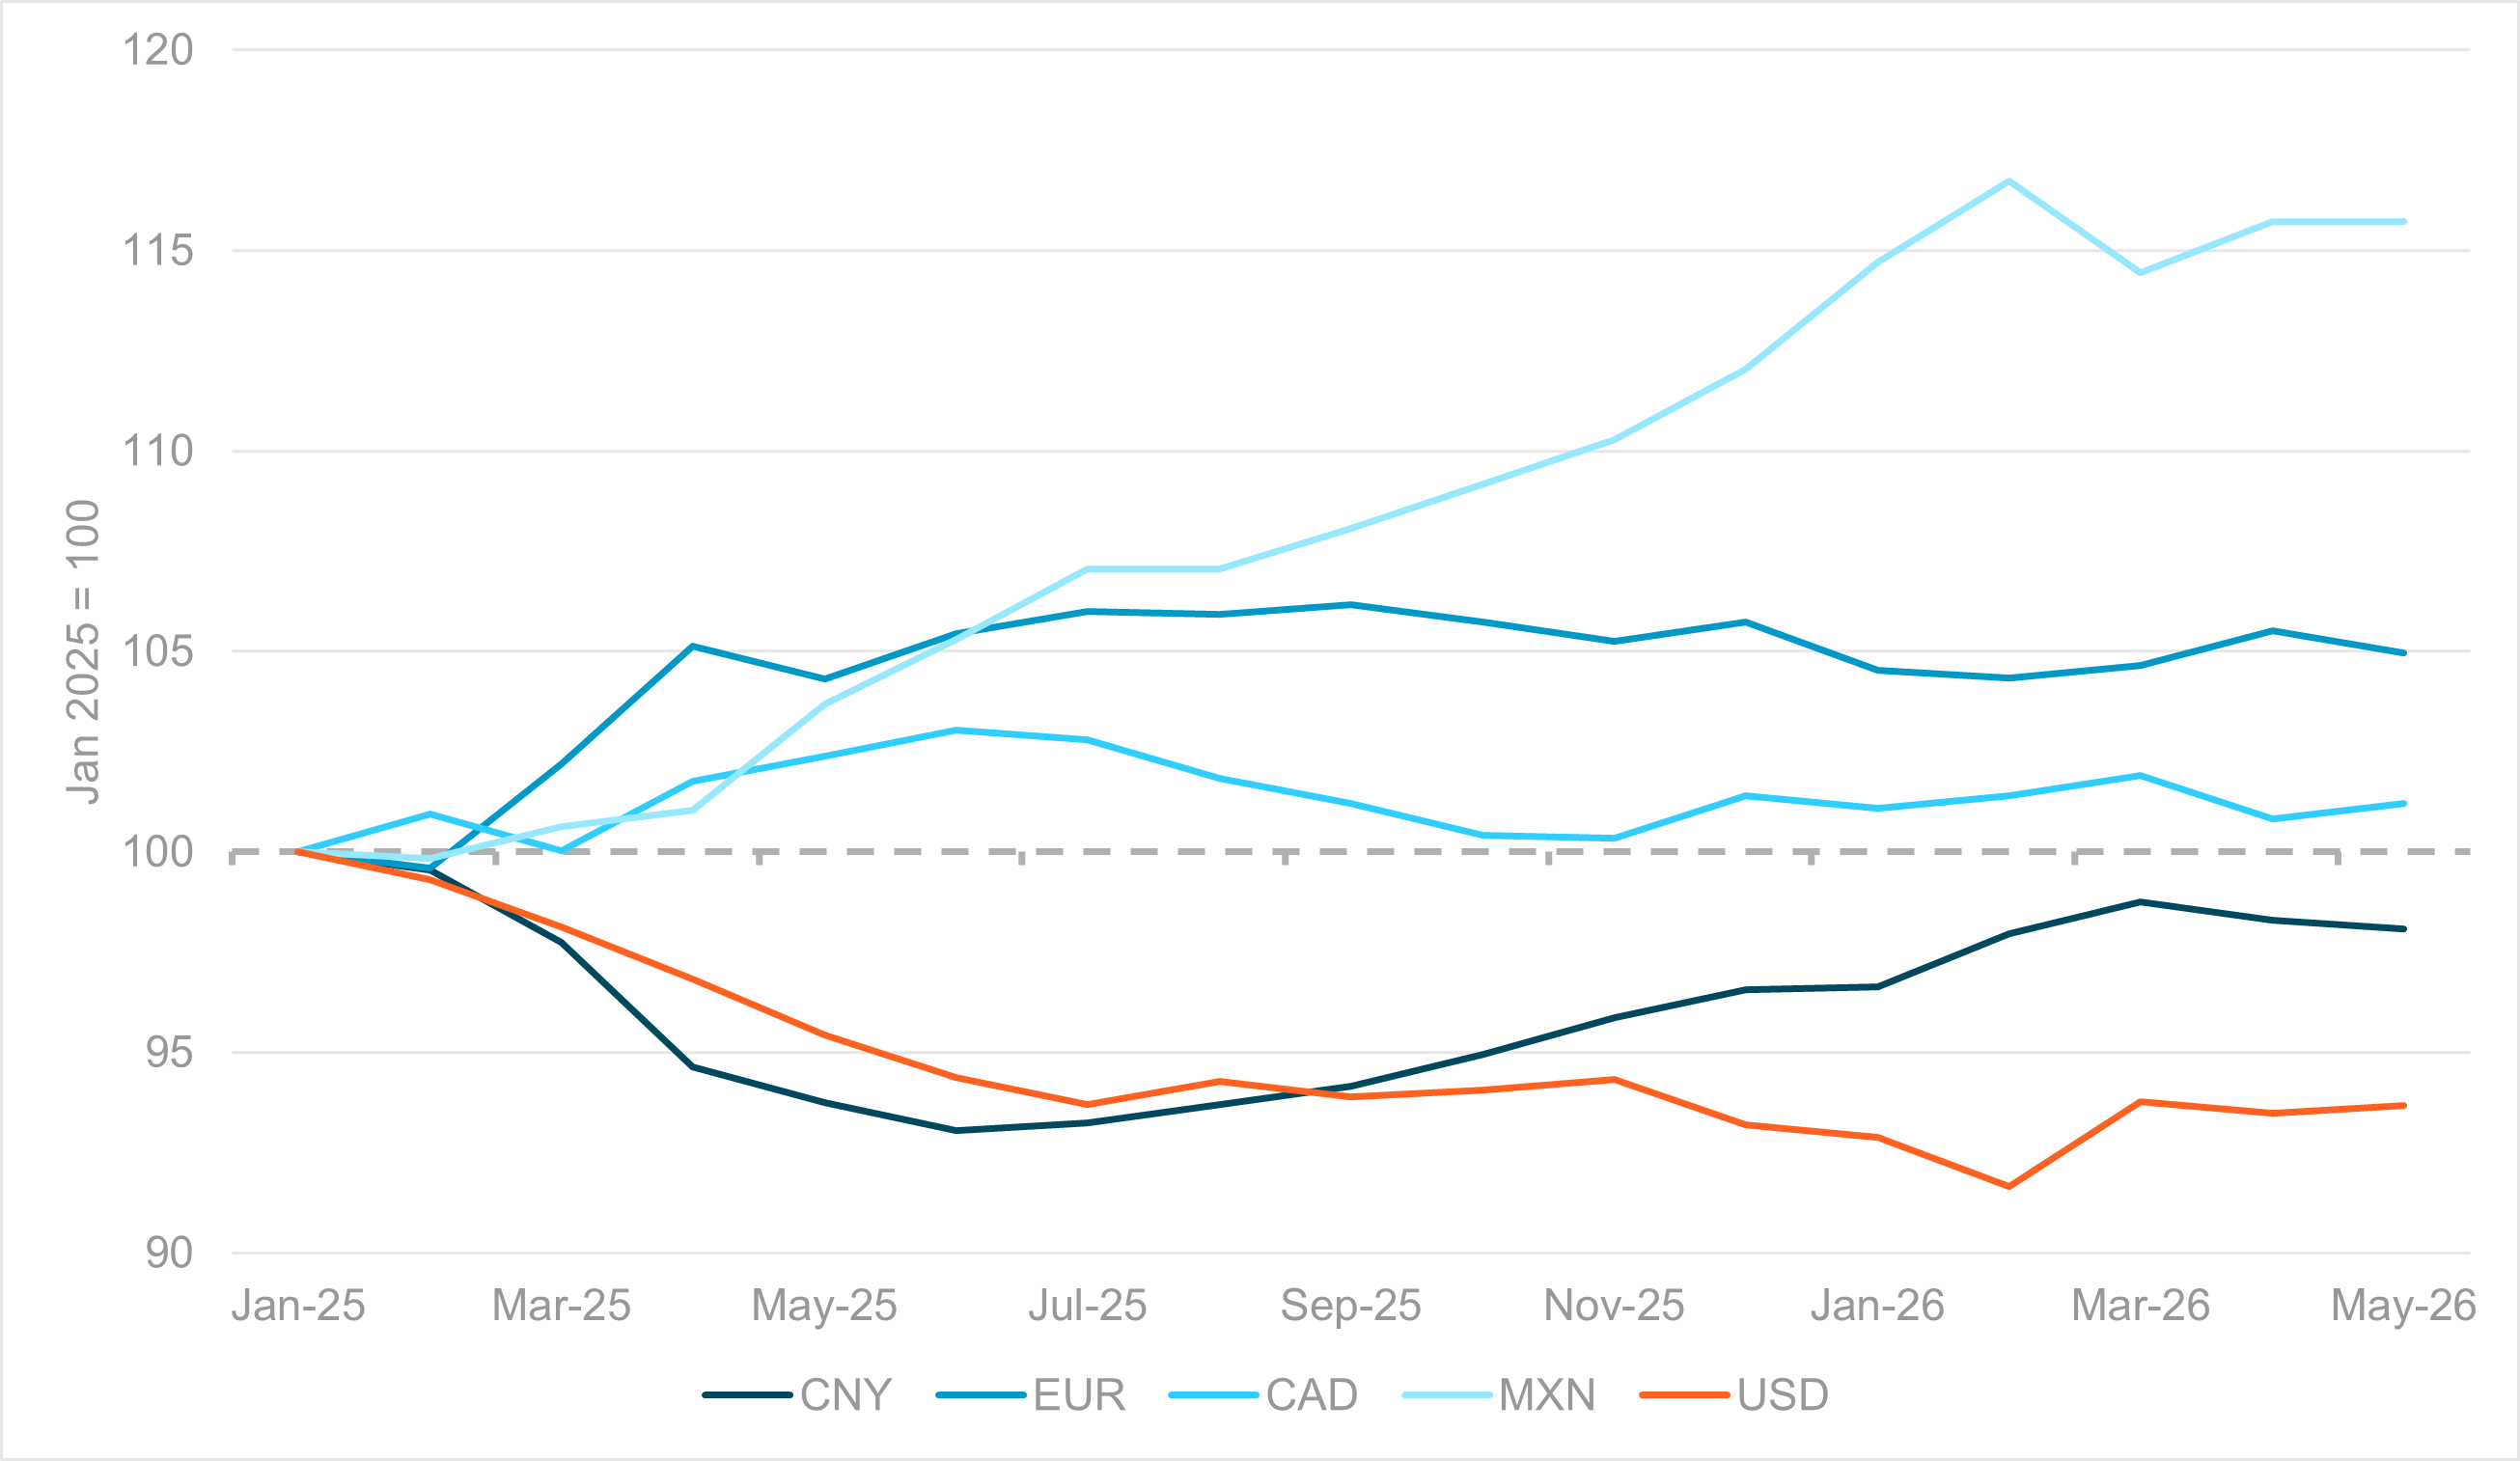
EXHIBIT #1: REAL EFFECTIVE EXCHANGE RATES, JAN 2025 = 100
Source: BNY, BIS
Our take
The resilient JOLTS report reinforces our view that this week’s labor market data should continue to support higher U.S. yields and a stronger dollar. After the recent moves in USDJPY, EURUSD and USDCAD, valuation concerns are bound to resurface. We think those concerns are premature. By historical standards, the dollar is nowhere near the extremes seen during previous episodes of U.S. exceptionalism.
Take the euro: the Eurozone’s growth outlook is arguably weaker today than it was at the end of 2024, yet EURUSD was already trading close to parity back then. Meanwhile, iFlow data showed cross-border EUR hedging at several multiples of current levels. The dollar also remains exceptionally undervalued in real terms. At the start of the year, inflation was not viewed as a material risk, and markets were cautiously pricing Fed easing. At the same time, key trading partners were at very different stages of the policy cycle, leaving inflation differentials broadly unfavorable for the dollar’s real effective exchange rate (REER), as shown in Exhibit 1. That backdrop is now reversing. Yesterday’s Eurozone inflation data saw Germany, France and Italy all surprise to the downside as domestic growth risks increasingly outweigh external supply pressures. In contrast, U.S. price dynamics continue to strengthen. As this divergence widens, the dollar’s REER has further room to appreciate.
Forward look
We continue to expect further gains in the dollar’s REER. The main risk is a sharp acceleration in demand-driven inflation – particularly wages – which would force a more aggressive Fed response and weigh on broader risk sentiment.
A stronger real dollar cuts both ways globally. On the one hand, stronger U.S. demand and higher import prices provide the reflation impulse many economies need. On the other, a materially stronger USD REER tightens global financial conditions by forcing central banks to respond to imported inflation while raising the cost of already-scarce dollar funding. Global trade flows have been reshaped over the past two years; we believe the tightening channel now poses the greater risk.
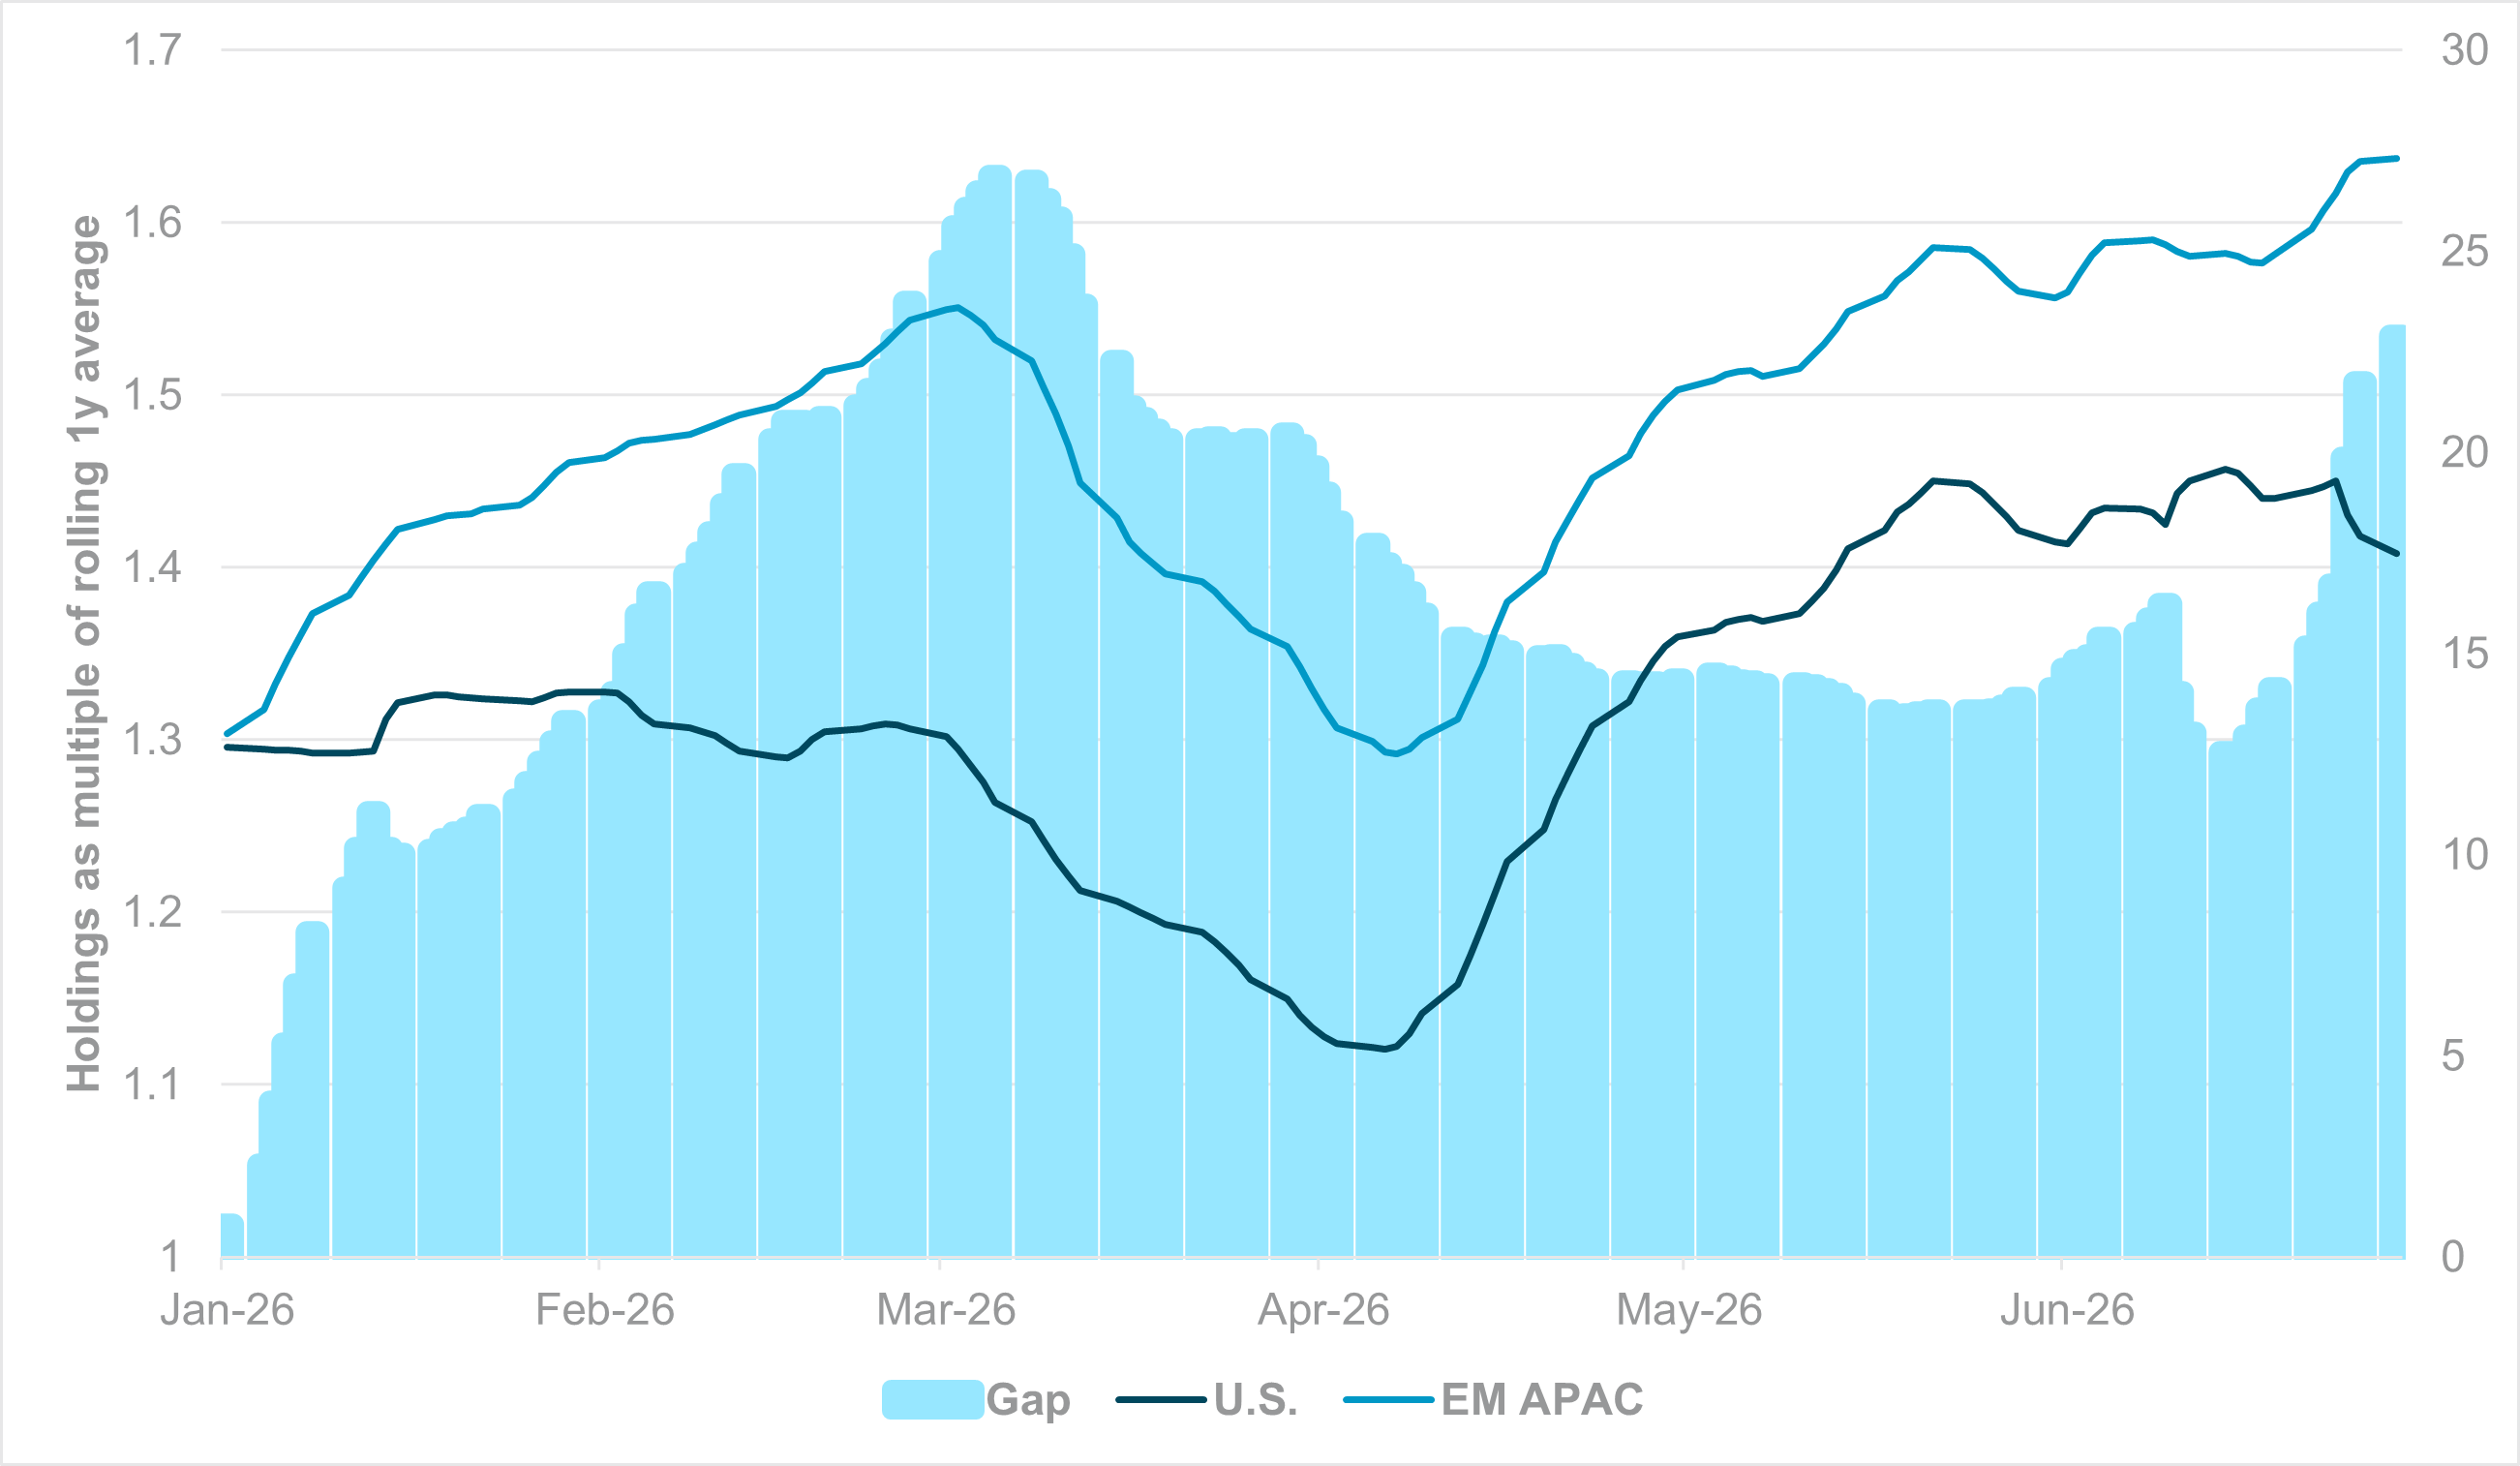
EXHIBIT #2: SCORED HOLDINGS IN SEMICONDUCTORS AND SEMICONDUCTOR EQUIPMENT (GICS 4530), EM APAC VS. U.S. PEERS
Source: BNY
Our take
U.S. and U.S.-aligned semiconductor stocks have been the defining global equity allocation this year, with almost 15% of global equity holdings concentrated in U.S., South Korea, and Taiwanese semiconductor and semiconductor equipment companies. Performance in these markets has remained closely aligned, with changes in holdings (net of flows) moving largely in tandem throughout the year. That relationship broke down at the end of June. EM APAC semiconductor holdings have consistently outperformed their U.S. peers, and the gap has now widened back to its largest since the start of the U.S.–Iran conflict, despite the absence of an obvious catalyst.
This week’s announcement that the South Korean government will support nearly $1tn of investment in new fabrication facilities highlights a structural advantage underpinning Asia’s semiconductor sector: coordinated industrial policy. While investors increasingly question the financing costs facing U.S. chipmakers, South Korean and Taiwanese firms continue to benefit from preferential lending, tax incentives and direct policy support. These measures lower discount rates and enhance valuations, particularly in markets where high domestic savings rates and strong balance sheets can be mobilized to fund investment. U.S. firms will benefit from ecosystem spillovers in South Korea and Taiwan, but China is pursuing a similar strategy, reinforcing the long-term competitive challenge facing the U.S. While the current U.S. administration has also embraced a more active industrial policy, structural constraints – including fiscal limits, political cycles and a greater reliance on private capital – are likely to make its impact less pronounced than in much of APAC.
Forward look
Strong fundamentals do not eliminate concentration risk. Semiconductor companies now account for an outsized share of APAC equity benchmarks, leaving regional allocations far less diversified than in the U.S. Our data show that semiconductor-related holdings represent 38.5% of our clients’ total EM APAC equity exposure, compared with less than 14% in U.S. portfolios. That asymmetry is a source of vulnerability. If the sector experiences a meaningful correction, EM APAC holdings would absorb a disproportionately larger hit, allowing the current holdings gap with the U.S. to close quickly.
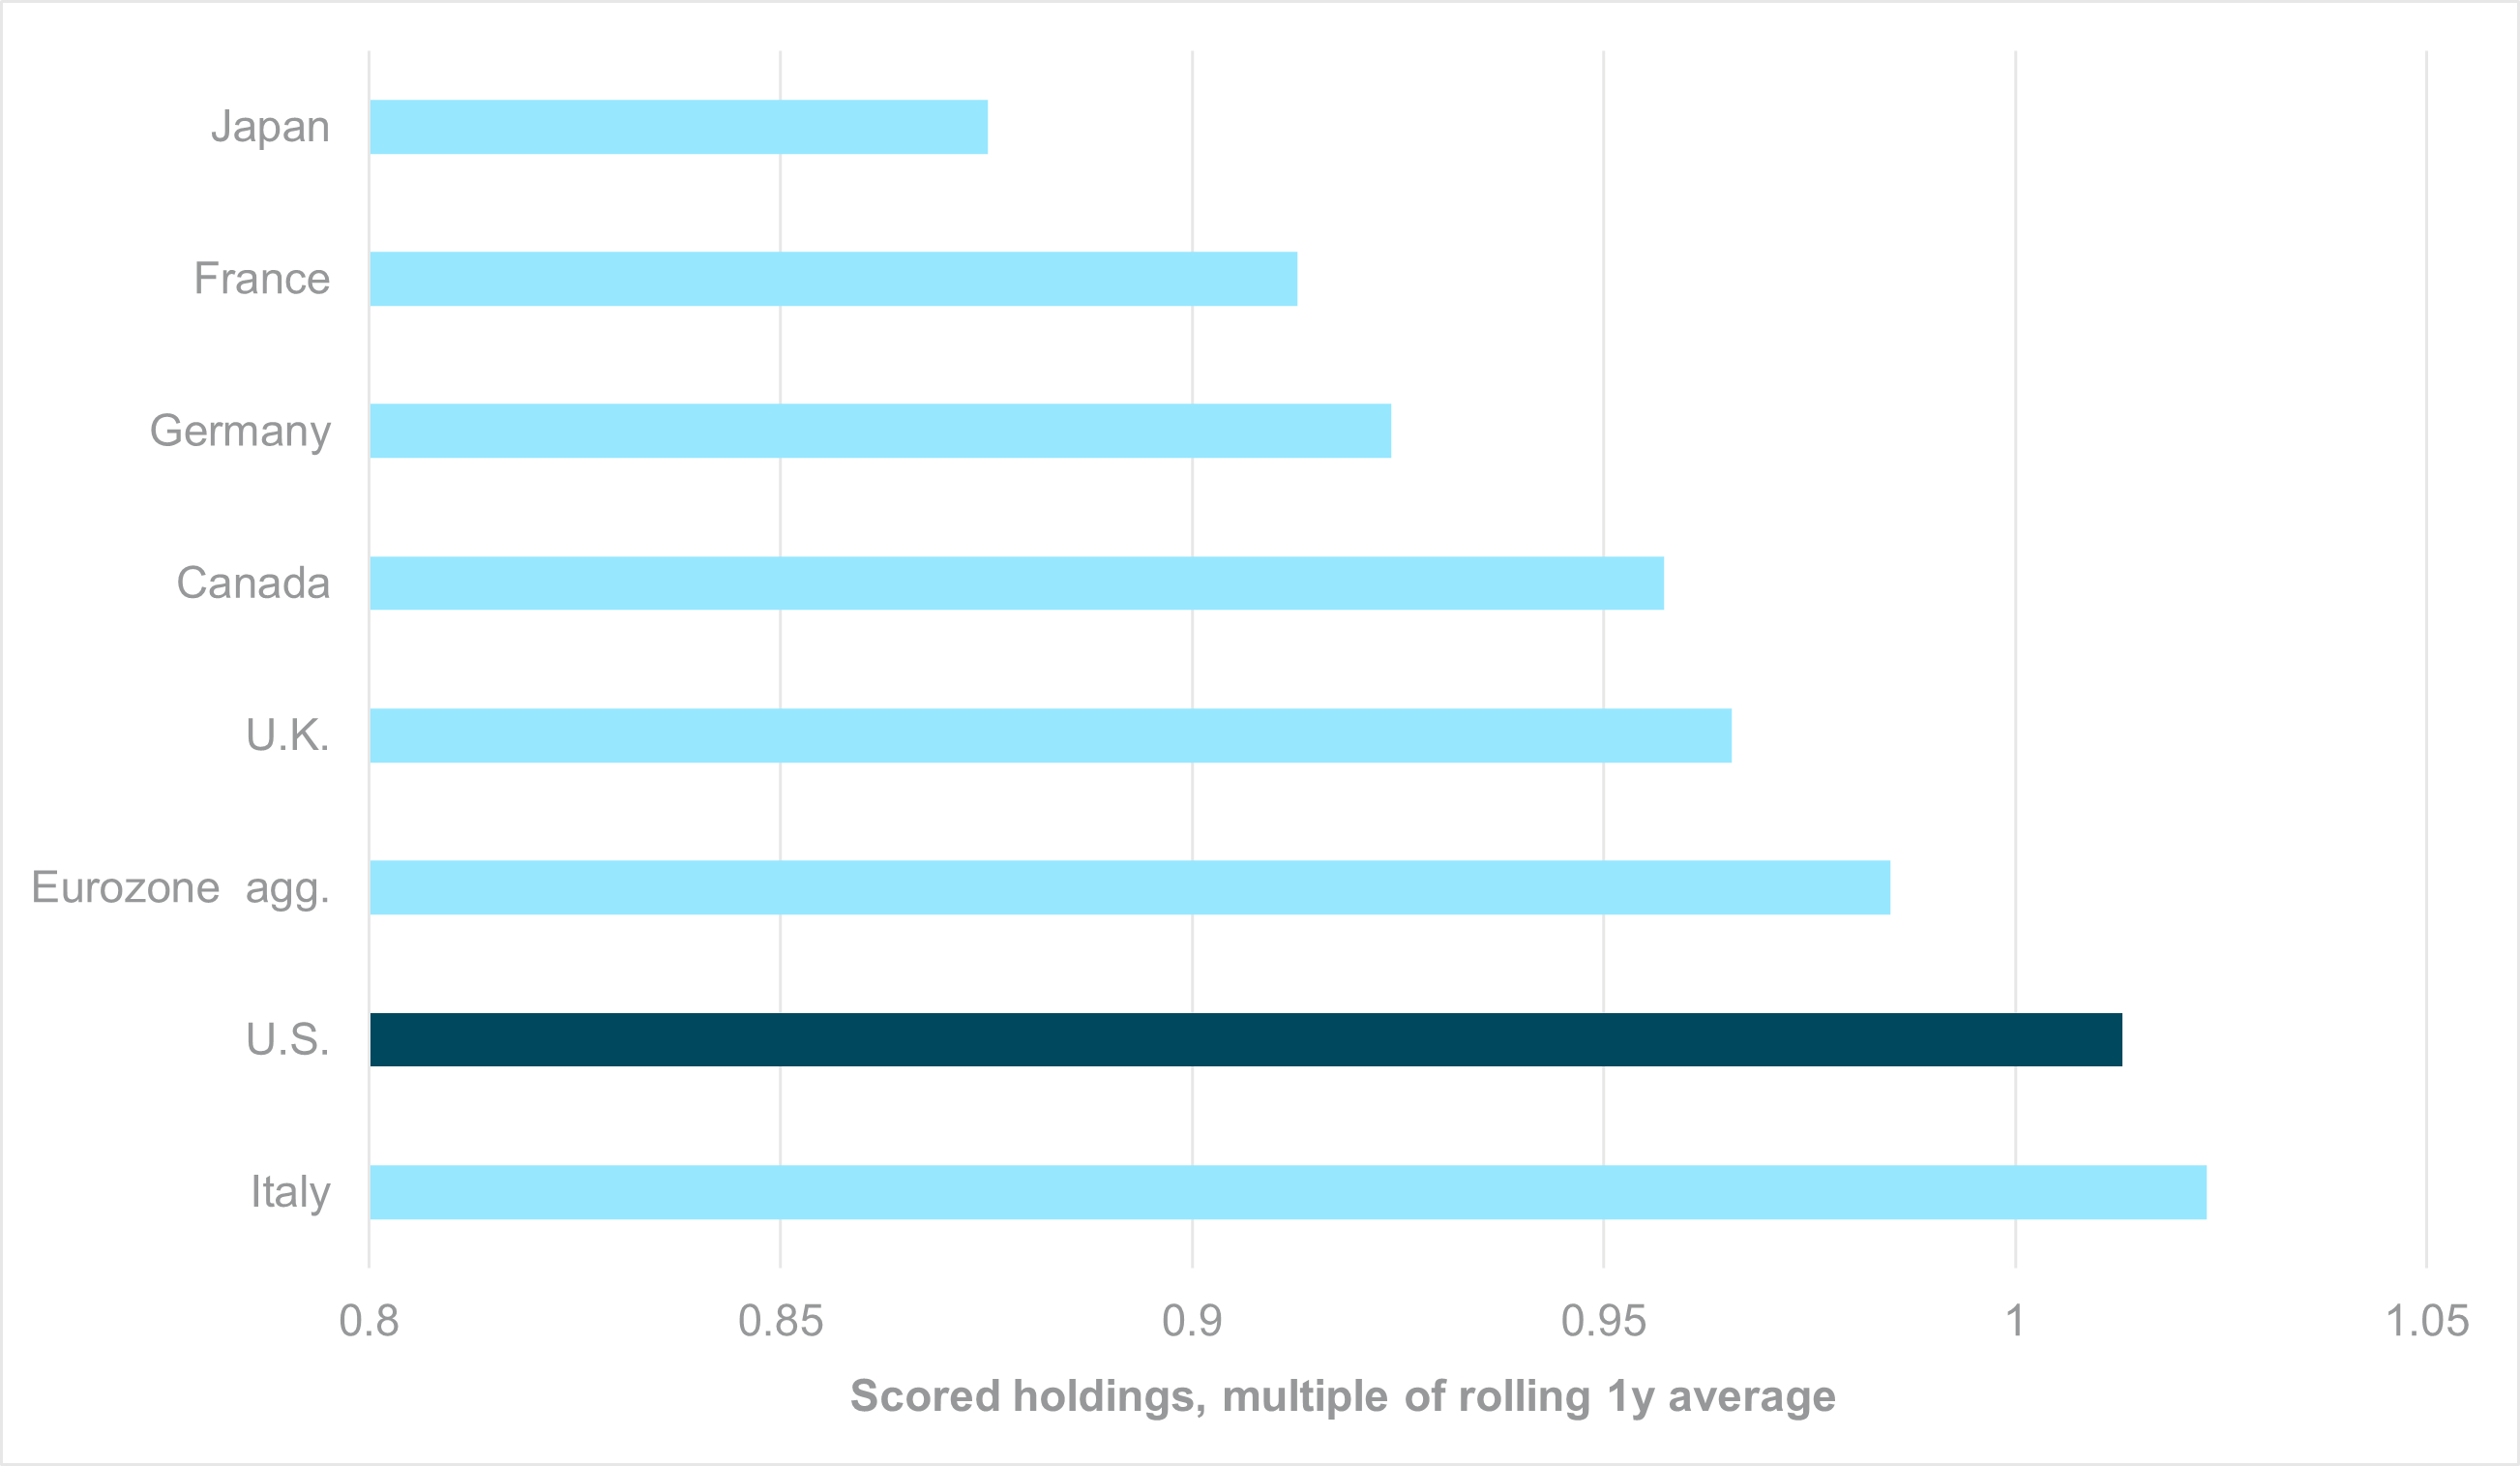
EXHIBIT #3: CURRENT HOLDINGS SCORE FOR G7 GOVERNMENT BONDS
Source: BNY
Our take
More than a year after the “Liberation Day” shock, markets continue to question whether U.S. Treasurys deserve their status as the world’s premier reserve asset. The data tell a different story. Nearly 75% of global sovereign bond holdings remain allocated to U.S. Treasurys and, as of end-Q2, holdings still exceed every other G7 sovereign market. Only Italian BTPs have seen a larger increase in holdings over the past year, while U.S. Treasurys remain comfortably ahead of aggregate Eurozone government bonds. Notably, Italy and the U.S. are the only G7 issuers where holdings have risen above last year’s levels, despite persistent duration headwinds from elevated issuance, fiscal expansion and higher term premia.
Forward look
Reserve demand and liquidity preference continue to underpin the Treasury market, with external investors favoring the front end of the curve. At the same time, European sovereign debt is becoming increasingly reliant on domestic buyers seeking positive real yields without taking FX risk. The immediate catalyst is this week’s U.S. labor market data. A resilient employment report would reinforce the current backdrop of anchored inflation expectations, supporting U.S. real yields, Treasury demand and, by extension, the dollar.
The key risk, however, is evidence of accelerating demand-driven inflation – particularly through wages – which would force markets to price a more aggressive Fed response. In that scenario, today’s elevated ownership levels could quickly shift from a source of stability to a source of vulnerability: investors would demand greater term compensation and the curve would steepen materially. For now, however, the depth, liquidity and reserve status of the Treasury market remain advantages that no credible alternative has yet matched.