Tracking steepening proxies
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.

Geoff Yu
Time to Read: 4 minutes
The current steepening move is being reinforced by positioning across FX, equities and rates. International investors are cutting record dollar exposure as real-yield support fades, utilities are outperforming traditional hard-asset hedges as long-end yields rise, and U.S. Treasury short utilization remains too low to suggest the move is fully priced in. Unless fiscal or monetary signals change materially, the path of least resistance remains toward further curve steepening and a continued normalization of dollar exposure.
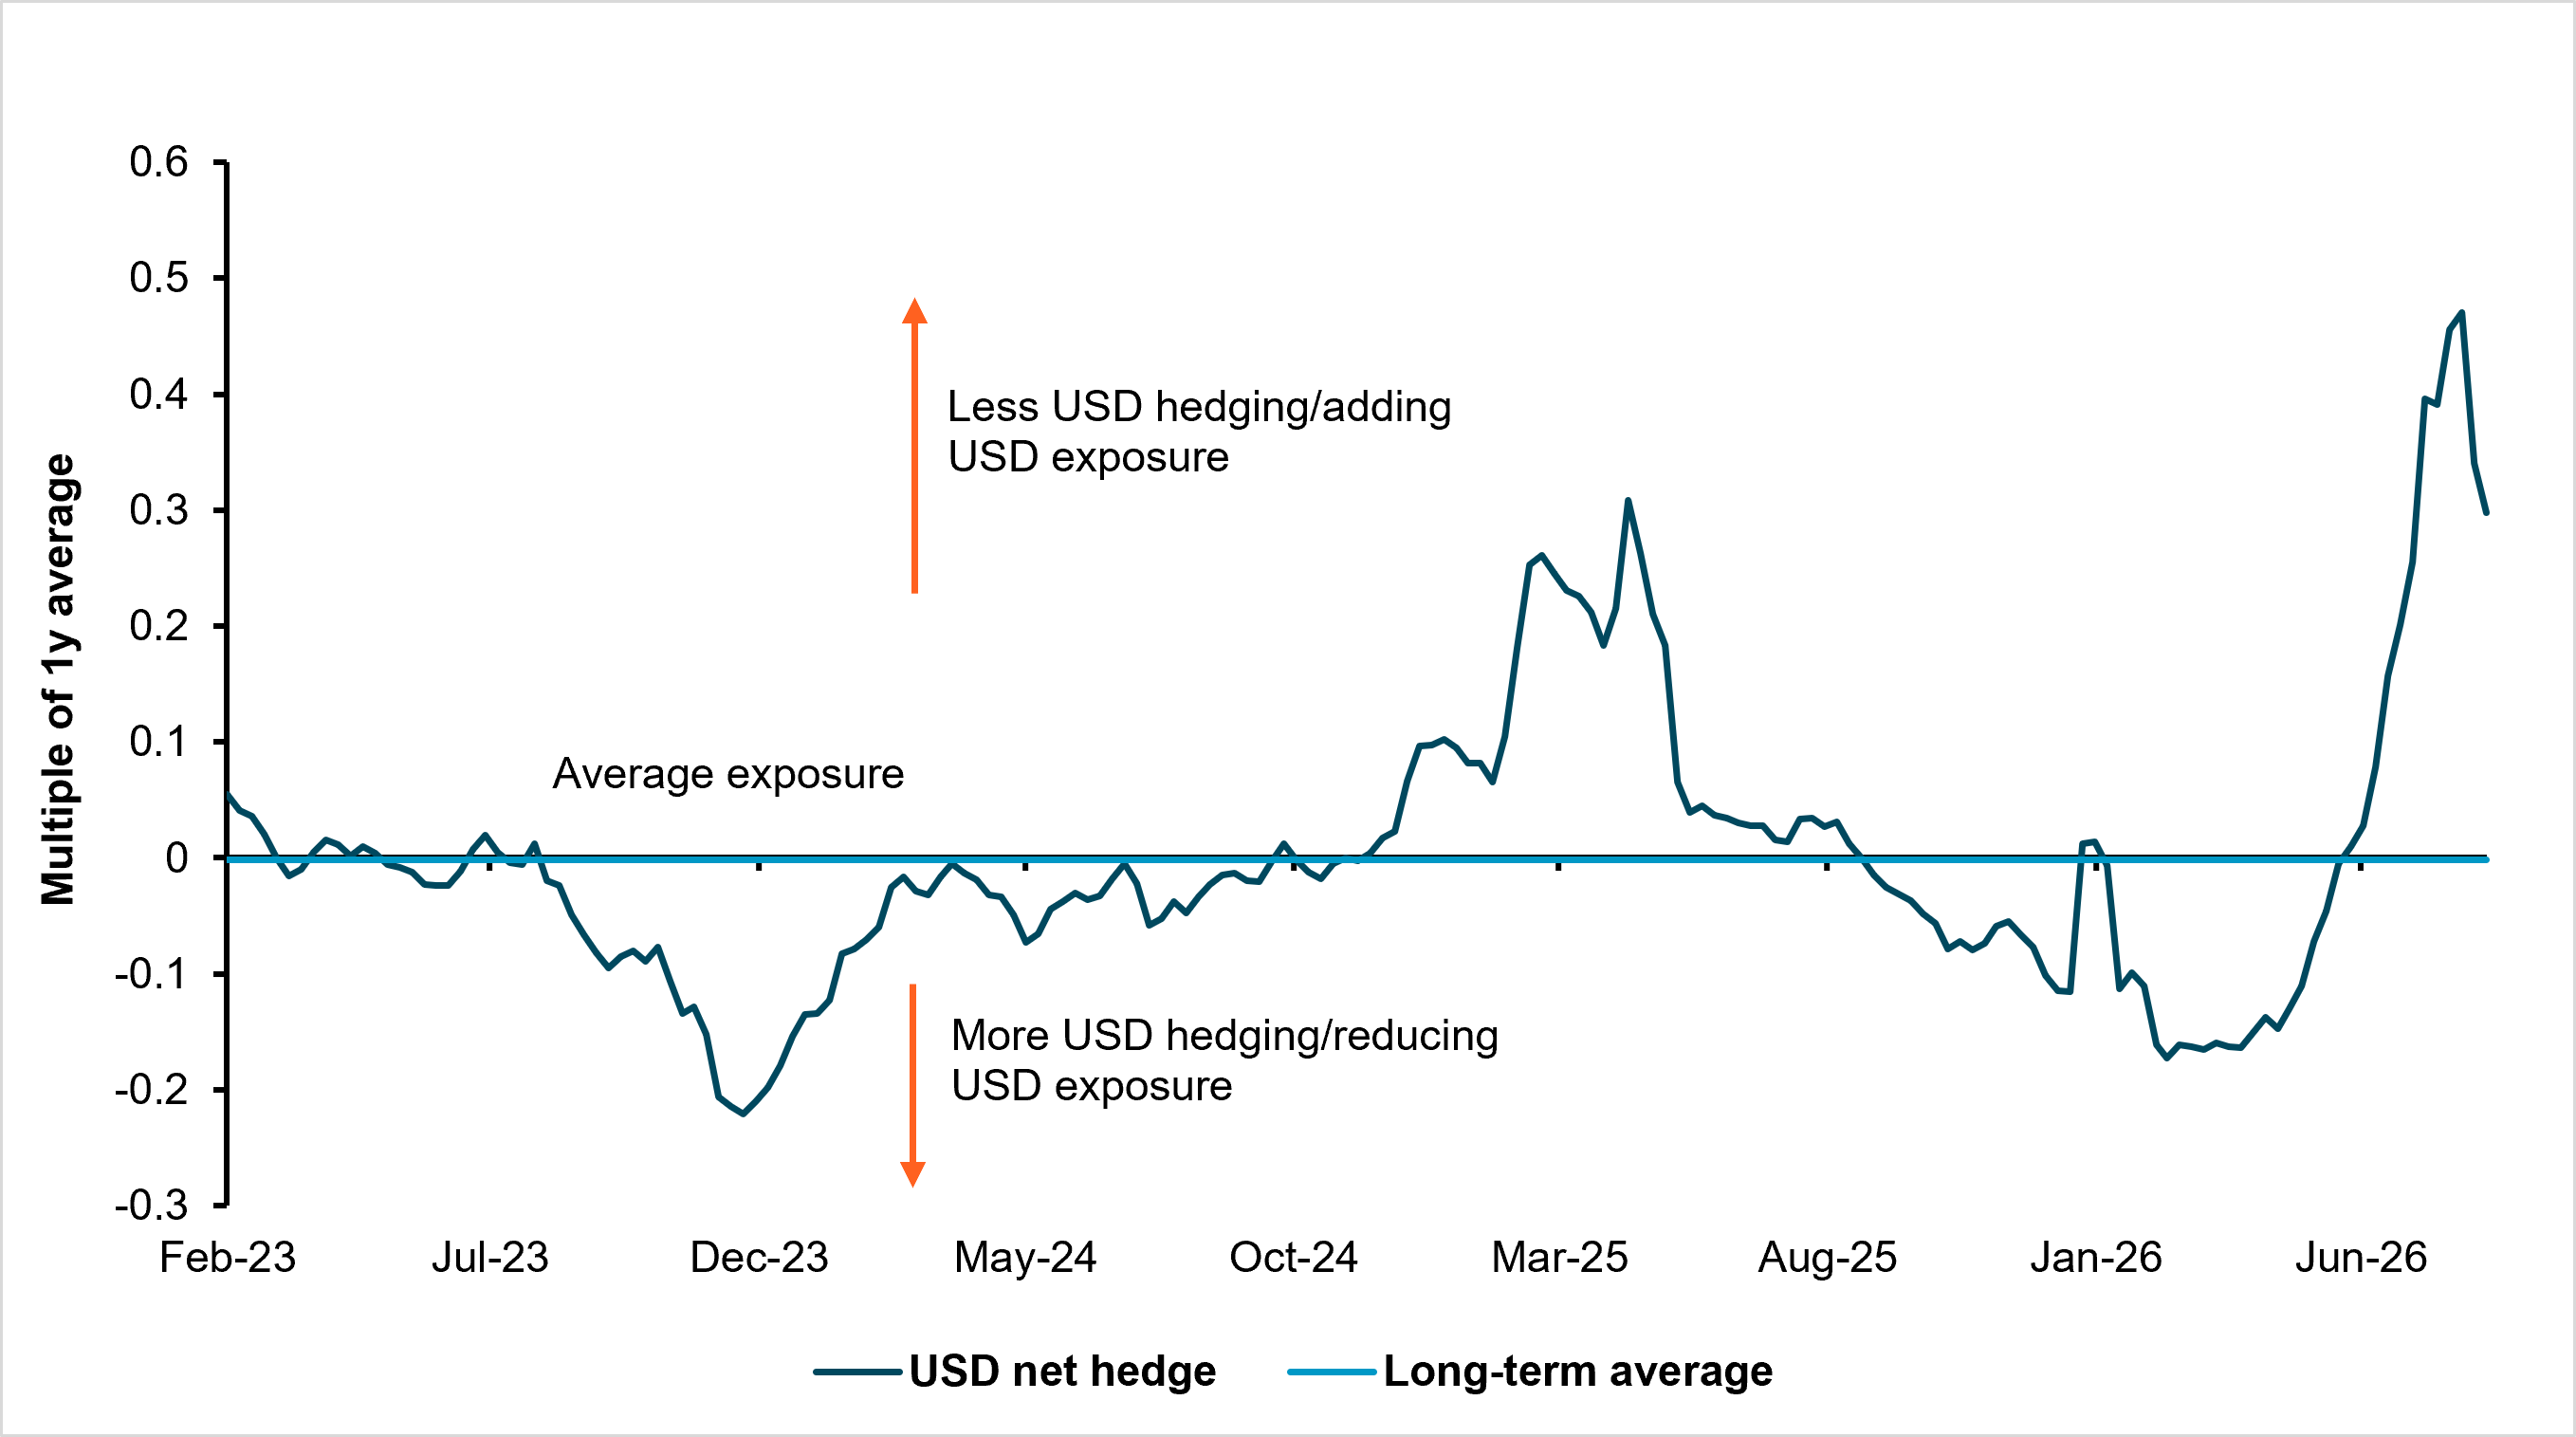
EXHIBIT #1: DOLLAR EXPOSURES CONTINUE TO DECLINE POST-FED, AS PASS-THROUGH RISK RISES
Source: BNY
Our take
The market is viewing the current bond move largely through an inflation-and-fiscal lens, but there’s a risk of a powerful feedback loop through the dollar. Aggregate U.S. exposure among international investors, measured using a 40:60 equity/fixed-income portfolio net of dollar holdings, recently reached record highs. The July FOMC meeting marked a clear turning point, and the unwind in “dollar exceptionalism” is now proving equally sharp. If the adjustment is fully symmetrical, we estimate total dollar exposure could return to flat within roughly 12 weeks, setting the stage for a significant regime shift in FX markets into Q4.
That timeline could prove conservative. The dollar is already weakening in nominal terms, introducing some pass-through inflation risk, even if the U.S. is less exposed to this channel than more export-dependent economies. This comes on top of uniquely strong domestic inflation pressures from capital expenditure and demand. As a result, downside risk to U.S. real rates, previously a key source of dollar support, could accelerate at the margin and become self-reinforcing. We saw a similar dynamic at the start of the year, when asset hedge ratios fell to two-year lows as real rates declined.
Forward look
The dollar is clearly under pressure, but the risks remain differentiated by pair and asset class. U.S. equity exceptionalism remains intact, while stronger home bias in fixed income means the marginal impact of overseas hedging should be smaller, particularly at shorter maturities. Barring a major policy misalignment, we see the current move as a healthy normalization of international exposure to U.S. assets. The long-run average of total U.S. exposure is close to flat, and the recent extremes were always likely to correct.
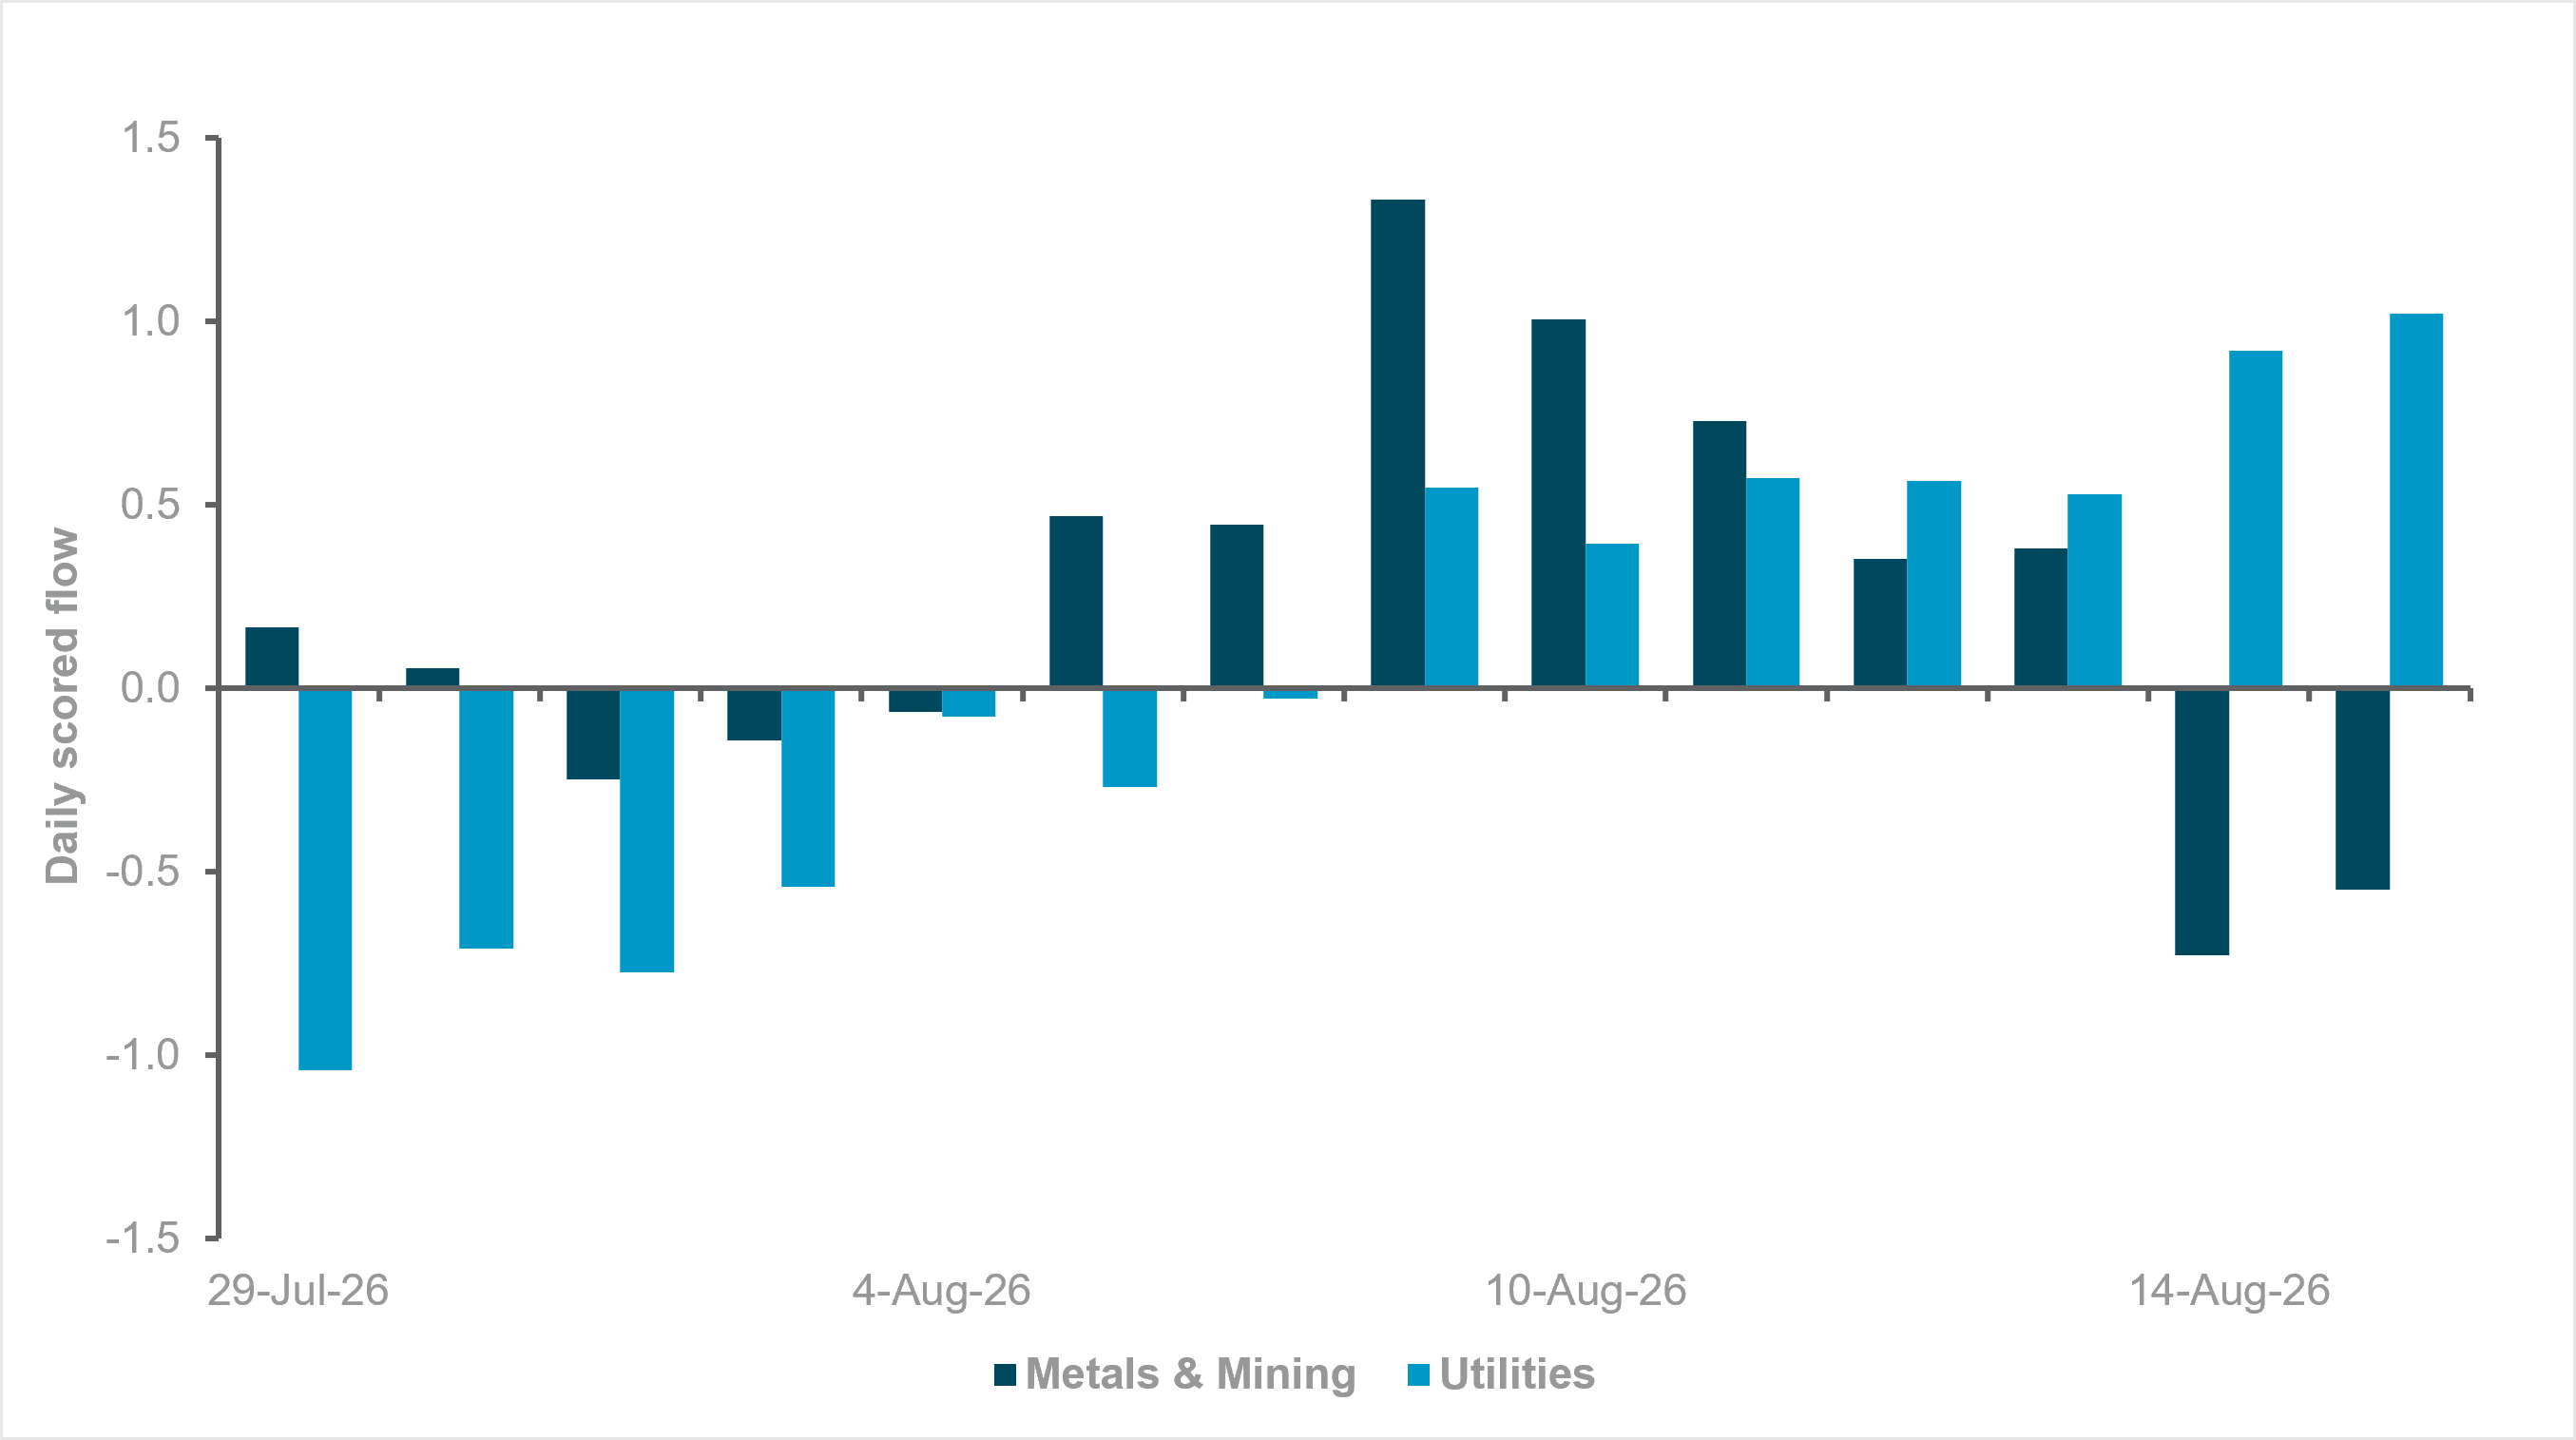
EXHIBIT #2: DAILY FLOW SINCE FED, METALS & MINING (GICS L3) VS. UTILITIES (GICS L2)
Source: BNY
Our take
Gold and utilities are emerging as the clearest inflation hedges, with gold remaining one of the strongest expressions of rising inflation concern. Our global Metals & Mining (GICS L3) flow proxy has shifted materially since the July FOMC, with late-July selling giving way to strong buying through August. Positioning remains well below the euphoria seen at the start of the year, and some profit-taking has emerged over the past two sessions, but gold is still expressing inflation risk more clearly than commodity FX or duration.
Utilities are performing even better. Like gold, utility flows turned decisively after the Fed decision, but the sector has shown far less sensitivity to the subsequent rise in long-dated yields. While Metals & Mining flows have started to soften, U.S. utility flows continue to accelerate, reaching their strongest post-Fed level on Monday. The divergence matters as curves steepen: gold remains the cleaner inflation hedge, but utilities are proving more resilient as both term and inflation premia rise. In flow terms, investors are increasingly using utilities as protection against higher long-end yields rather than relying solely on traditional inflation-sensitive assets.
Forward look
Utilities should continue to perform in the current environment, but metals, mining and precious metals exposure face a different set of constraints. First, extraction is energy-intensive, so higher input costs can pressure earnings even when commodity prices rise. Second, the “debasement” trade in January and February depended on the expectation that central banks would avoid tightening while fiscal largesse remained in place. That was an unusually supportive backdrop for real assets. The immediate reaction to the Fed briefly revived this dynamic, but the subsequent steepening in bond curves is itself tightening financial conditions and creating a headwind for real assets, particularly precious metals. Metals & Mining flows should still outperform commodity FX and industrial metals, but gold remains an imperfect hedge as higher long-end yields increasingly compete with the inflation story.
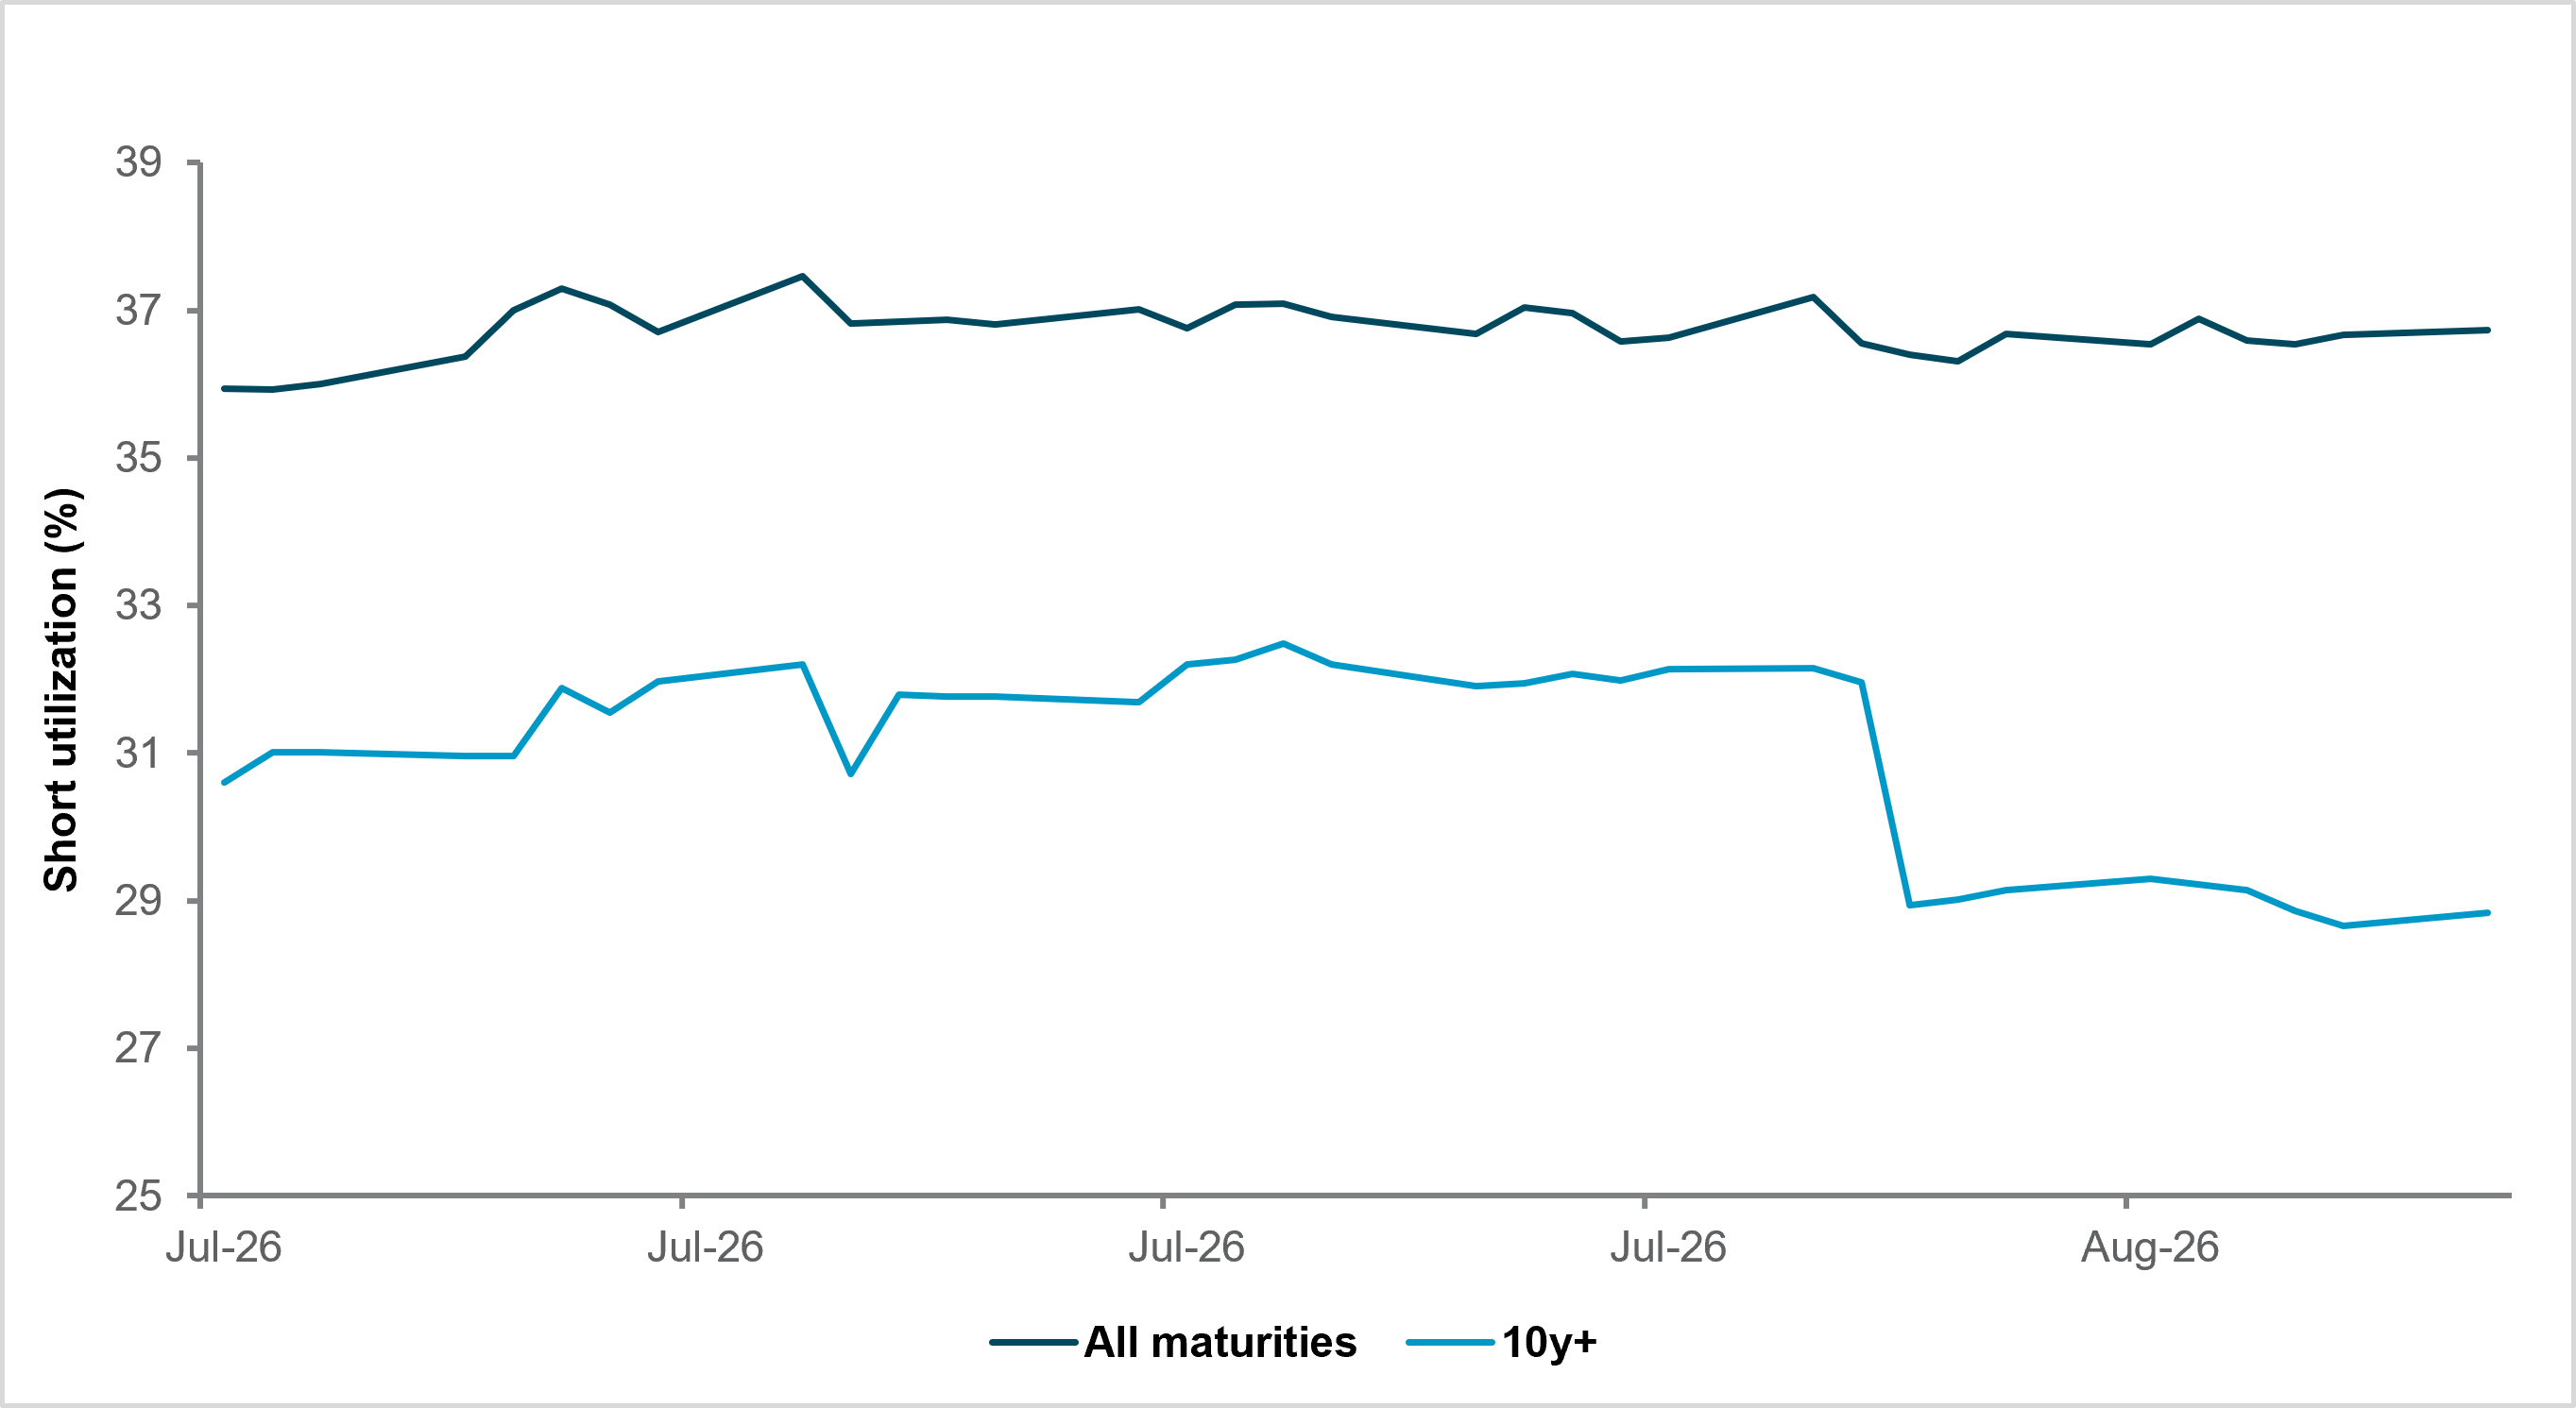
EXHIBIT #3: SHORT UTILIZATION IN U.S. TREASURYS, ALL MATURITIES AND 10Y+ MATURITIES
Source: BNY
Our take
When moves in any asset class become relatively violent, positioning becomes a decisive factor. We often point to the sharp EURUSD rally from parity to almost 1.20 in 2025 as a direct consequence of record underheld cross-border positioning. Government bond holdings are not similarly extreme, but our short-utilization indicator – the share of bonds in BNY’s lending program that have been sold short – has barely moved since July. More strikingly, short utilization in the 10y sector fell materially between the Fed meeting and late last week – by around two percentage points in absolute terms, or roughly 10% in relative terms. This suggests investors were taking profit on protection into the Fed, a move that now looks premature.
Forward look
Across all maturities, fixed-income short utilization remains broadly unchanged at 37%. The decline in longer-dated protection was not matched by a similar move at the front end or in shorter maturities. Even so, the lack of any meaningful increase in short utilization means clients did not add protection against further curve steepening. That leaves the bar relatively low for the current move to extend. The next phase may therefore extend across other parts of the curve, unless clearer fiscal or monetary policy signals emerge to contain term-premium and inflation risk.
Add protection against further steepening, particularly in the 10y-plus, where short utilization has fallen. In equities, favor utilities over Metals & Mining as the more resilient inflation and term-premium hedge. In FX, continue to raise USD hedge ratios rather than cut U.S. assets outright, while treating the dollar decline as a broader exposure normalization, not a collapse in U.S. exceptionalism.