The energy risk is there. The hedges aren’t.
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.

Geoff Yu
Time to Read: 4 minutes
Energy-related risks are rising again, but markets aren’t well hedged. Despite renewed tensions in the Gulf and concerns over Strait of Hormuz transits, cross-asset moves show very little interest in adding to “pure” energy exposure, except directly through crude oil futures. A return to the extreme volatility seen in March and early April isn’t our base case, but current flows look disproportionately low relative to event risk.
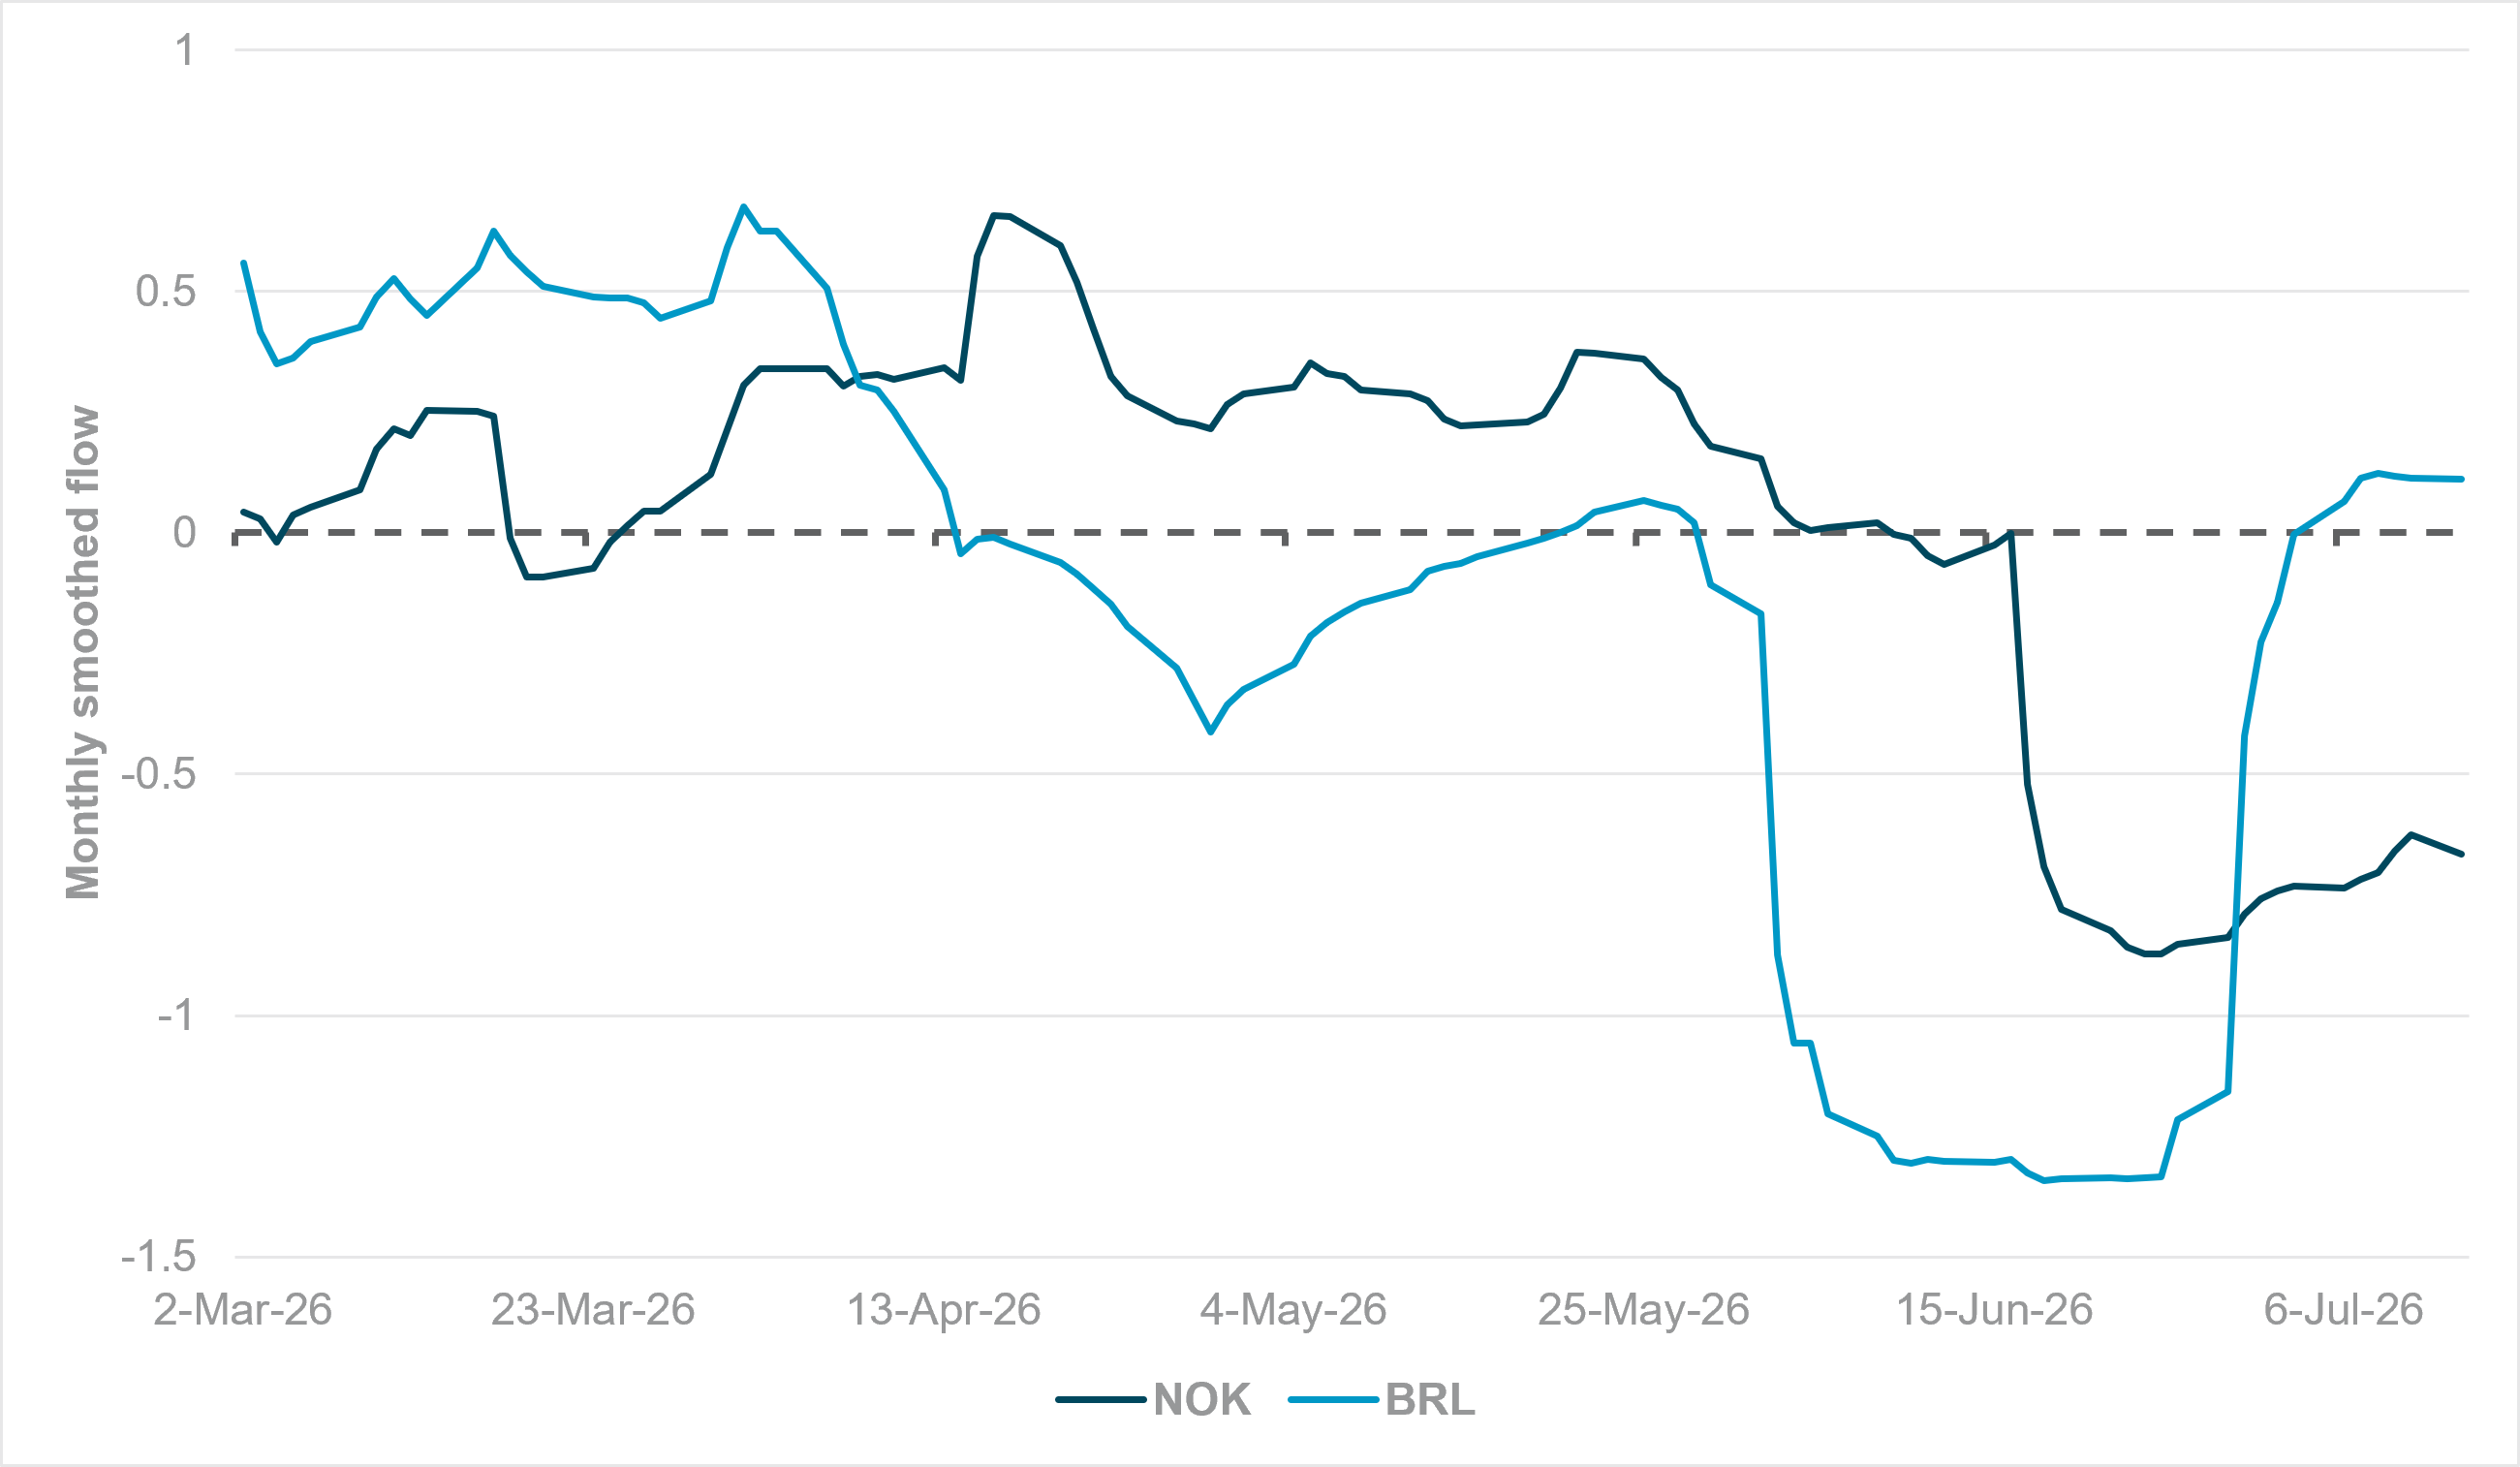
EXHIBIT #1: SMOOTHED MONTHLY FLOWS, NOK AND BRL
Source: BNY
Our take
During the most intense phases of the conflict, NOK and BRL were two of the best-performing currencies in flow and holdings terms. Yields, both nominal and real, were already favorable, while gains in liquefied natural gas prices were particularly supportive for terms-of-trade improvement. Our data show that market preferences tracked the conflict closely, with flows peaking in early April as the ceasefire took hold.
We would have characterized the market as sufficiently “hedged” in energy-linked currencies if flows had merely flattened out. Instead, there were sharp losses through June, first in BRL and subsequently in NOK, around the IMM and Fed dates. Long positions matured and markets clearly lacked conviction in a commodity-price recovery, especially after Fed pricing had fundamentally adjusted.
Forward look
Our data indicate that NOK and BRL remain overheld and positions are still in profit. However, levels are low: both currently stand below 50% of their rolling one-year averages. Flow performance has clearly recovered, but it will take time to rebuild holdings. Risk-reward looks highly favorable, and yesterday’s U.S. CPI figure has also made funding conditions more supportive. We still see the market moving toward a pro-carry phase through the summer. Adding NOK and BRL exposure simultaneously supports carry and provides a hedge against a renewed energy shock.
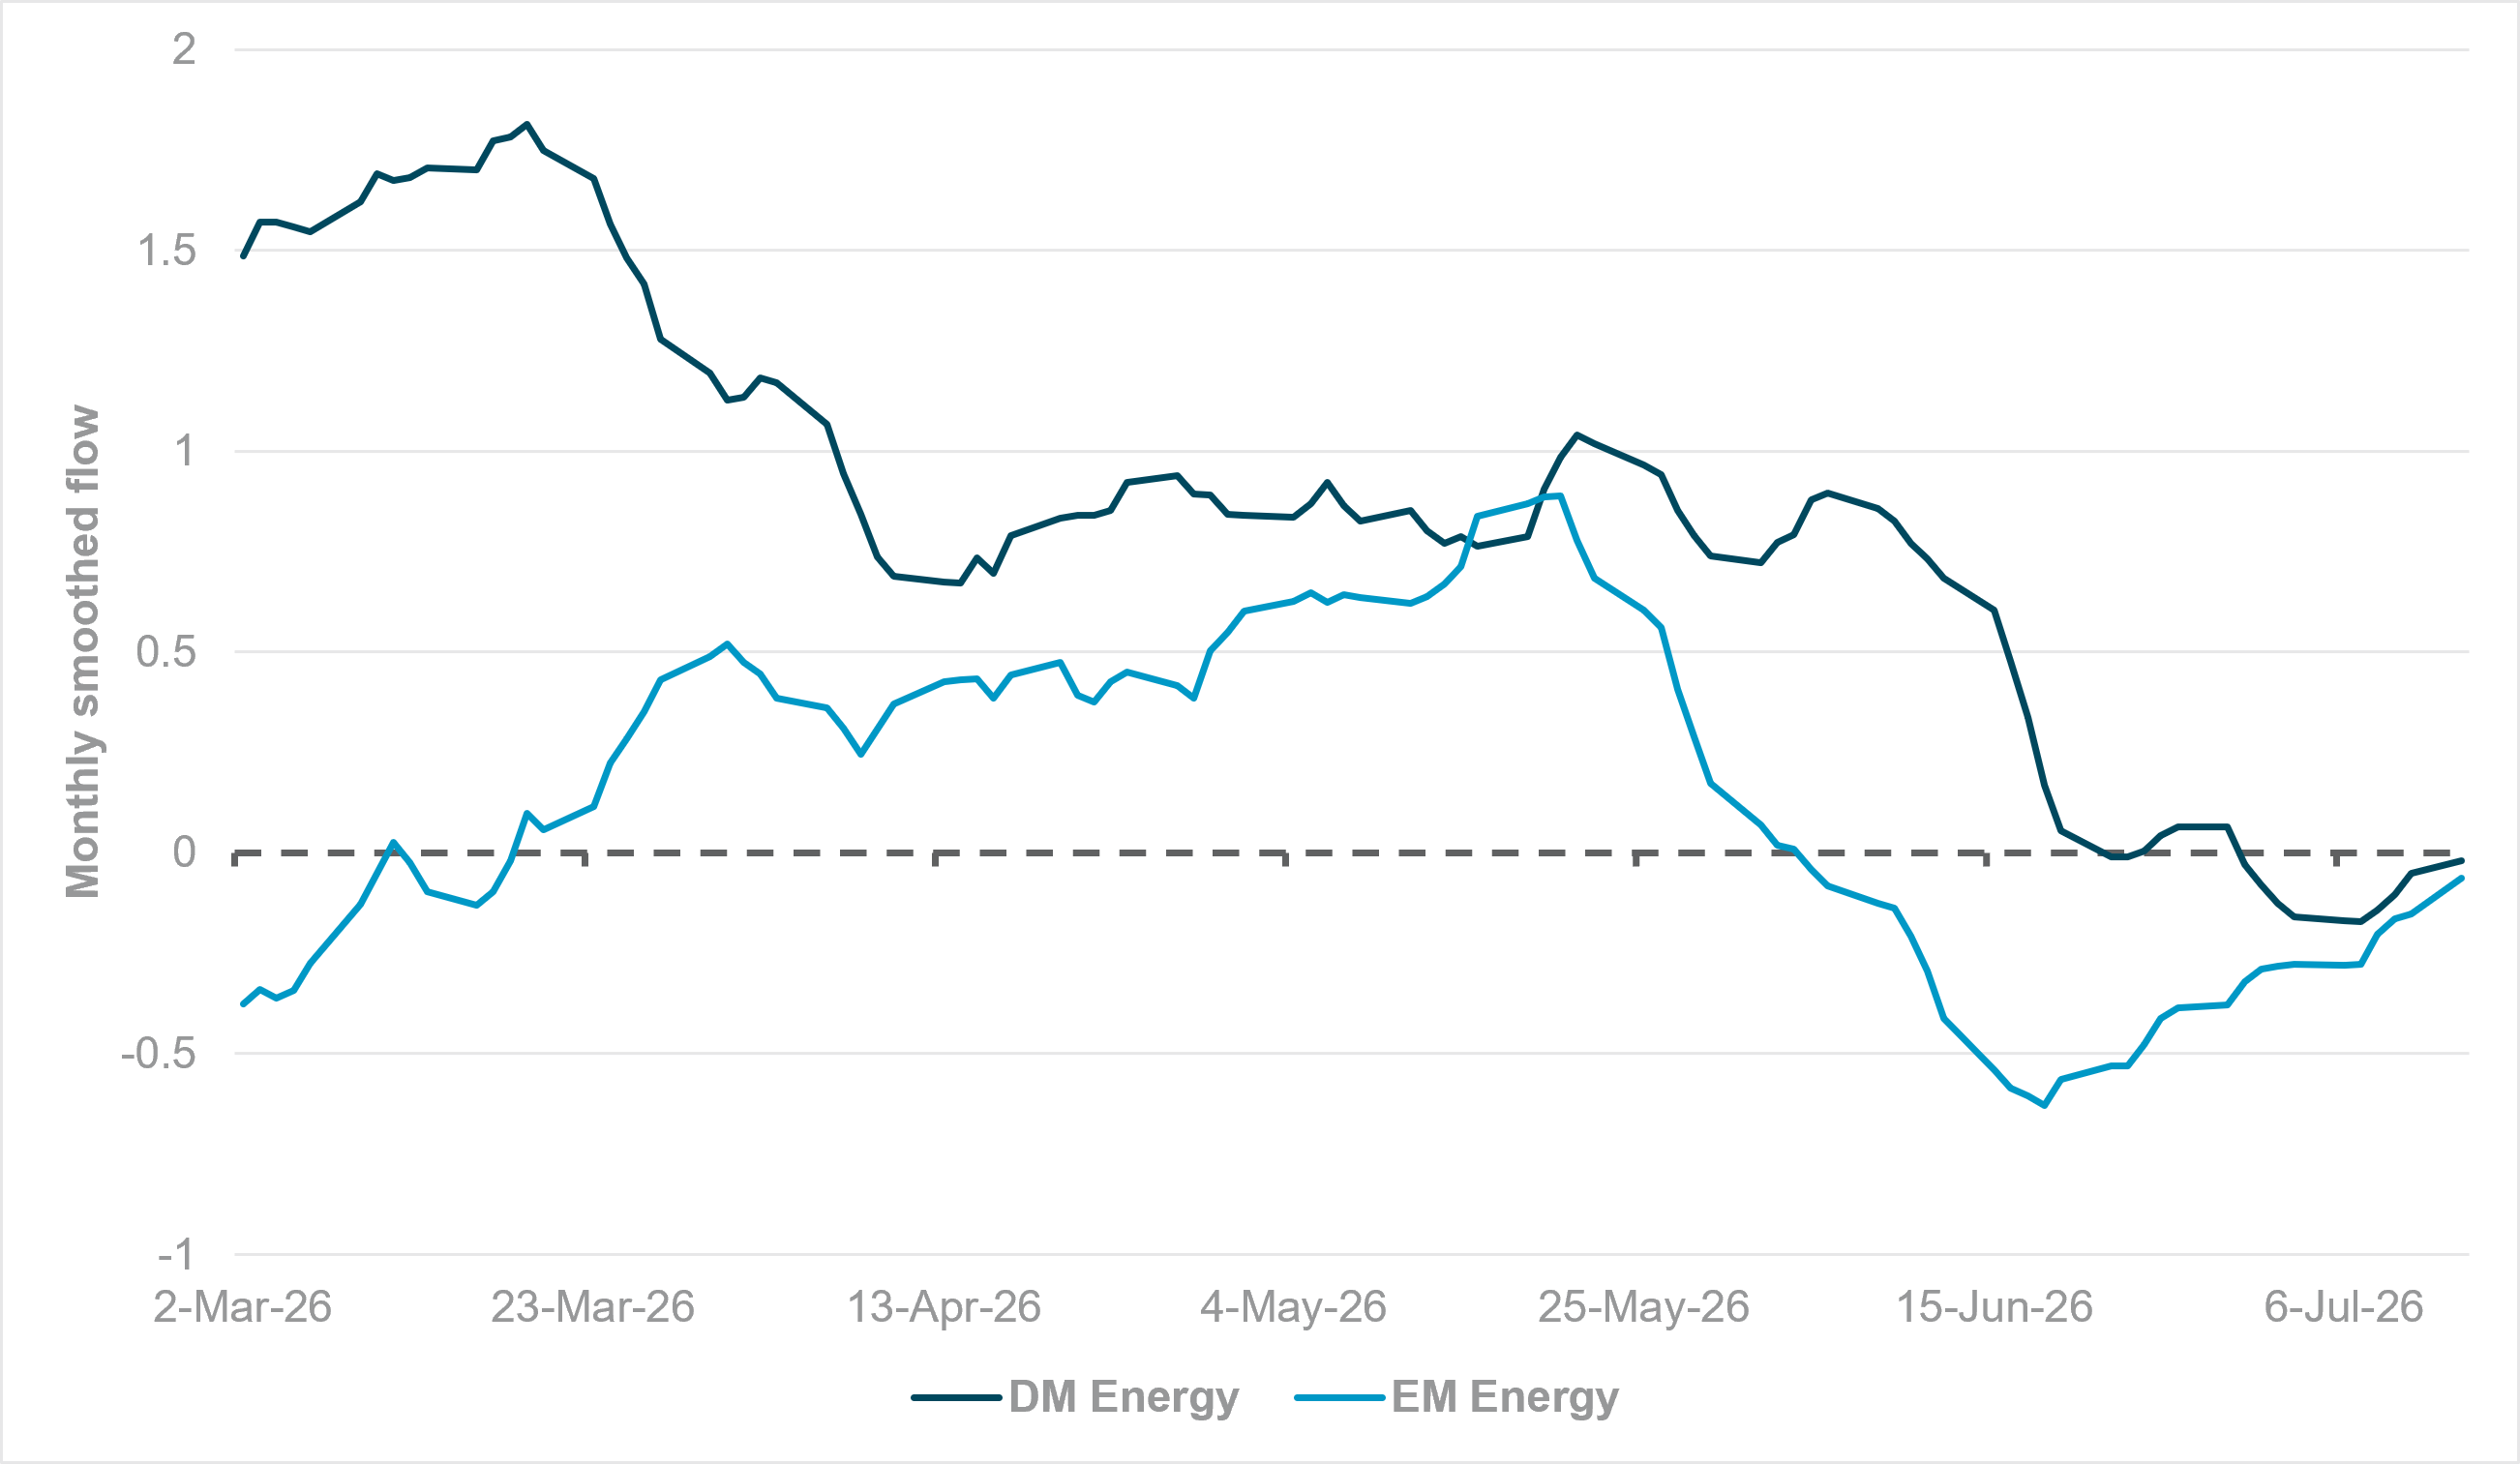
EXHIBIT #2: MONTHLY SMOOTHED FLOWS INTO GLOBAL ENERGY INDUSTRY GROUP (GICS 1010)
Source: BNY
Our take
Energy companies performed strongly in flow terms through May, but the extended ceasefire has led to profit-taking, or at least a pause in purchases. In late June, our client flow turned to net selling in the energy industry group (GICS 1010) across both developed- and emerging-market energy companies for the first time this year. This wasn’t only due to oil prices declining on improved supply and weaker demand. The tech and semiconductor narrative was also very strong at the time, making energy the “low-hanging fruit” for rotation into growth sectors. Recent sessions, however, have generated a modest shift, and global energy now looks set for combined developed- and emerging-market inflows for the first time since late May.
Forward look
Our current view on the conflict argues against a repeat of Q2 for the sector. This isn’t only because full escalation remains a low-probability risk. Demand is weakening globally as central banks continue to tighten financial conditions, while the strong dollar is still limiting meaningful gains in global commodity prices. Based on U.S. industry group equity-flow alignment, our clients are currently showing vigilance against inflation in their allocations. However, the inflation concerns highlighted by recent Fed commentary are broad based, not exclusively energy driven. This should limit the potential for strong flows into energy, but we expect moderately positive flow averages and a meaningful lift in holdings until there is greater clarity on the situation in the Gulf.
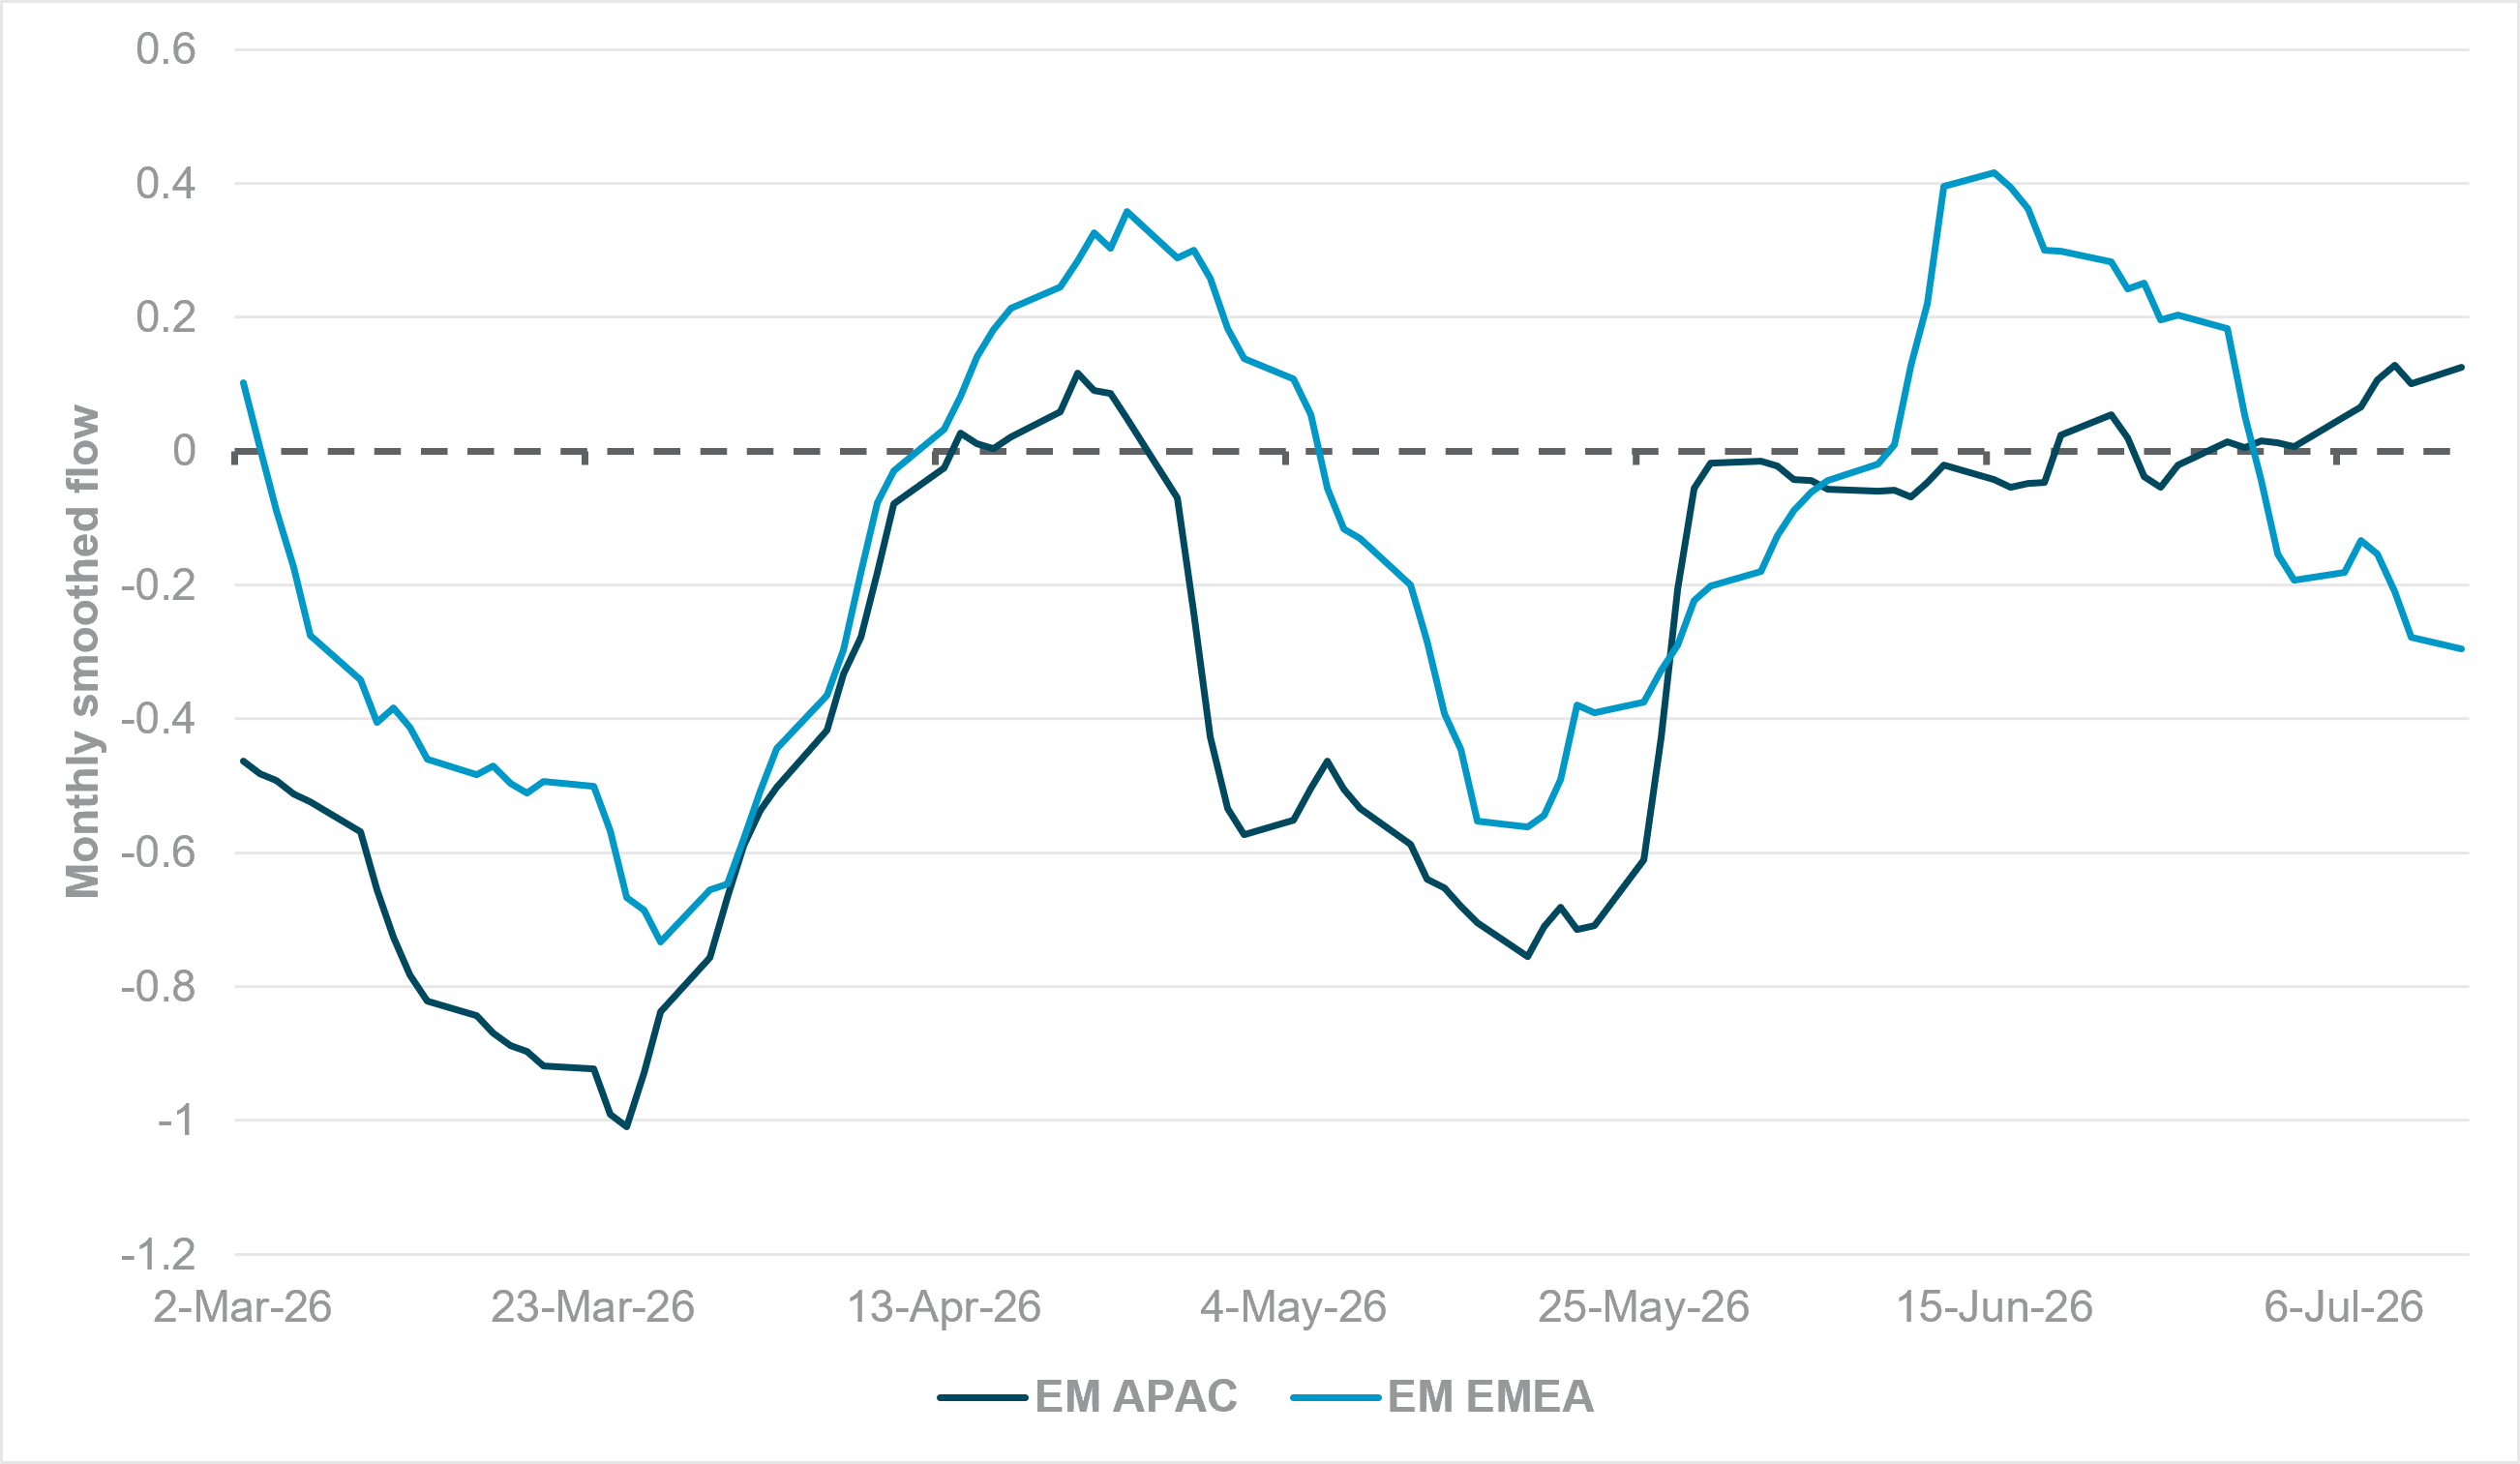
EXHIBIT #3: MONTHLY SMOOTHED FLOWS INTO EM APAC AND EM EMEA DEBT
Source: BNY
Our take
Fixed income is a more difficult asset class in which to express a positive view on higher energy prices. Inflation affects duration regardless of its source, and global bond markets are already fragile because of fears of a hawkish Fed pivot and persistent concerns over fiscal health. During the initial phases of the conflict, the heaviest duration outflows were concentrated among emerging-market oil importers. The sharp rise in import bills triggered concerns over balance-of-payments pressure: energy stabilization funds in Southeast Asia were depleted quickly, and global reserve holdings fell significantly in March. Our data show severe selling in EM APAC and EM EMEA sovereign debt toward the end of March. Recovery flows have materialized since then, but conviction remains light.
Forward look
Under-positioning in these markets reflects the credible response from authorities. Although fiscal support came through subsidies and tax relief, cutbacks elsewhere were swift, and emerging-market governments displayed far greater resilience than in 2022–2023. Central banks also hiked aggressively to stabilize currencies, and external conditions improved quickly. The lack of inflows at present reflects two factors. First, the supply situation is unlikely to improve materially, so a permanent “supply discount” is being reflected in emerging-market duration. Second, the Fed is still playing a major role, and the case for a comprehensive recovery in non-commodity-exporting EM fixed income remains weak until the Fed path is fully set. For existing positions, higher U.S. rates also point to a pick-up in FX hedging and reduced aggregate exposure. EM debt financial conditions are likely to remain tight, but governments such as Hungary and Indonesia have acknowledged the need to maintain fiscal credibility and are demonstrating restraint. This reduces the case for renewed EM debt selling, but a different cycle is needed for renewed accumulation.
Oil hedging needs to rise. In FX, NOK and BRL have room to take leadership on carry and terms-of-trade grounds, especially if the Fed avoids further tightening for now. Equity flows and holdings also have significant room to recover, particularly among emerging-market producers. EM duration for oil importers is harder to own given tighter policy and energy resilience, while FX hedging is likely to rise until Fed expectations peak.