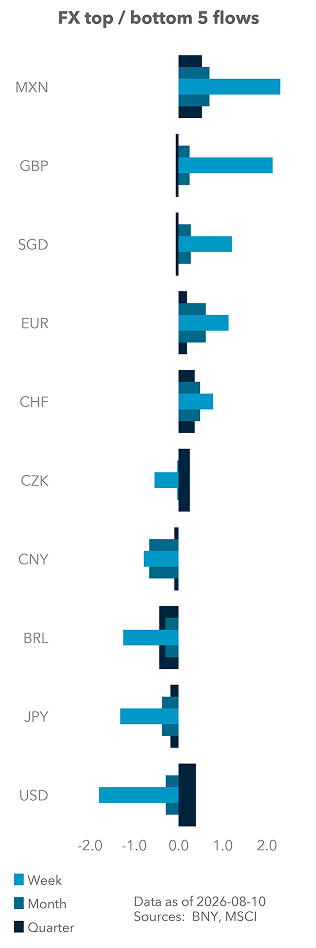
No commodity bid from “dovish Fed”
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.

Geoff Yu
Time to Read: 5 minutes
A less hawkish Fed has weakened the dollar but hasn’t generated a broader commodity bid. Commodity FX buying faded quickly, institutional investors remain sellers of metals and miners, and EM commodity sovereign debt has struggled despite lower U.S. real yields. The missing ingredient remains growth: without stronger global demand, particularly from China, easier financial conditions alone aren’t enough to sustain commodity-linked assets.
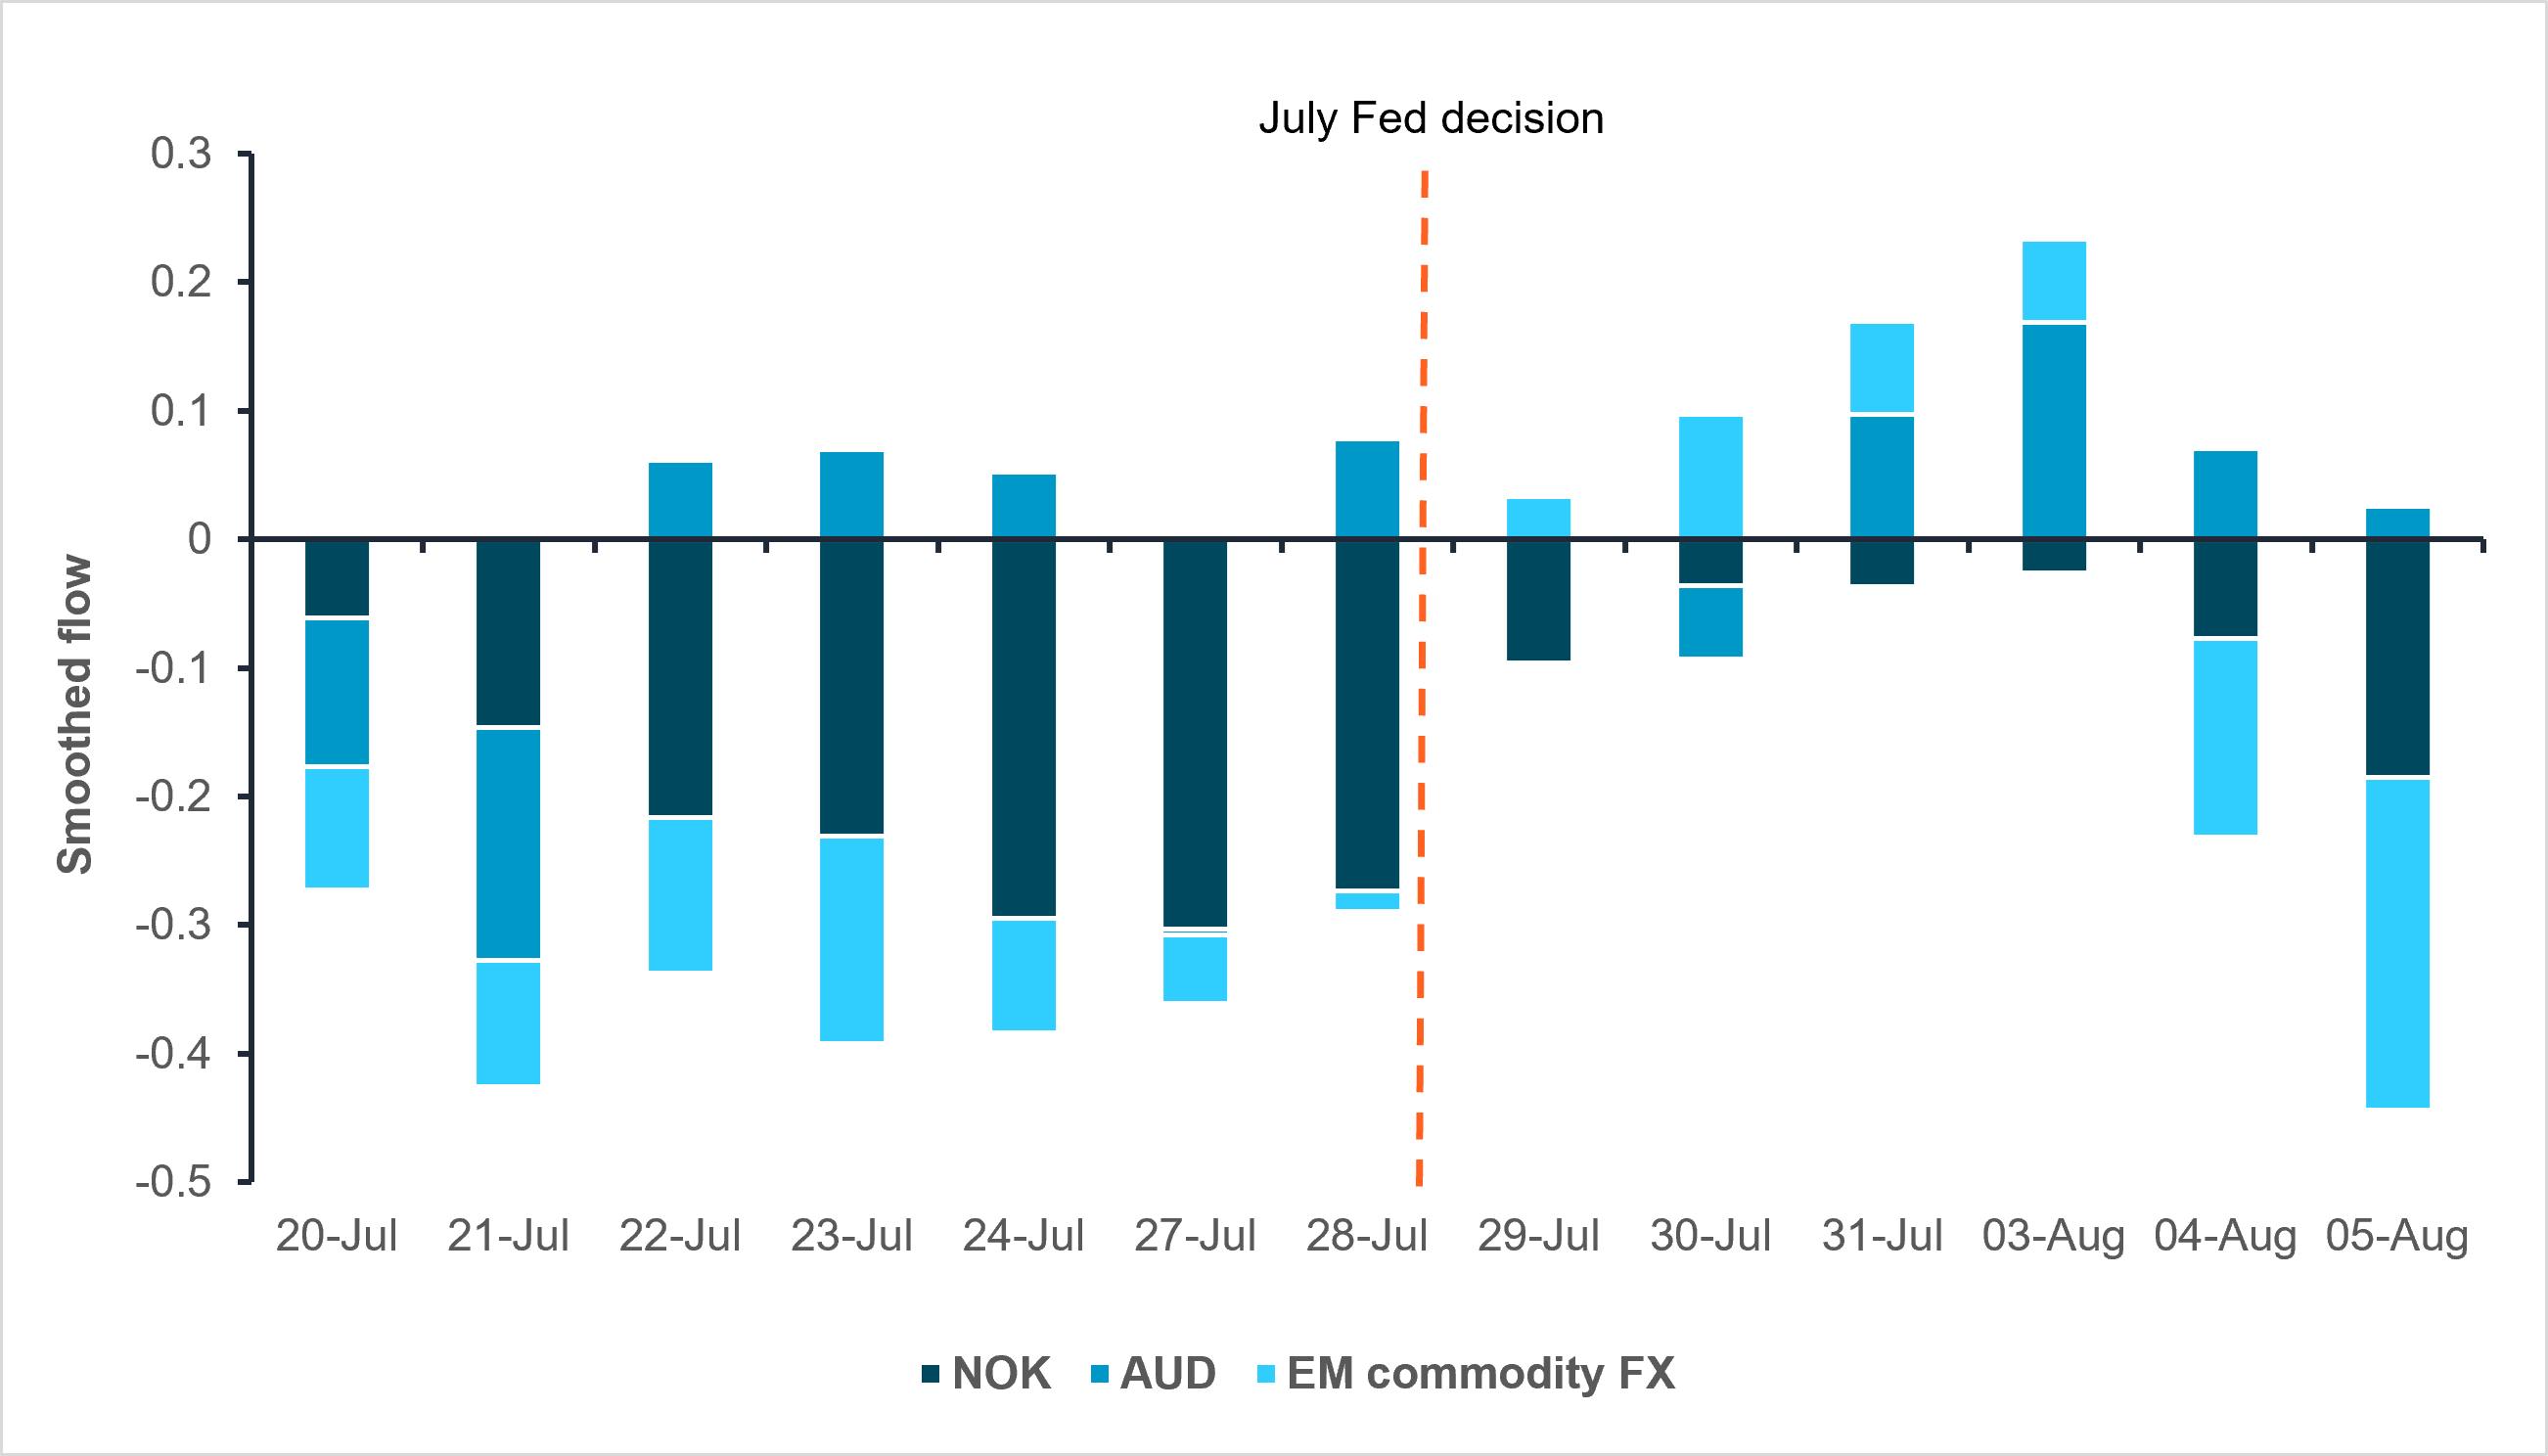
EXHIBIT #1: WEEKLY SMOOTHED FLOWS – NOK, AUD, EM COMMODITY FX BASKET (CLP, BRL, ZAR)
Source: BNY
Our take
Even before last Friday’s payroll numbers, iFlow showed dollar hedges rising again. Mean reversion was already overdue, but the Fed decision and subsequent “credibility” narrative accelerated the process. We have always viewed extreme positioning as an amplifier of price action, and the dollar is adjusting accordingly. However, that adjustment is still playing out across the majors. Gold aside, there’s still no sign of the broad commodity move needed to revive the “debasement” trade that dominated markets in January and February. In FX, we can isolate some of the cleanest commodity currencies: NOK, AUD and an EM basket of CLP, ZAR and BRL. In the full trading week after the Fed decision, there wasn’t a single session when the entire group was net bought; by a week later, aggregate flows were again moving toward net selling.
Forward look
The Reserve Bank of Australia and Norges Bank retain the highest nominal rates in G10, but idiosyncratic risks remain too high to generate a sufficient front-end real-rate gap vs. USD. Stagflation and non-commodity productivity challenges have beset Australia and Norway for much of the past two decades, forcing central banks to remain vigilant while limiting their willingness to over-tighten and aggravate household imbalances. This constraint now looks more acute in Australia.
Meanwhile, as the Iran conflict has broadly stabilized in market terms, commodity-linked economies are more willing to return to earlier easing paths and prevent real rates from widening again. South Africa is a good example: the Reserve Bank of South Africa surprised markets by holding rates in July and maintained a forward-looking bias, with expectations of weaker inflation opening the door to a policy pivot. The global growth priority is increasingly clear, creating a hard ceiling for carry performance unless the Fed starts signaling cuts.
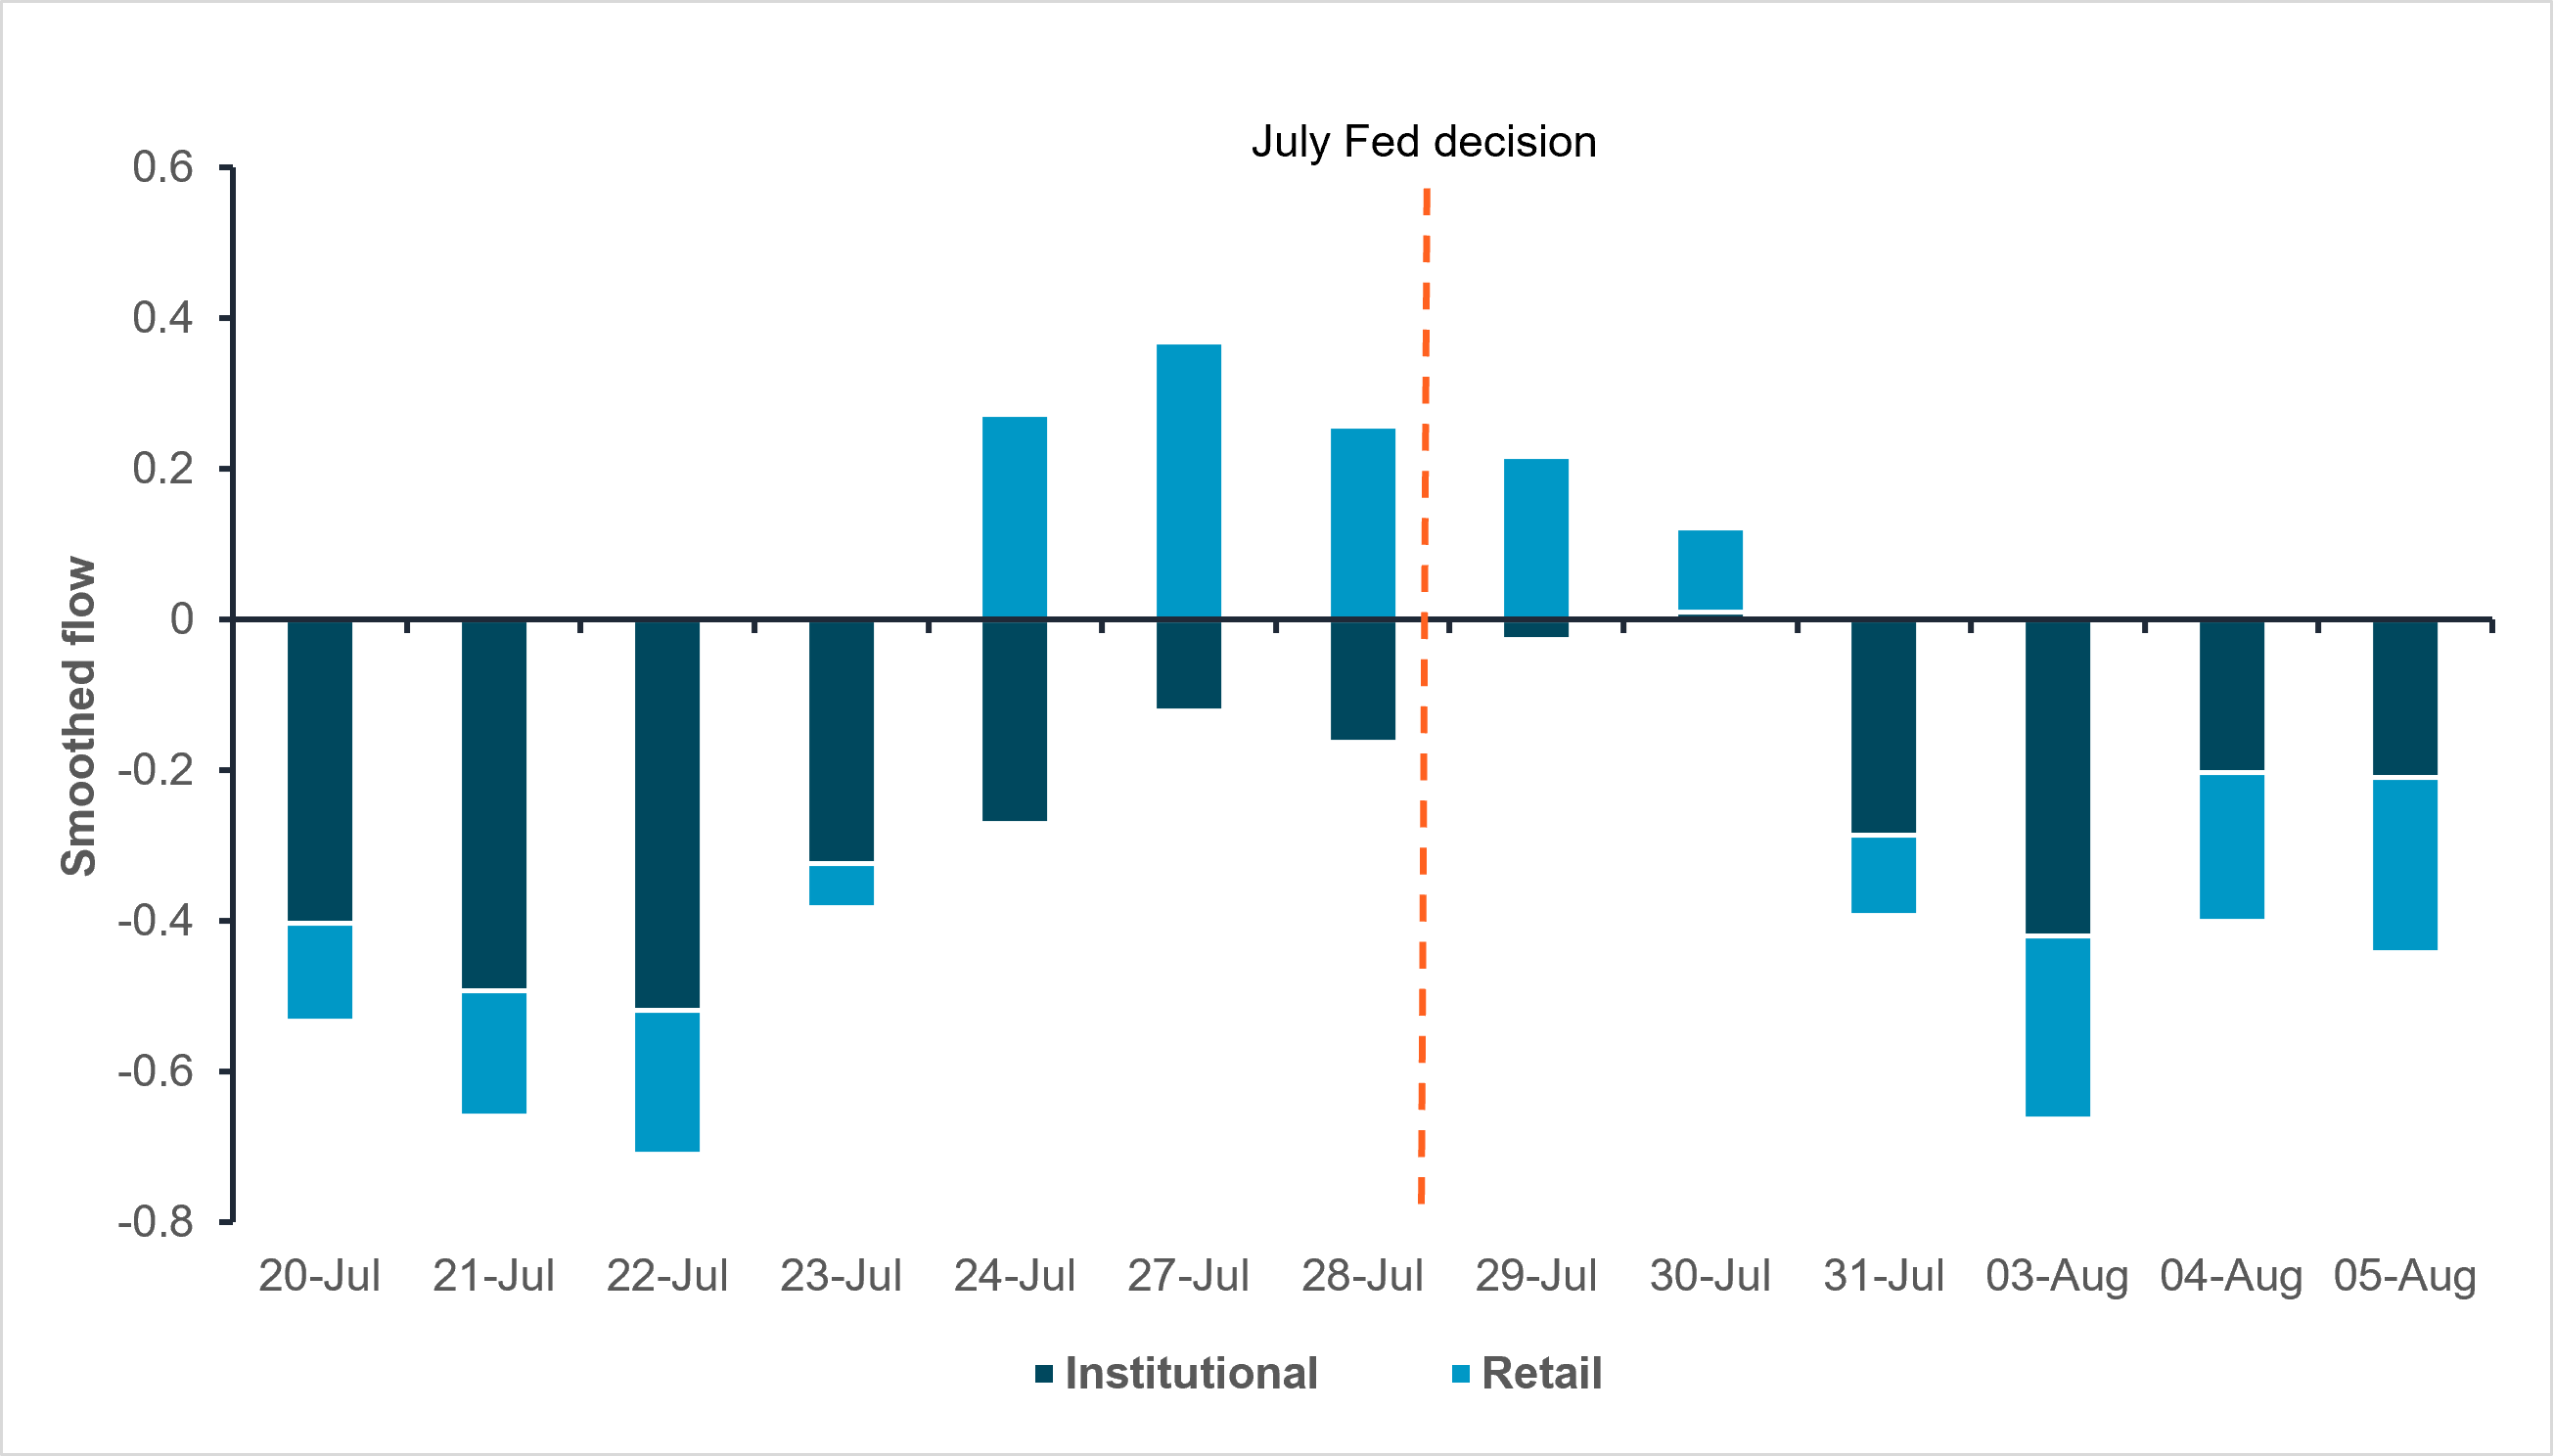
EXHIBIT #2: WEEKLY SMOOTHED FLOW, METALS & MINING (GICS LEVEL 3)
Source: BNY
Our take
Flows into Metals & Mining (GICS Level 3) show a clear behavioral split between client groups. Institutional flows match the FX narrative: global growth is soft, especially in China, and the near-term earnings outlook remains weak. At best, the Fed decision halted selling for a trading day or two before institutional outflows resumed. This creates clear narrative asymmetry. A hawkish Fed could tighten global financial conditions and hurt commodities; but if the Fed is right to be dovish, as suggested by the July payrolls report, the weaker growth backdrop is also unsupportive. Either way, institutional investors still see little reason to add commodity exposure.
In contrast, retail investors were much more tactical. Their flow trend broadly matched institutional equities until just before the Fed decision, when buying of Metals & Mining stocks turned strongly positive at a magnitude that can’t be explained by mean reversion alone. In equities, this was one of the clearest ways to position for a dovish or non-hawkish Fed, and the trade was initially rewarded. Profit-taking came quickly, however, and retail flows have since converged with institutional flows again. There is therefore little disagreement on the broader global macro narrative, but retail investors were nimble in positioning for a Warsh “disappoint.”
Forward look
Given the price action in precious metals and commodities in January and February, retail investors would normally be quick to re-enter precious metals or associated positions such as PEN and ZAR. That isn’t happening at present. Copper is the exception, although tariff-related factors are also in play and may not translate cleanly into the wider commodity complex. The message is that Fed credibility matters, but correlated trades across global assets also need a credible growth backstop. That’s difficult to achieve if U.S. data begin to weaken materially. Without stronger global demand, a weaker dollar alone is unlikely to recreate the commodity trade seen earlier in the year.
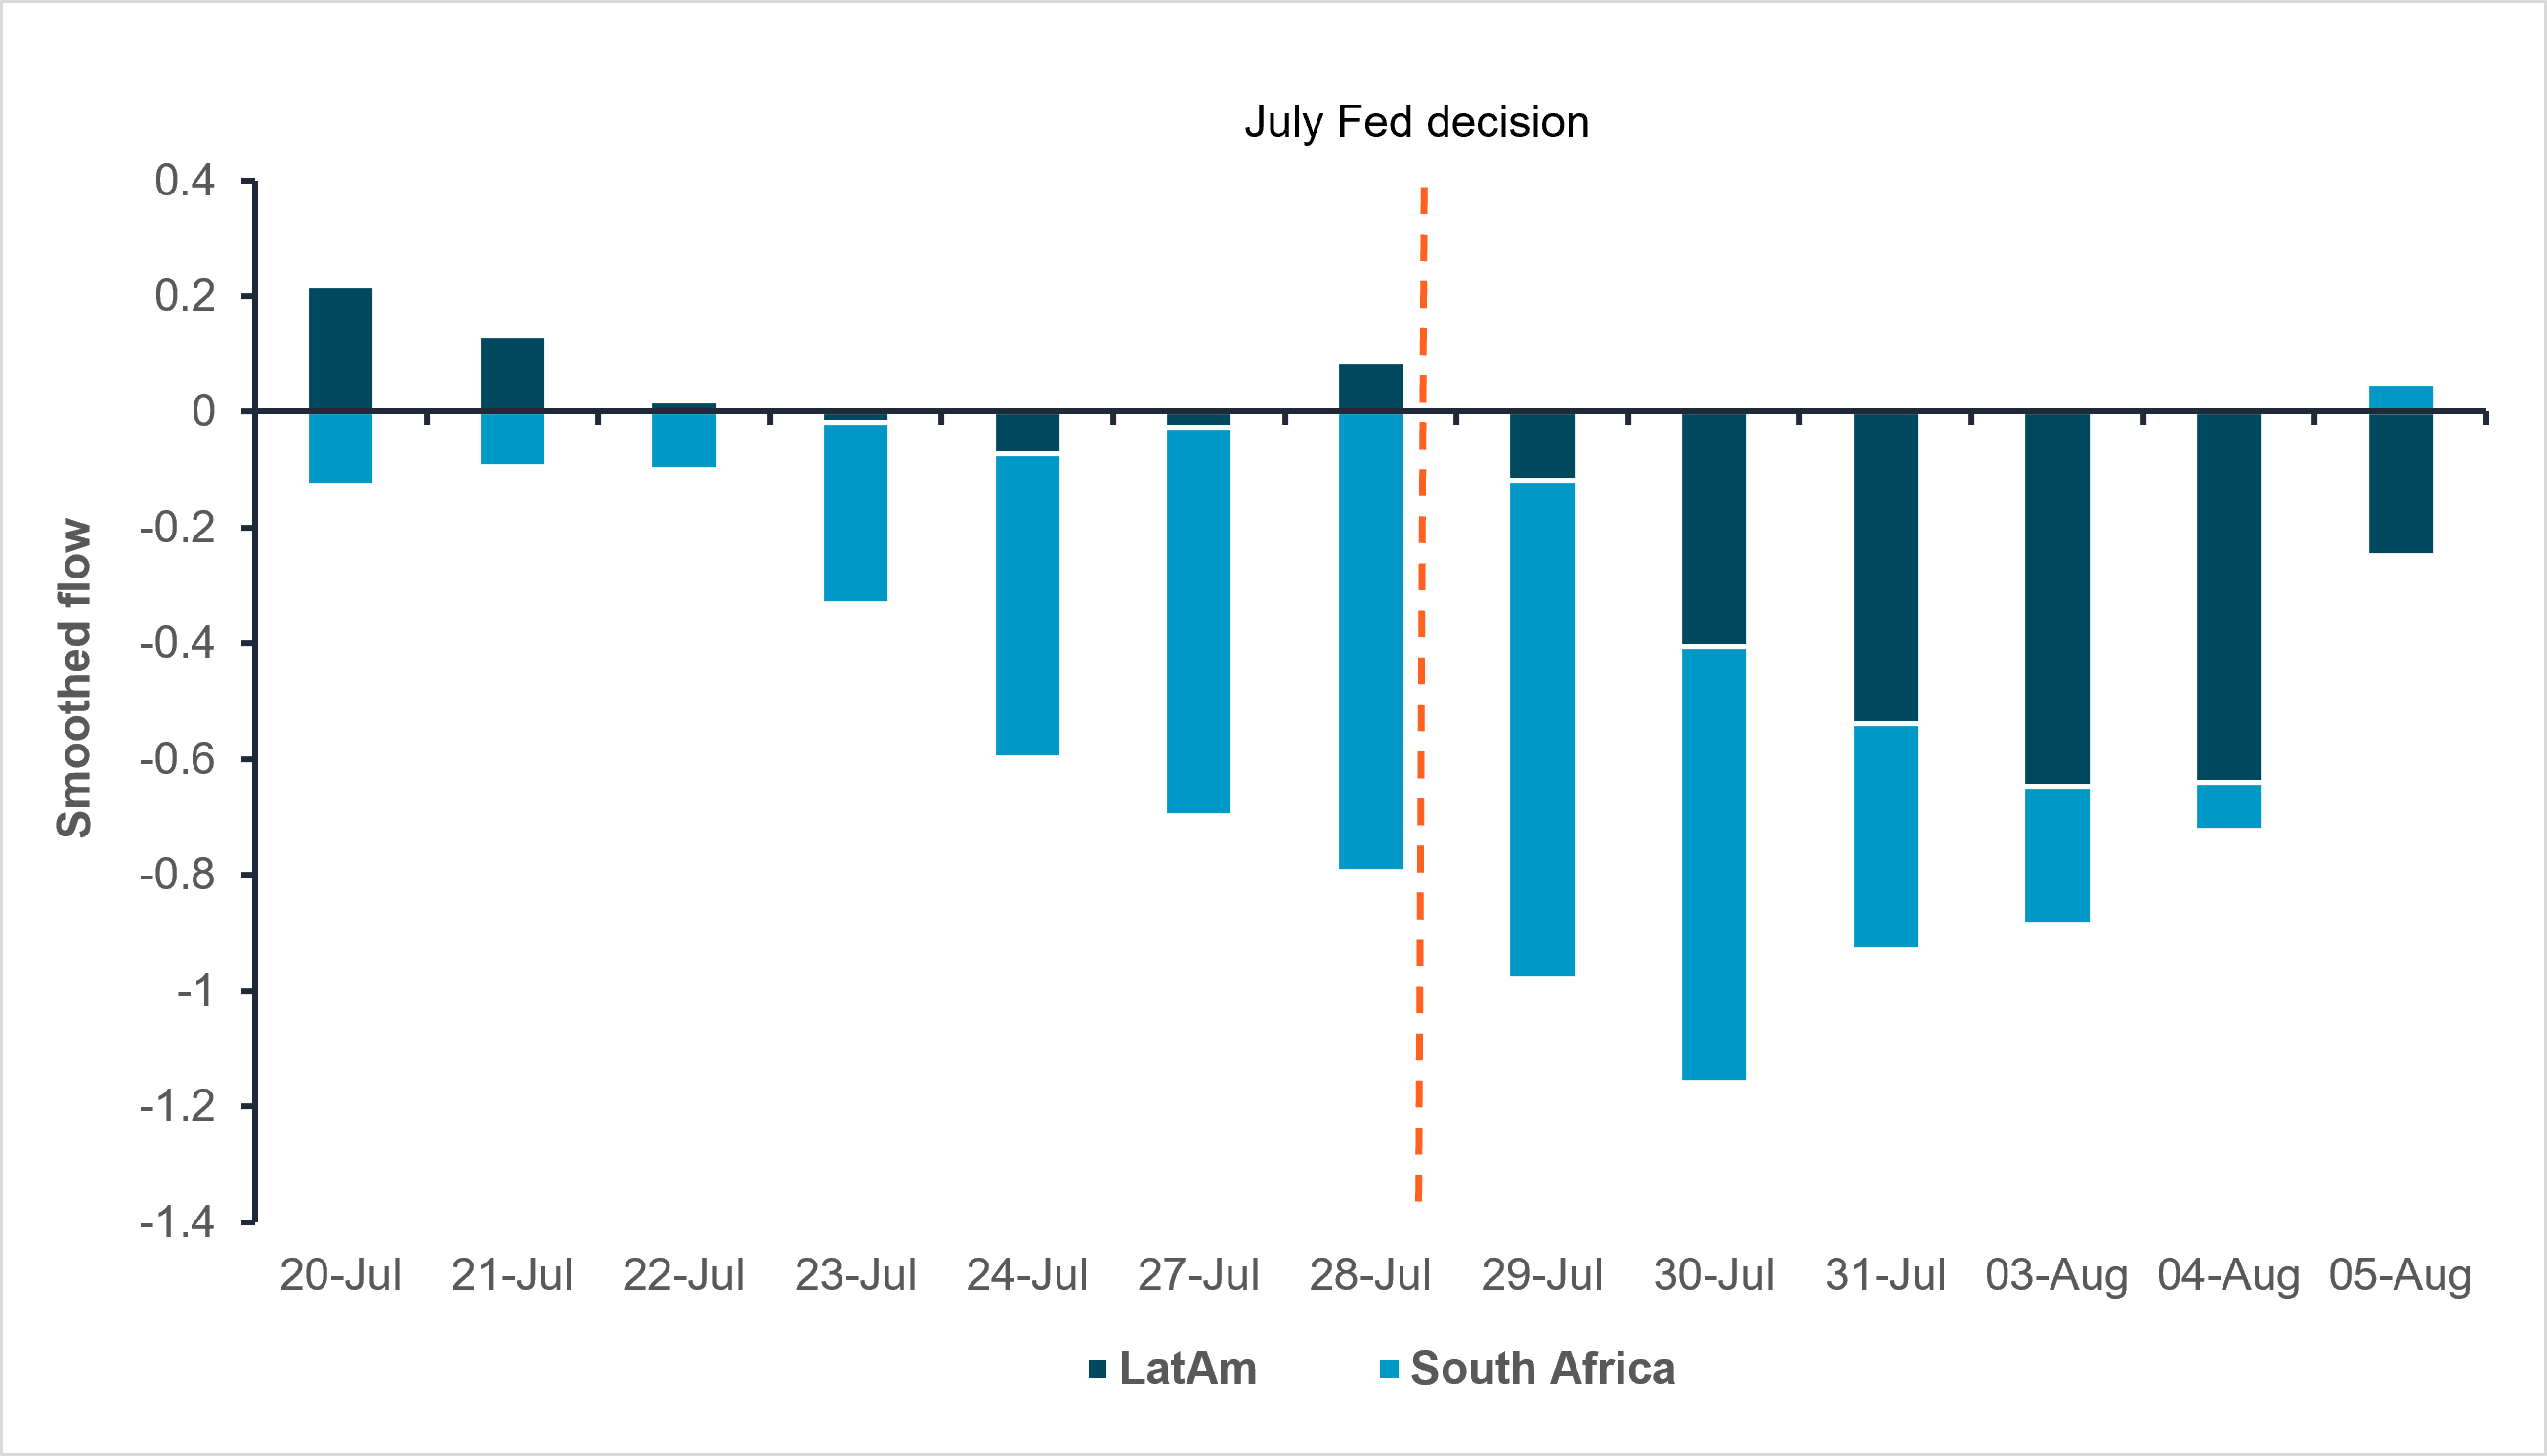
EXHIBIT #3: WEEKLY SMOOTHED FLOW, LATIN AMERICA AND SOUTH AFRICA SOVEREIGN DEBT
Source: BNY
Our take
Sovereign debt issued by commodity-based EM economies normally benefits from USD-funded trades in a dovish Fed environment, but selling accelerated after the Fed decision. There are some early signs of reversal, yet South Africa, which should be one of the clearest beneficiaries of higher gold prices, failed to register a single inflow session until a full week after the decision. This suggests the environment remains difficult for EM duration. Front- and back-end nominal yields are simply not high enough to compensate for inflation risk and fiscal stress. Given the current global growth outlook and the unexpected fiscal burden arising from the Iran conflict, we have some sympathy with this view. Central banks can’t impose fiscal discipline in the way bond markets can, and the required price adjustment hasn’t yet been reached for a sustained EM asset recovery.
Forward look
Despite high inflation, developed market sovereign bonds found strong domestic support throughout the Iran conflict. Local investors don’t face FX risk, while limited movement in breakevens keeps real yields attractive. This remains broadly true in Europe, but the Fed decision was a game-changer for U.S. breakevens: the 5y5y forward measure has risen 20bp over the past month and almost 30bp from its March lows. Even so, the decline in U.S. real yields has been insufficient to generate strong flows into commodity-linked bonds because Treasury curve steepening has offset much of the benefit. The weaker-dollar view is intact, but that doesn’t automatically translate into stronger commodity prices or stronger commodity-linked economies, particularly while U.S. investors remain comfortable with domestic nominal and real yields. Commodity economies therefore need to generate their own growth and total-return narrative before they can fully benefit from easier global financial conditions. The earlier combination of a wide yield advantage over the U.S. and strong Chinese demand boosting export revenues isn’t returning.
Call to action
Don’t chase the weaker-dollar commodity trade yet. Keep commodity FX and EM duration exposure selective until flows confirm a broader growth recovery, not just easier Fed expectations. Favor tactical opportunities where domestic fundamentals are improving, but require stronger institutional buying in metals, mining, and commodity sovereign debt before adding conviction.