July rebalancing: Favor GBP, sell USD
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.

Geoff Yu
Time to Read: 4 minutes
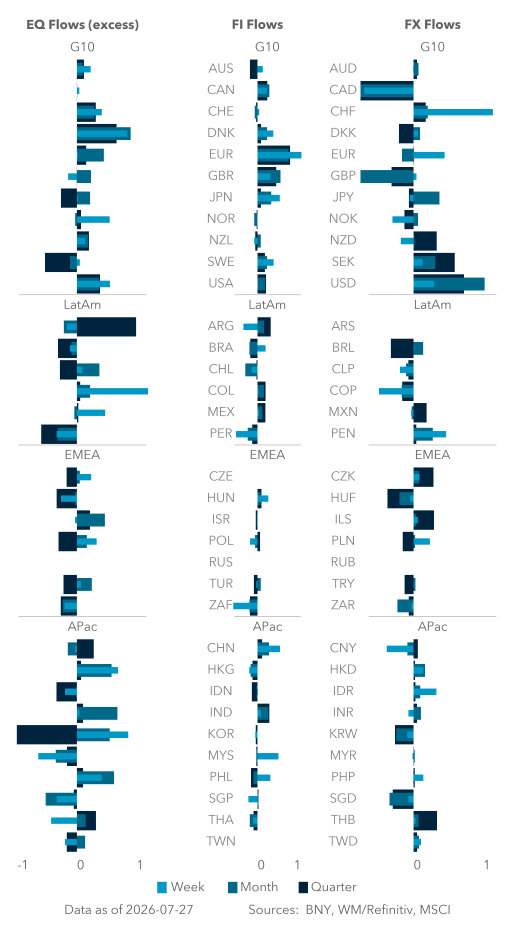
July rebalancing favors GBP and argues for reducing USD exposure through hedging rather than cutting U.S. assets outright. Global equity allocations are at record highs, U.S. ownership remains dominant, and dollar hedge ratios are still low. GBP is the clearest beneficiary because positioning is light across equities, gilts and FX, while USD and INR face the strongest hedging pressure.
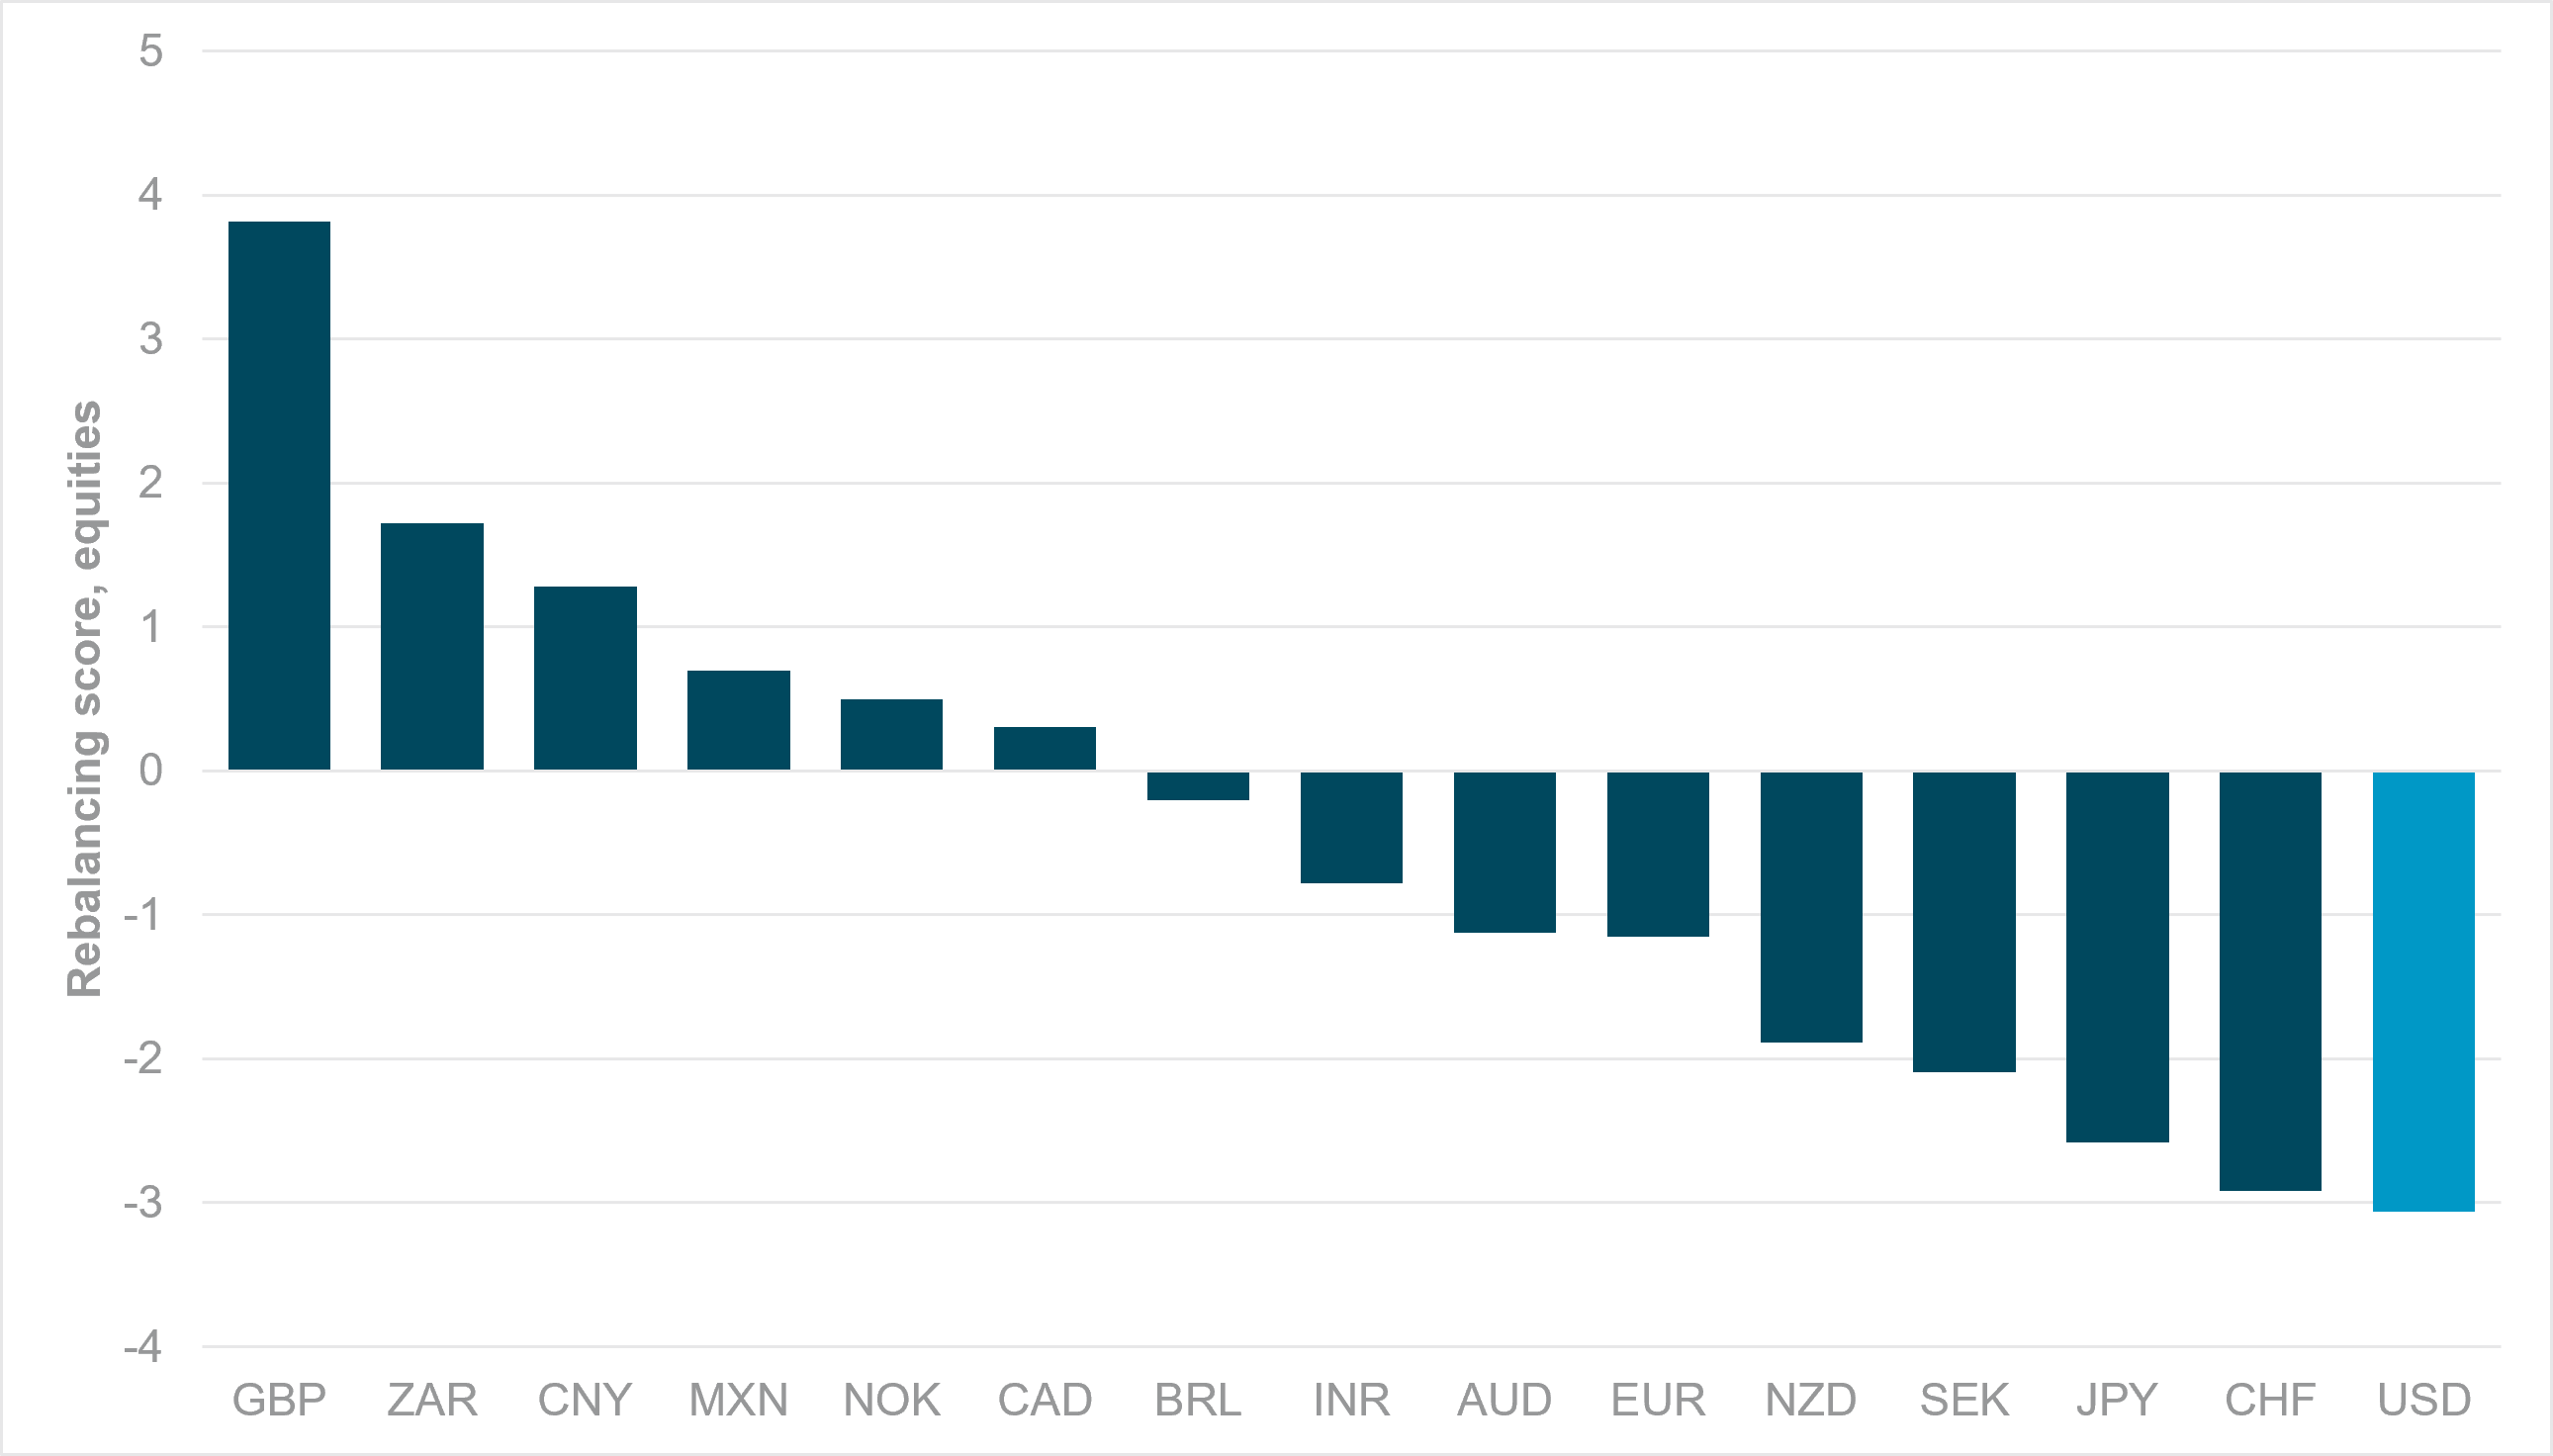
EXHIBIT #1: REBALANCING SCORE BASED ON MARGINAL FX FLOWS AND EQUITY PERFORMANCE
Source: BNY, Bloomberg
Our take
Global equity markets were volatile through the month, while marginal returns remained subdued. Realized currency flows will therefore drive most month-end rebalancing needs.
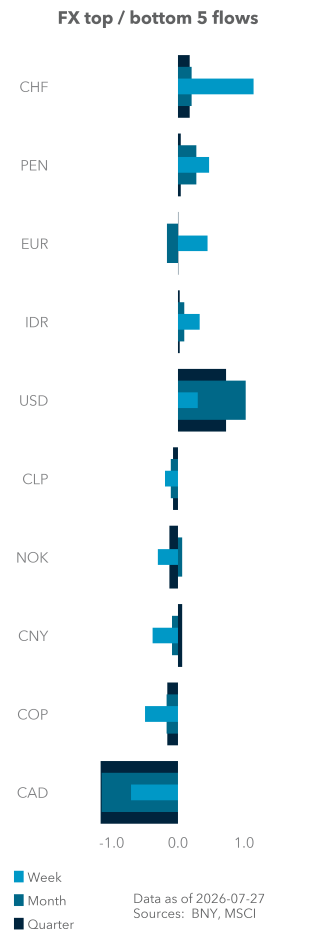
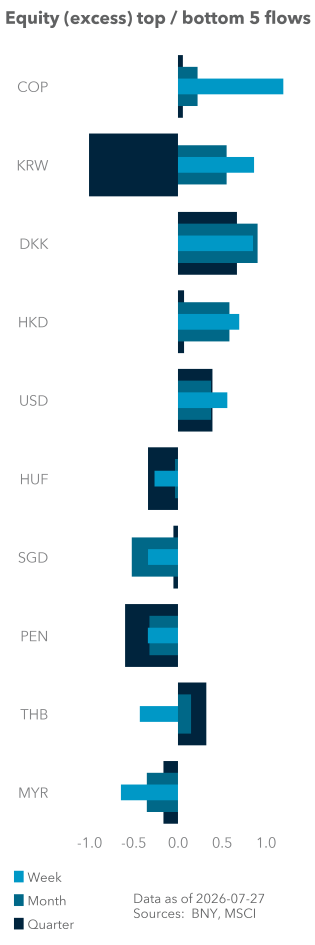
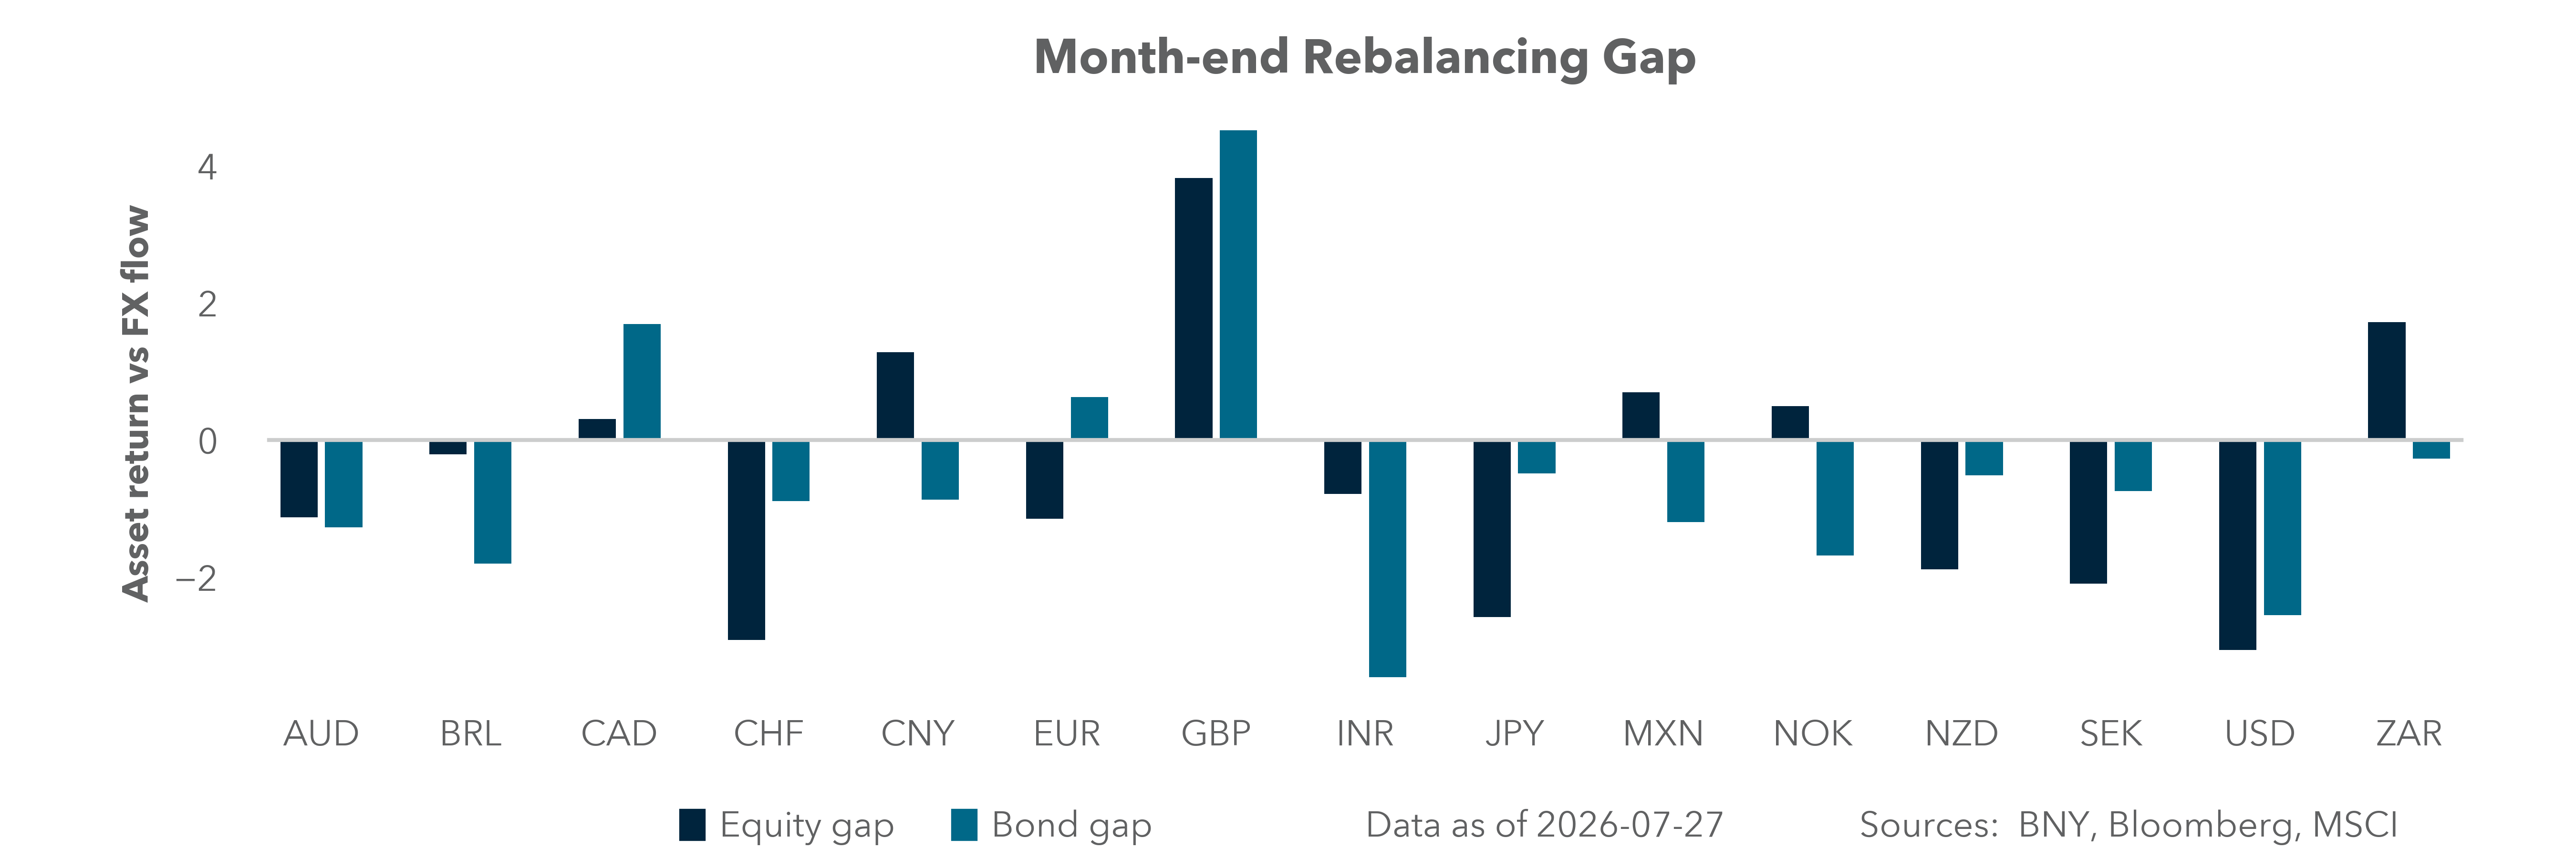
The USD was by far the best-bought currency, with a marginal flow score more than twice that of JPY, the next strongest. This supports our view that cross-border dollar exposure is at a record high: equity and fixed-income ownership remain elevated, while hedge ratios are low. U.S. equities also posted a modestly positive marginal return score, so strong dollar buying and equity gains have produced a large, combined rebalancing signal.
GBP and CAD were the most-sold currencies, with GBP hedging particularly aggressive. FTSE gains were not large enough to offset the currency move, leaving a strong GBP rebalancing signal. CAD is different, as TSX performance has broadly offset currency selling.
Forward look
Falling U.S. equities into month end will reduce total dollar exposure and ease some immediate rebalancing pressure. Even so, existing positions remain lightly hedged, while concerns over equity outflows should encourage further dollar hedging.
The message is unchanged: global exposure to U.S. assets remains historically high and portfolios still need to reduce risk. Increasing FX hedges is the most efficient route without cutting U.S. allocations outright.
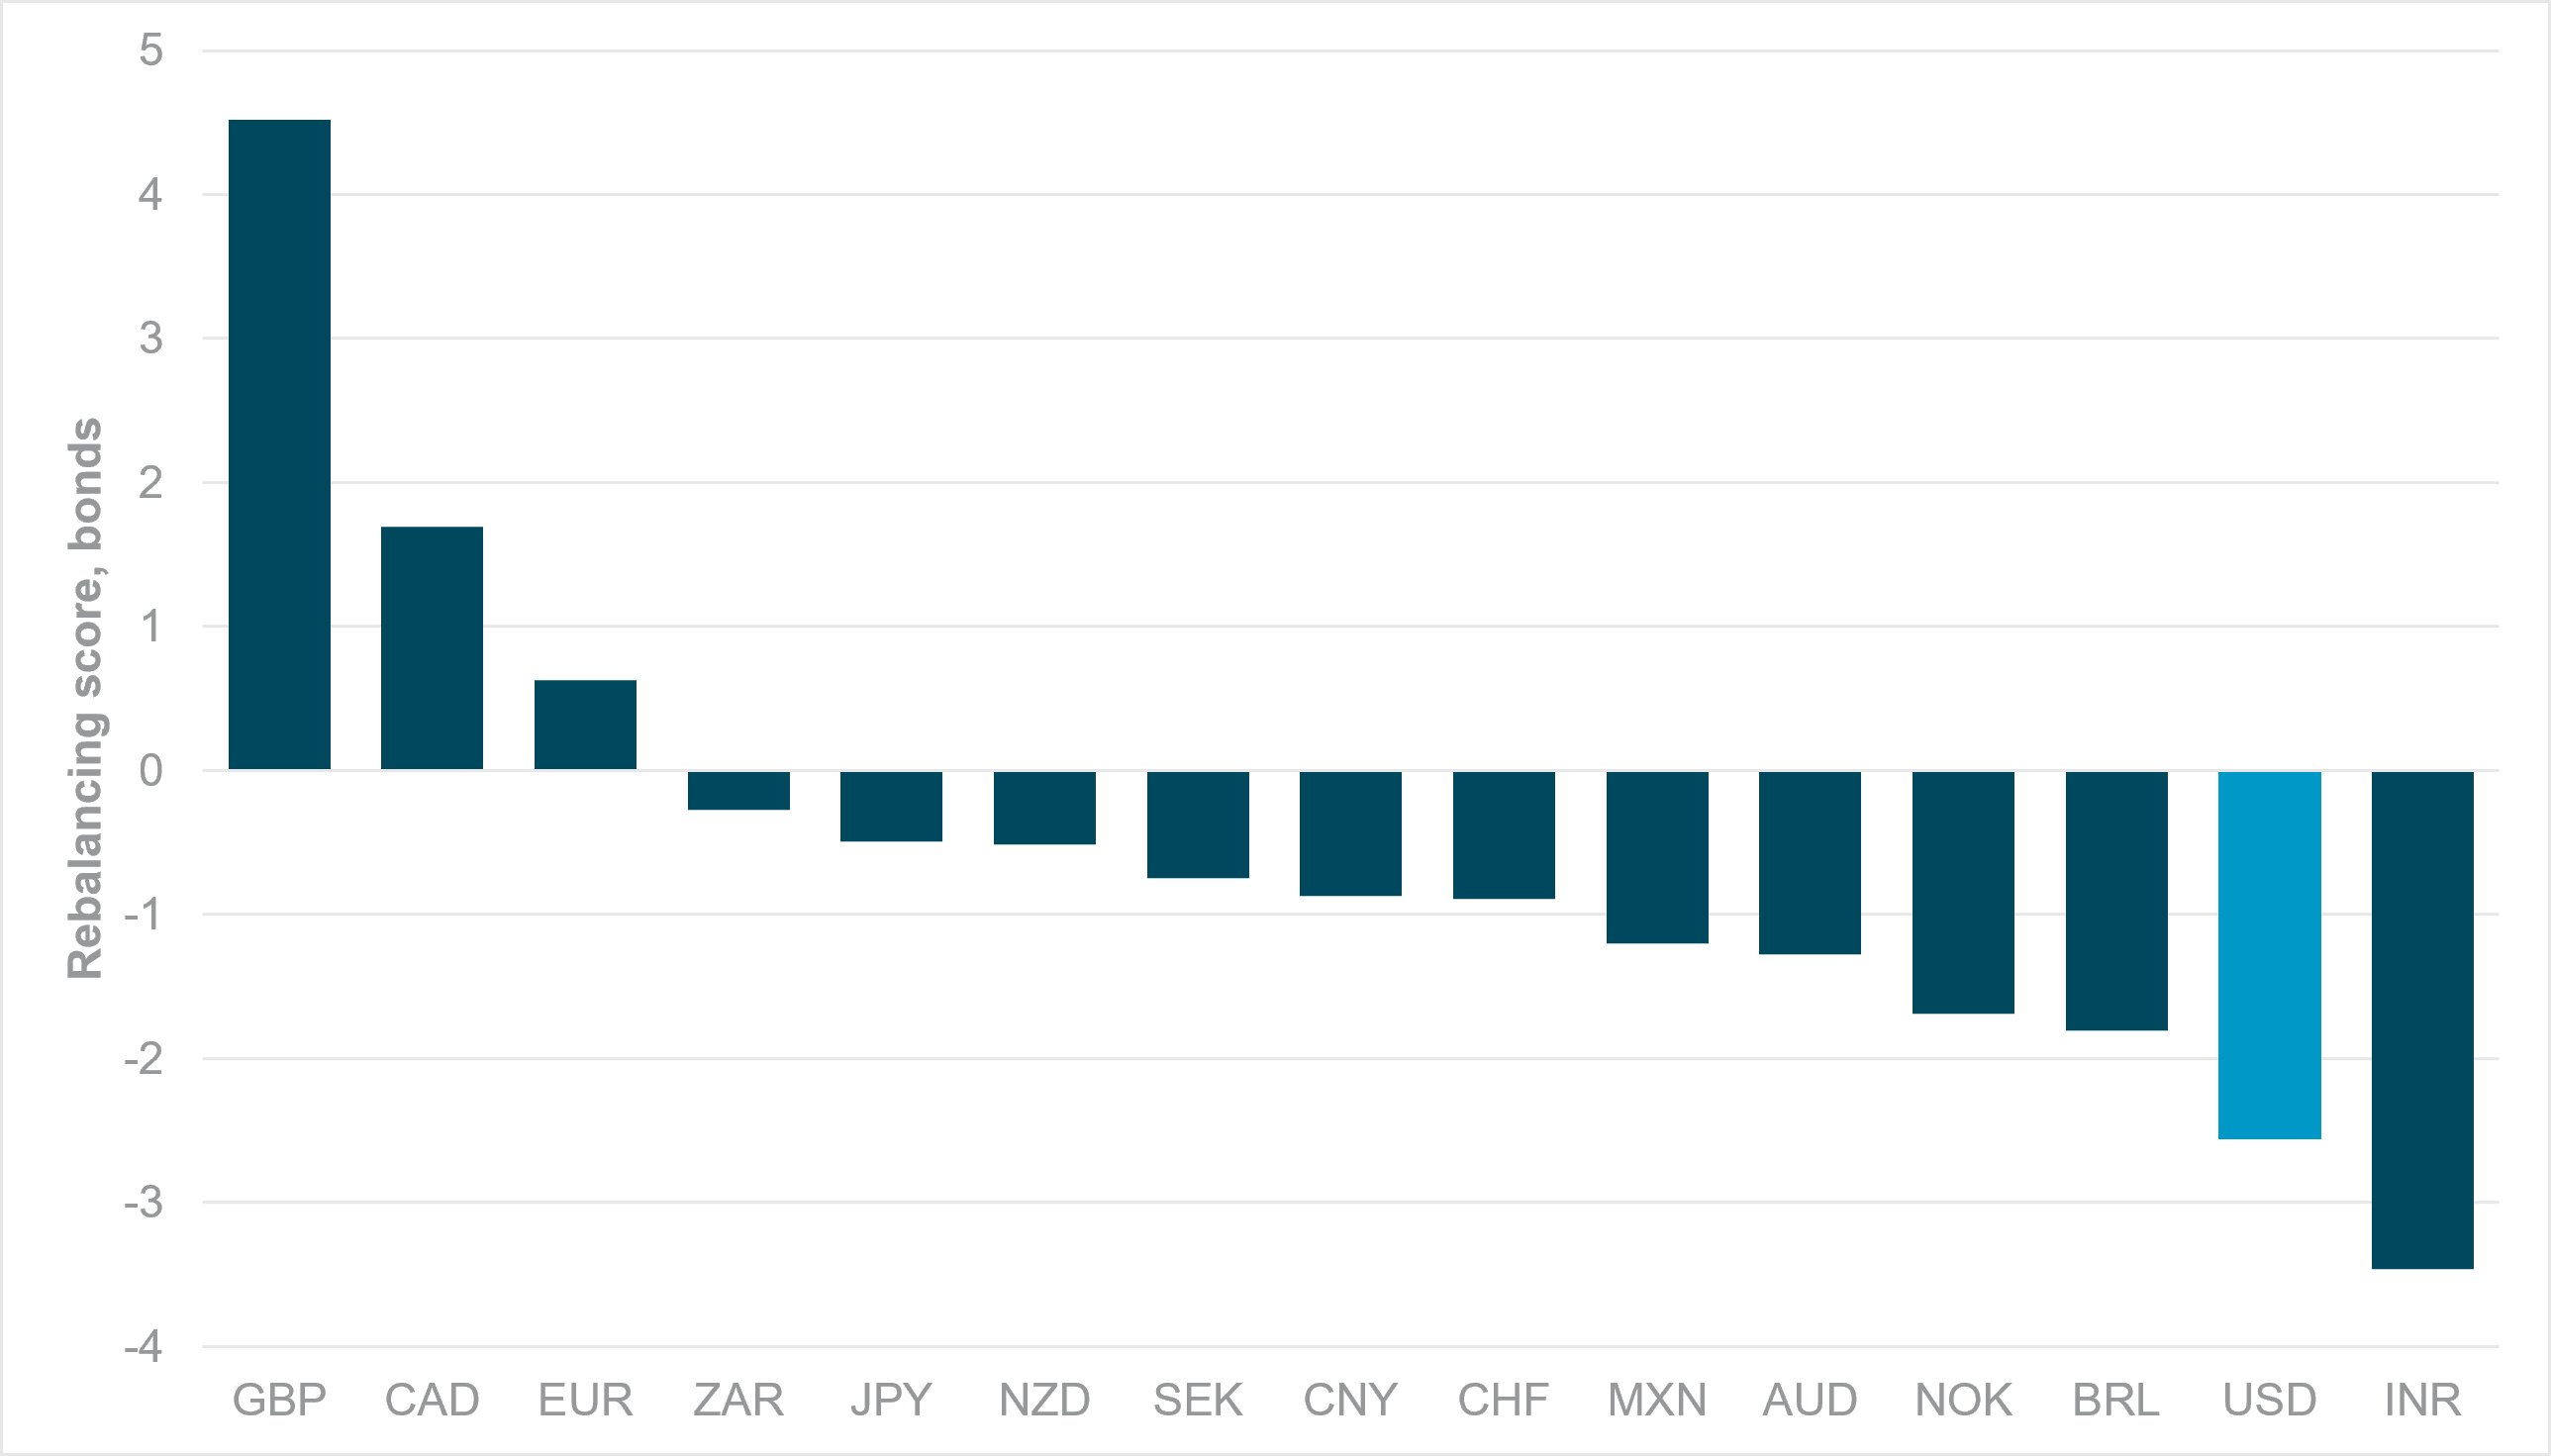
EXHIBIT #2: REBALANCING SCORE BASED ON MARGINAL FX FLOWS AND FIXED-INCOME INDEX PERFORMANCE
Source: BNY, Bloomberg
Our take
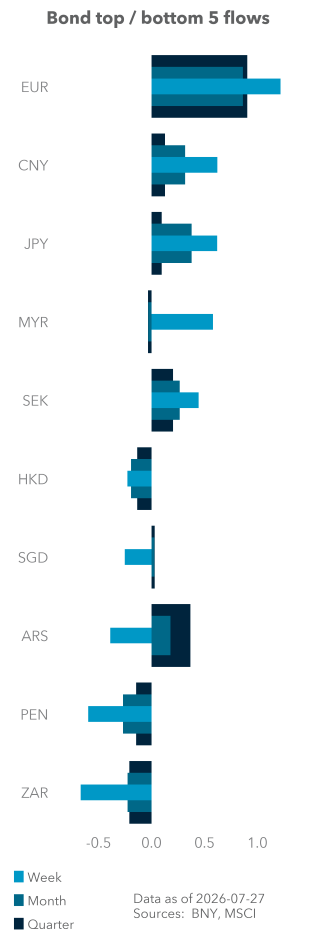
Global fixed-income returns remain positive at month end despite the mid-month rise in energy prices. Japan is the clear outlier as markets question fiscal credibility. U.S. bonds have also underperformed slightly as investors weigh a more hawkish Fed against softer domestic inflation. The USD fixed-income rebalancing signal is therefore weaker than the equity signal, but elevated U.S. bond holdings still create a clear need for more hedging.
Selling pressure is strongest in INR. Like many emerging market (EM) bond markets, Indian duration benefited from lower oil prices during the first weeks of the ceasefire as real rates improved. The latest re-escalation has not erased those gains, and Indian bonds have outperformed the major markets we track. With INR flows broadly flat over the month, FX exposure has risen and hedging demand has increased with it.
GBP is the only currency already showing a strong hedging component, while local fixed-income returns were broadly flat. Our data still show almost no cross-border demand for gilts. This creates pressure either to reduce hedges or increase gilt allocations outright, but duration demand is likely to remain limited until the new government delivers a full budget.
Forward look
July’s duration gains are creating meaningful rebalancing needs, especially across higher-beta currencies. The real-rate outlook is more difficult, however, as central banks show growing reluctance to tighten further. Indonesia and South Africa both surprised with policy holds despite inflation pressure, while parts of the ECB are also turning less hawkish.
Global supply chains will take time to normalize, leaving non-U.S. real rates vulnerable if current market pricing persists. This strengthens the case for greater FX hedging across fixed-income portfolios.
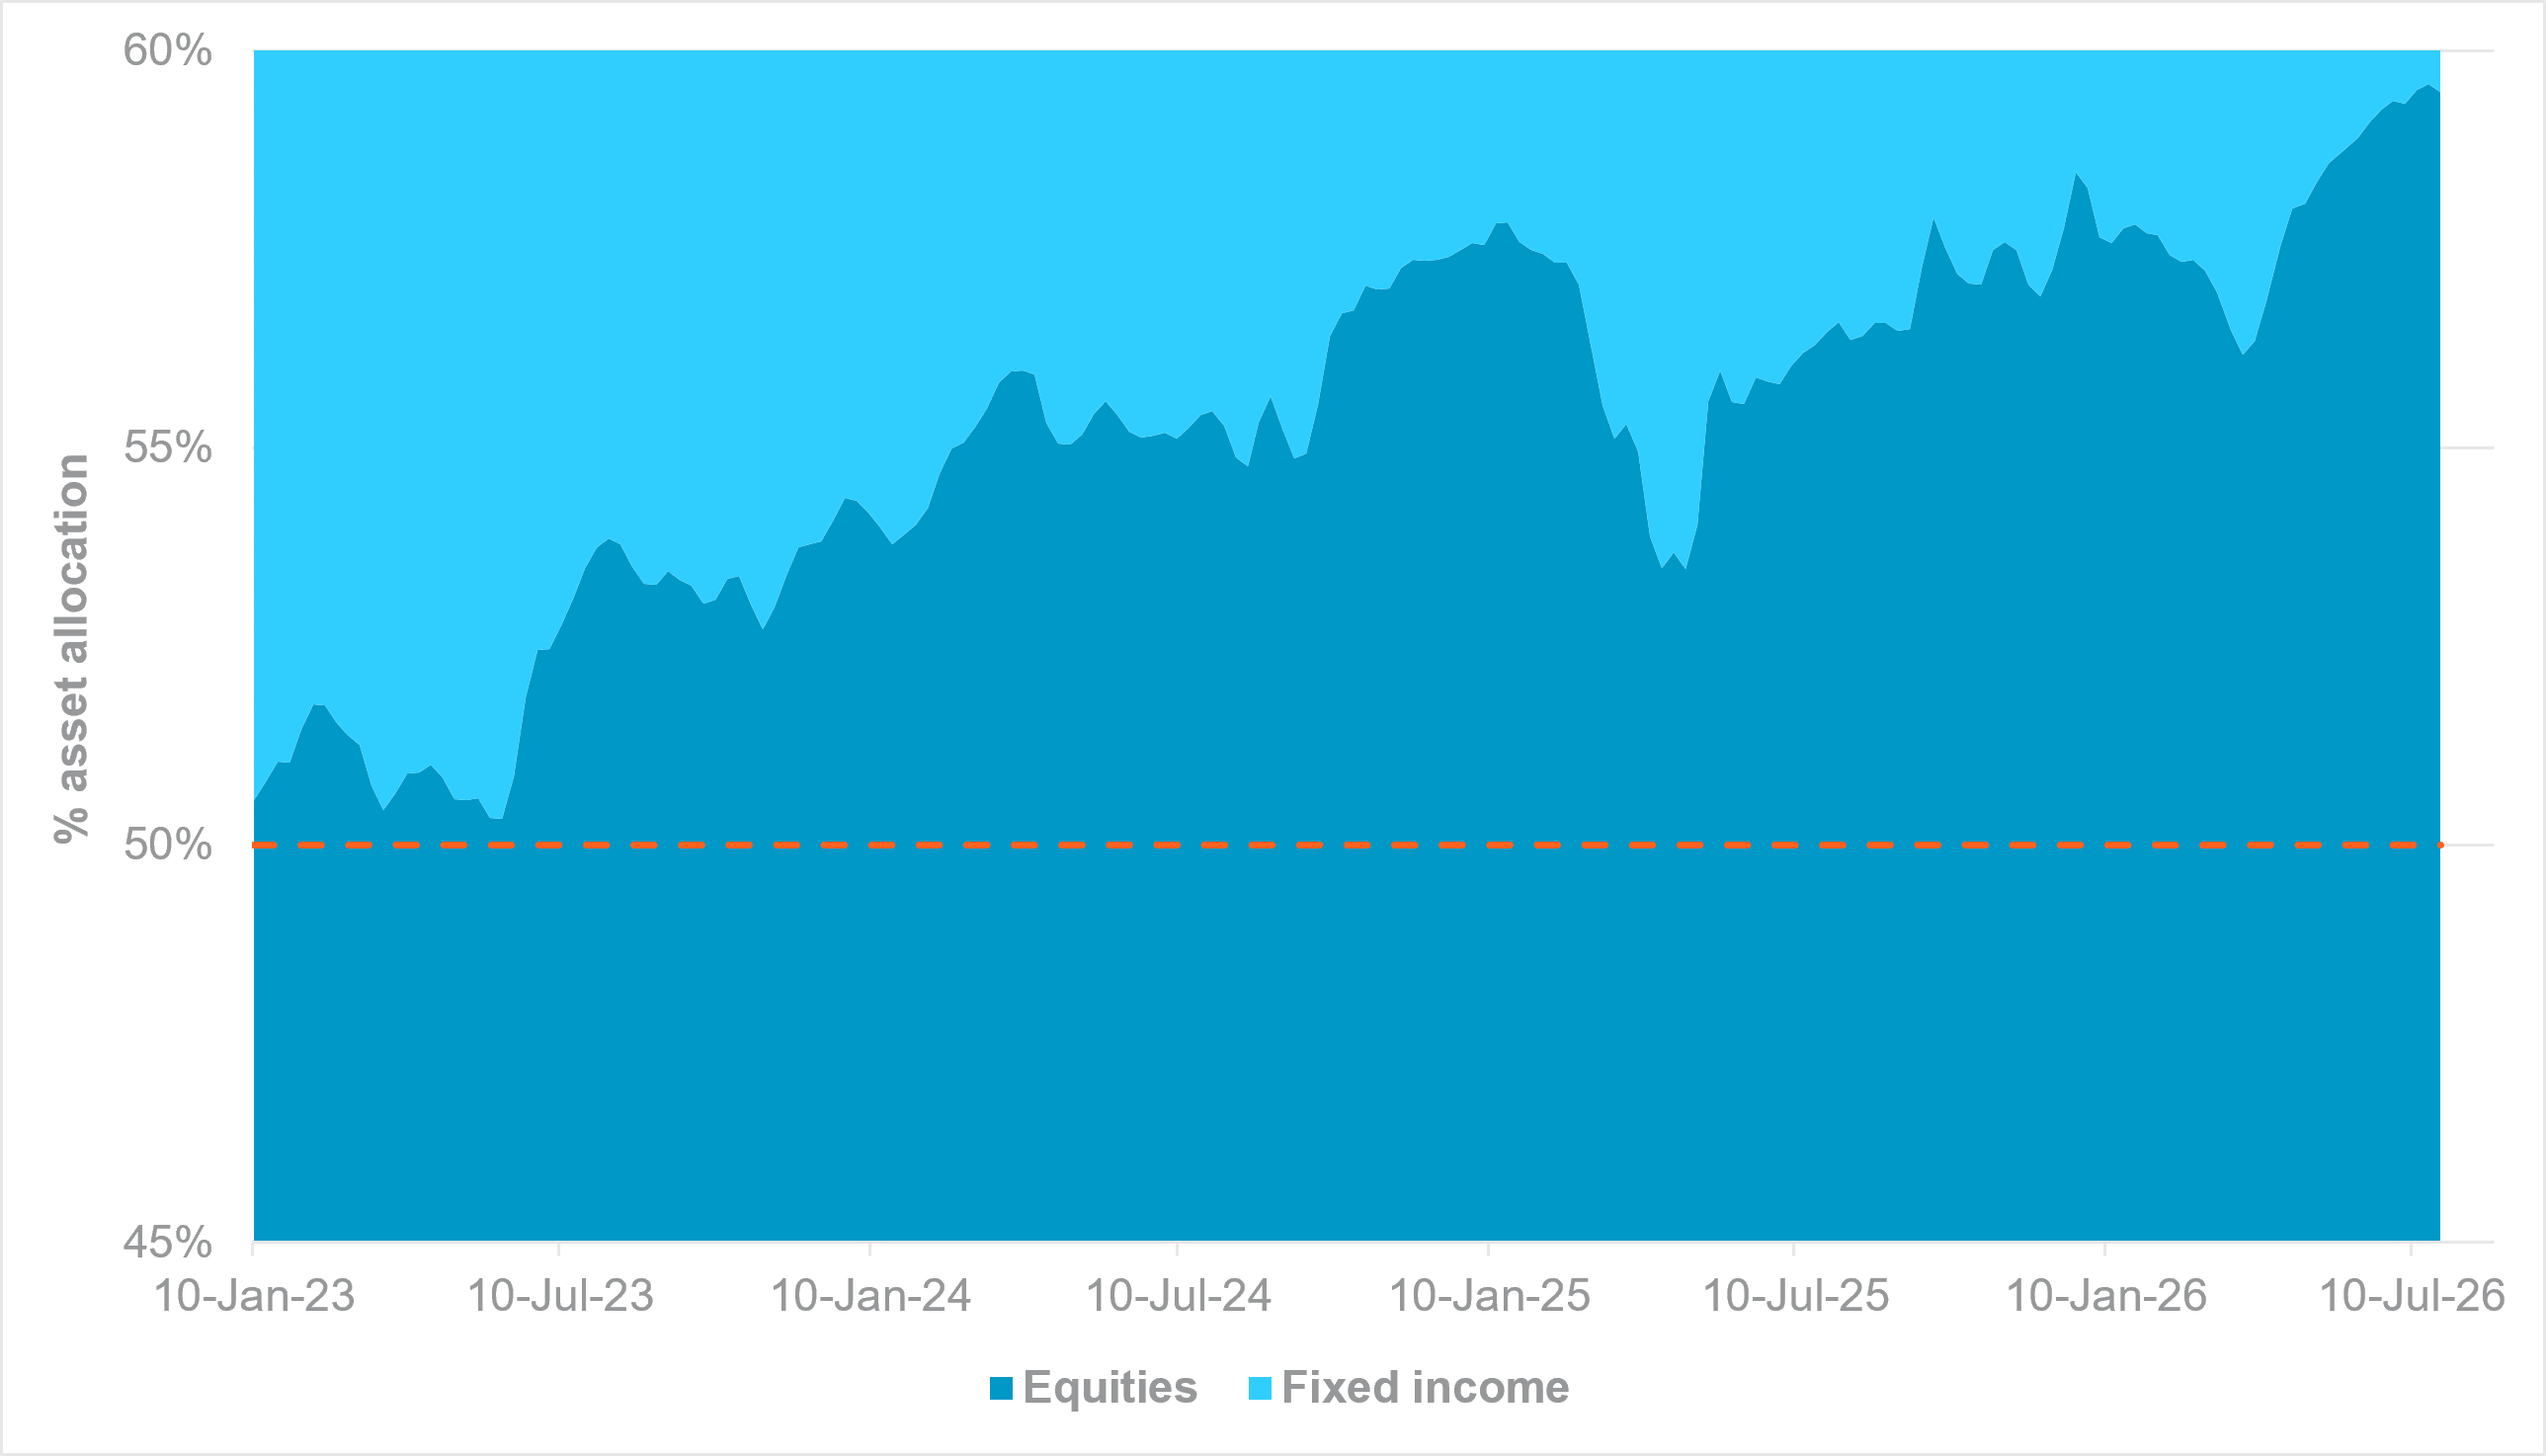
EXHIBIT #3: EQUITIES VS. FIXED INCOME WEEKLY ASSET ALLOCATION
Source: BNY
Our take
Dollar-selling signals from equity rebalancing are a welcome correction to stretched asset allocations. Equities accounted for 59.5% of total portfolio holdings at the end of last week, close to the early-July peak before the recent sell-off in memory-chip stocks. Relative to fixed income, equity exposure is now at a record high.
The U.S. accounts for 64% of global equity holdings and 73% of fixed income holdings. Because equity hedge ratios are typically lower, global portfolios carry an additional upward bias to dollar exposure. For non-U.S. investors, increasing dollar hedges is the cleaner way to reduce the U.S. contribution to portfolio volatility.
This is preferable to cutting U.S. allocations outright or rotating further into U.S. and global fixed income. Credible alternatives to U.S. assets remain limited, while bonds are likely to stay under pressure until inflation softens enough for markets to remove further rate hikes from the curve.
Forward look
We acknowledge near-term downside risk to global equity allocations, but the data suggest the rotation of the past three years is structural. In January and February, markets focused on the “debasement trade” as falling U.S. real rates weakened Treasury demand and encouraged more dollar hedging.
We expect central banks to pivot back toward growth at the earliest opportunity, with lower real rates likely to form part of that shift. Beyond dollar hedging, this should support rotation into economies that benefit from a softer dollar, particularly EM with less exposure to concentrated AI themes.
Global allocation is unlikely to swing decisively back toward fixed income. The more important shift may come within equities, where the regional and sector mix could change materially.
Add to USD hedges into month end and favor GBP as the main rebalancing expression. Keep INR hedging elevated after strong bond returns and treat any rotation away from U.S. assets as a shift within equities rather than a broad move into fixed income.